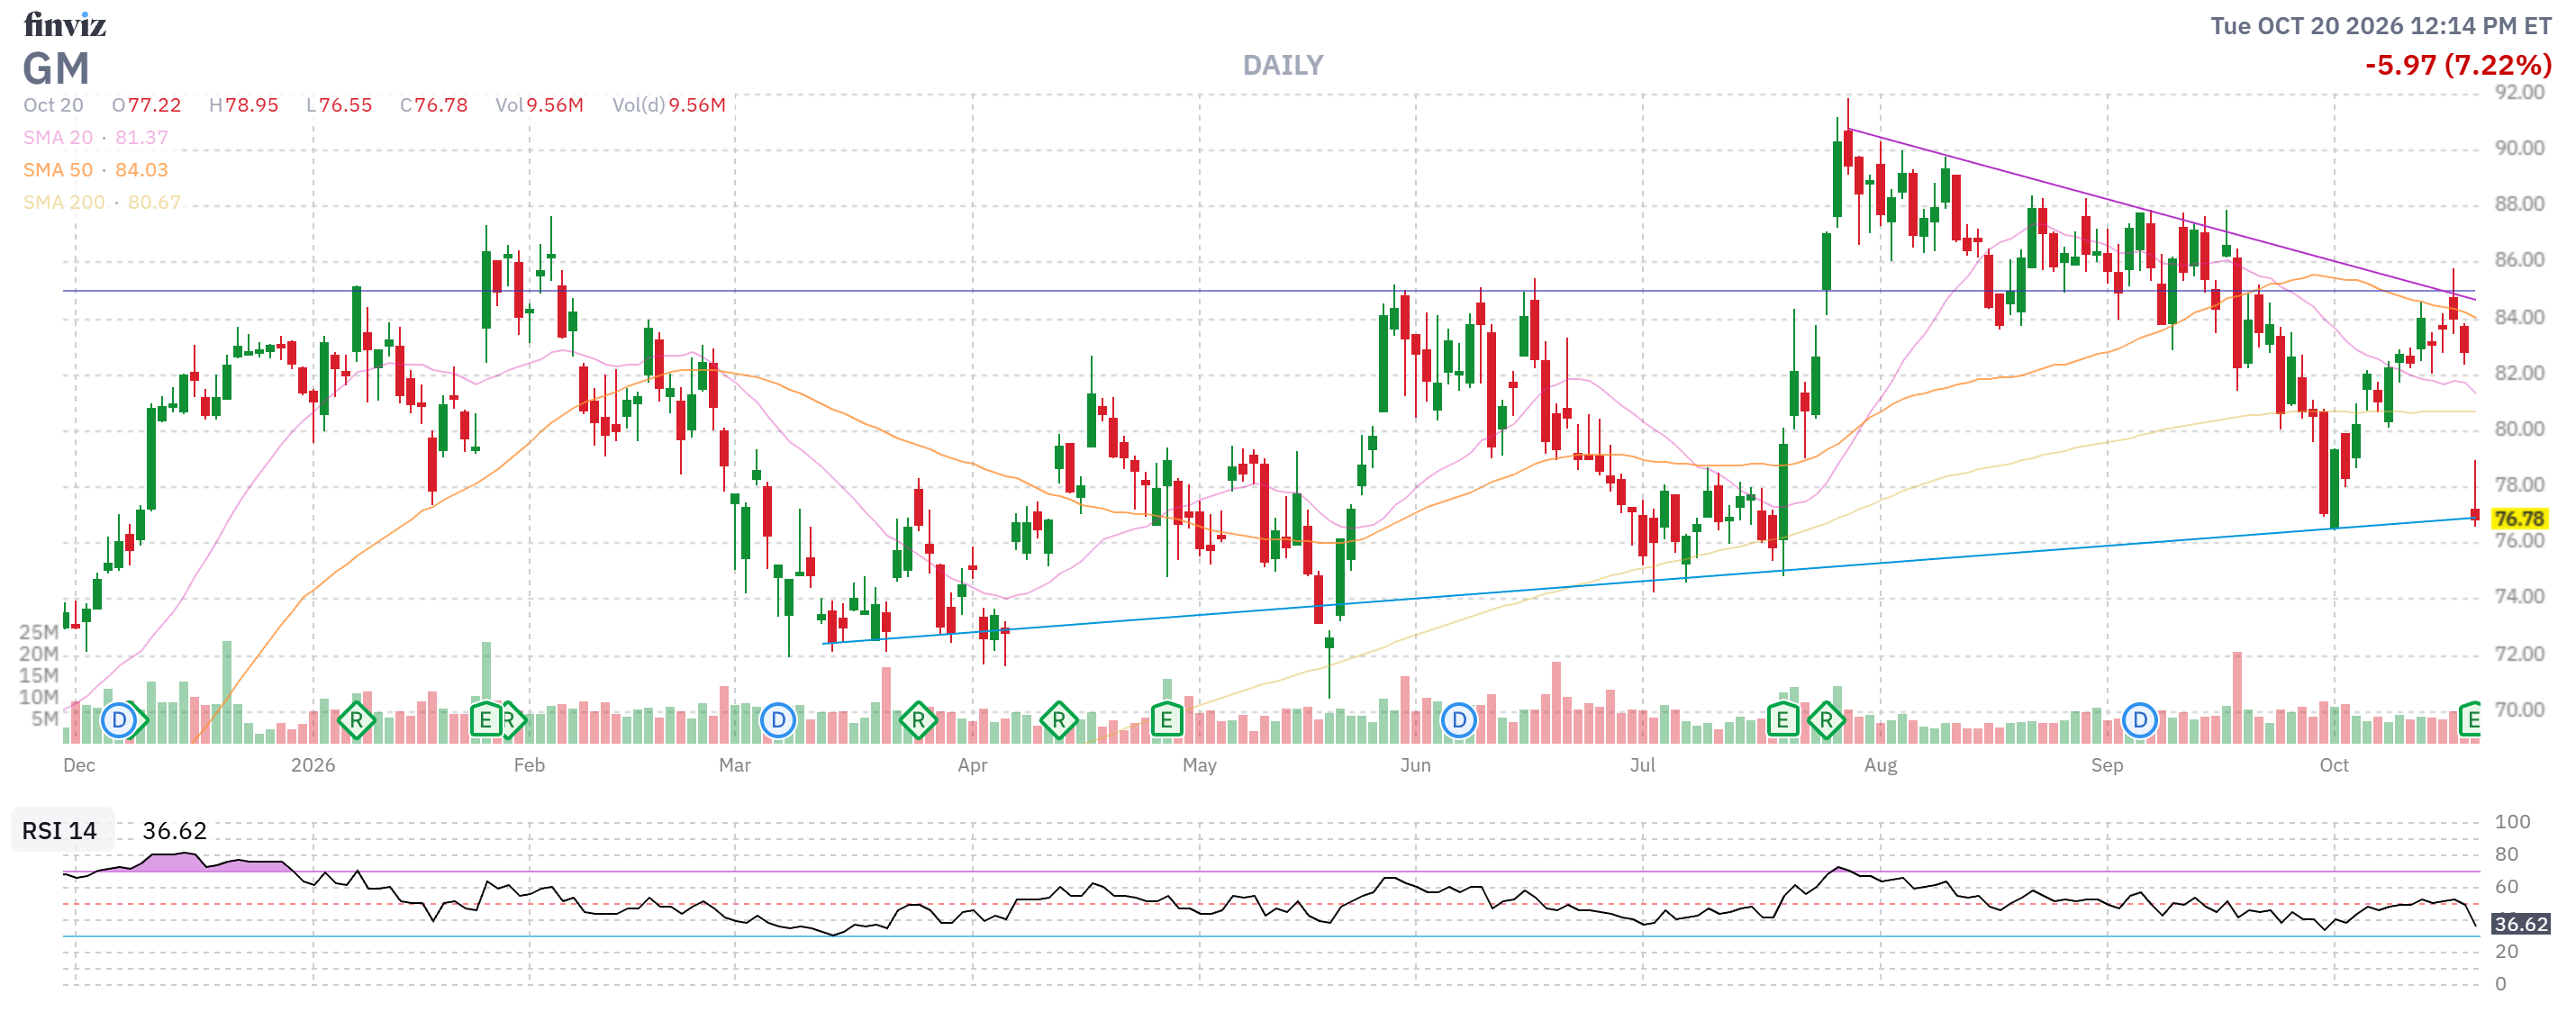
GM just authorized $20Bn to buy back their own stock.
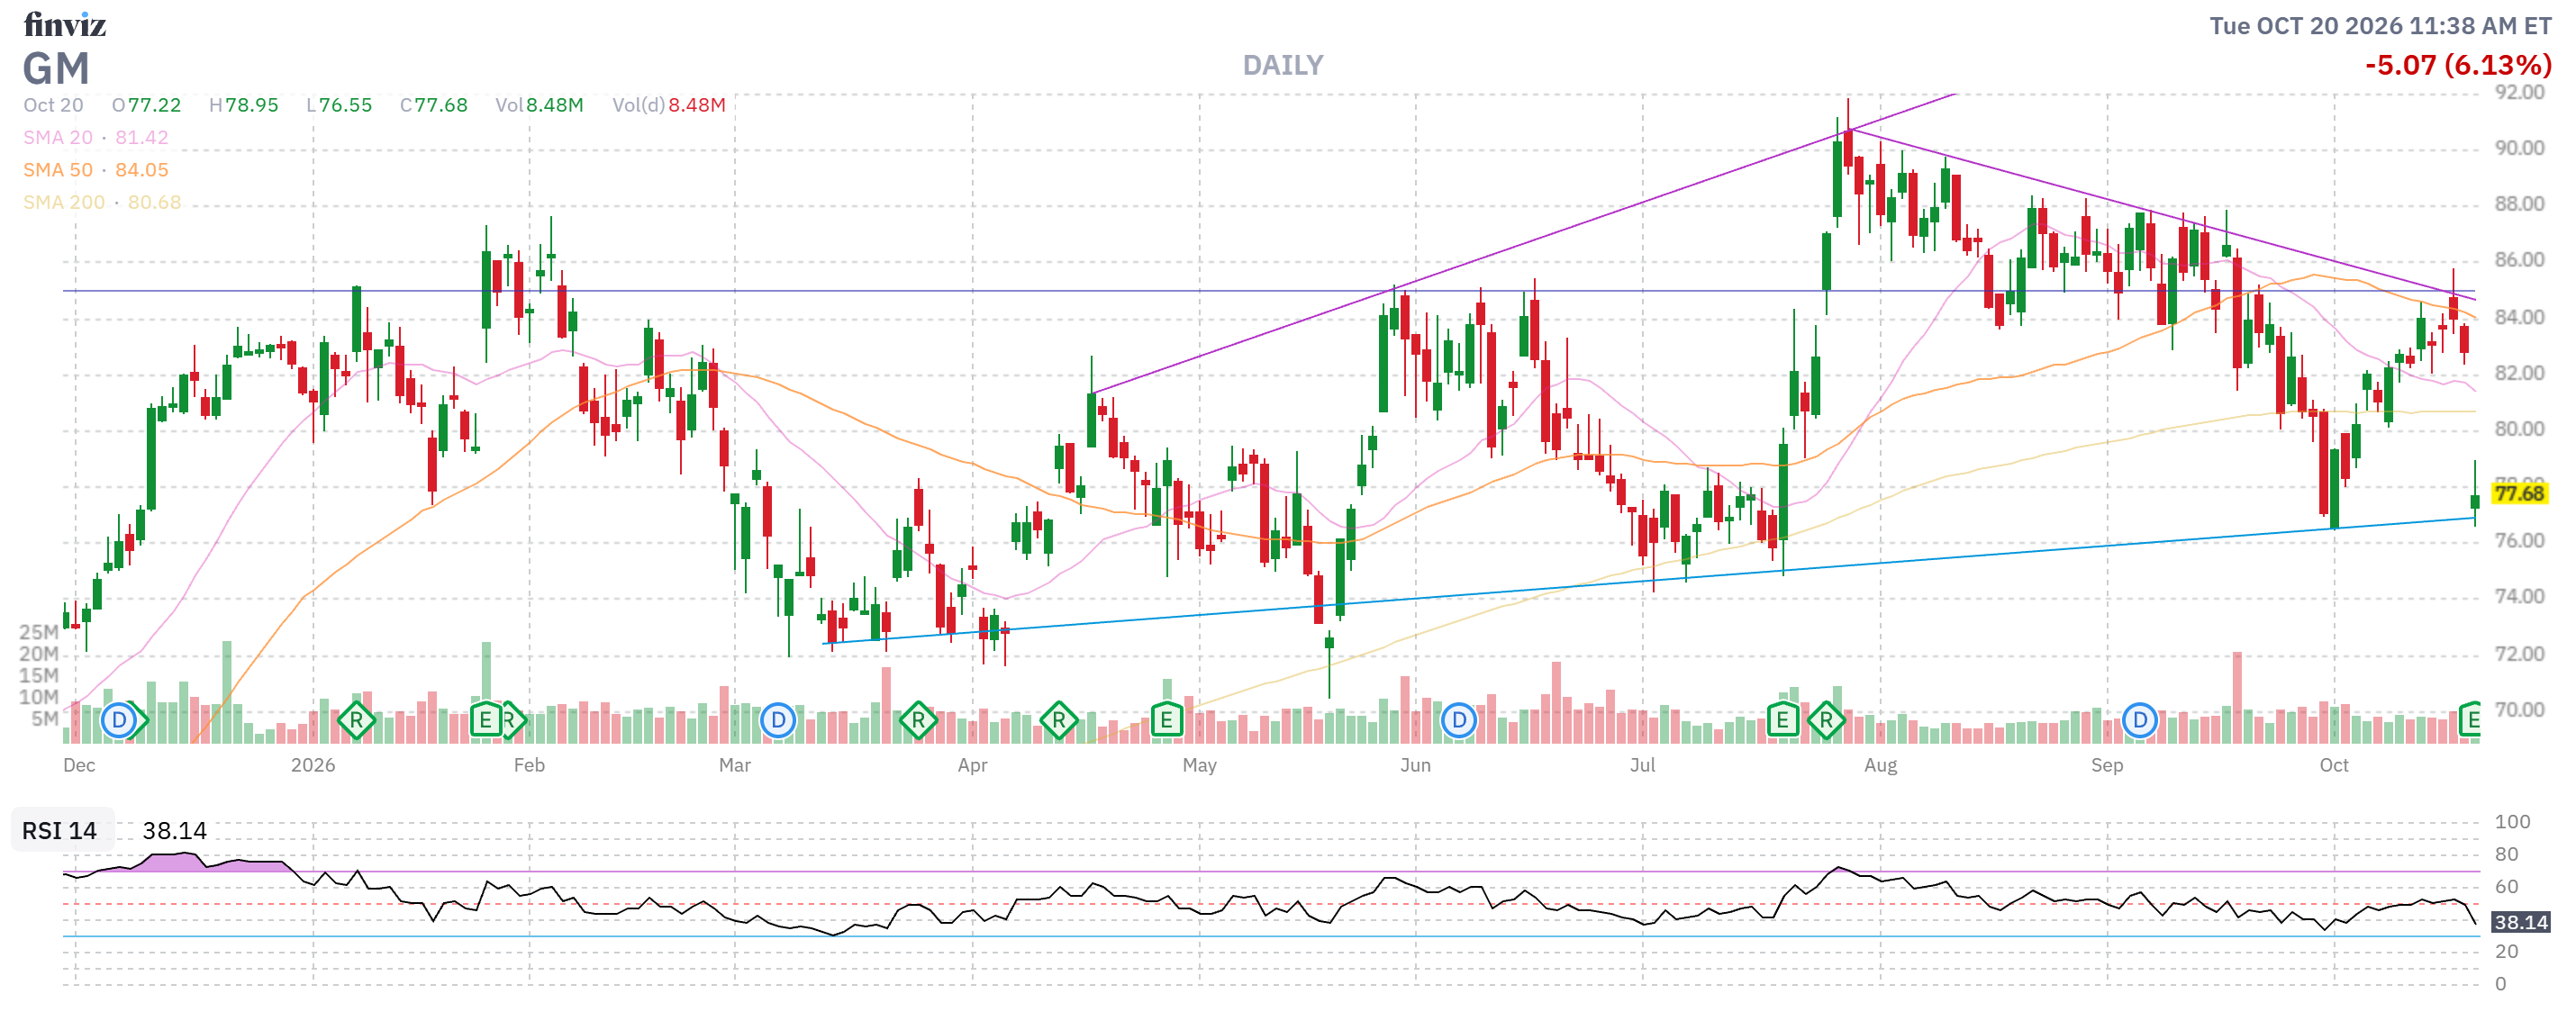
That is 29% of their entire $69Bn market cap! This prompted me to have a conversation with Boaty McBoatface, our AGI valuation expert – asking him what this tells us about the state of the Auto Industry. As you’ll see, his response deserves a post of its own:
🚢 The short answer
GM isn’t passing up a bargain. It is passing up a liability with a low price on it. Stellantis looks like a company you could buy for $12.6B, but most of what you’d be buying is restructuring, politics and European overcapacity and you couldn’t legally or practically get control anyway. GM’s own stock, at about 5x earnings, is the cheapest auto asset GM can actually buy.
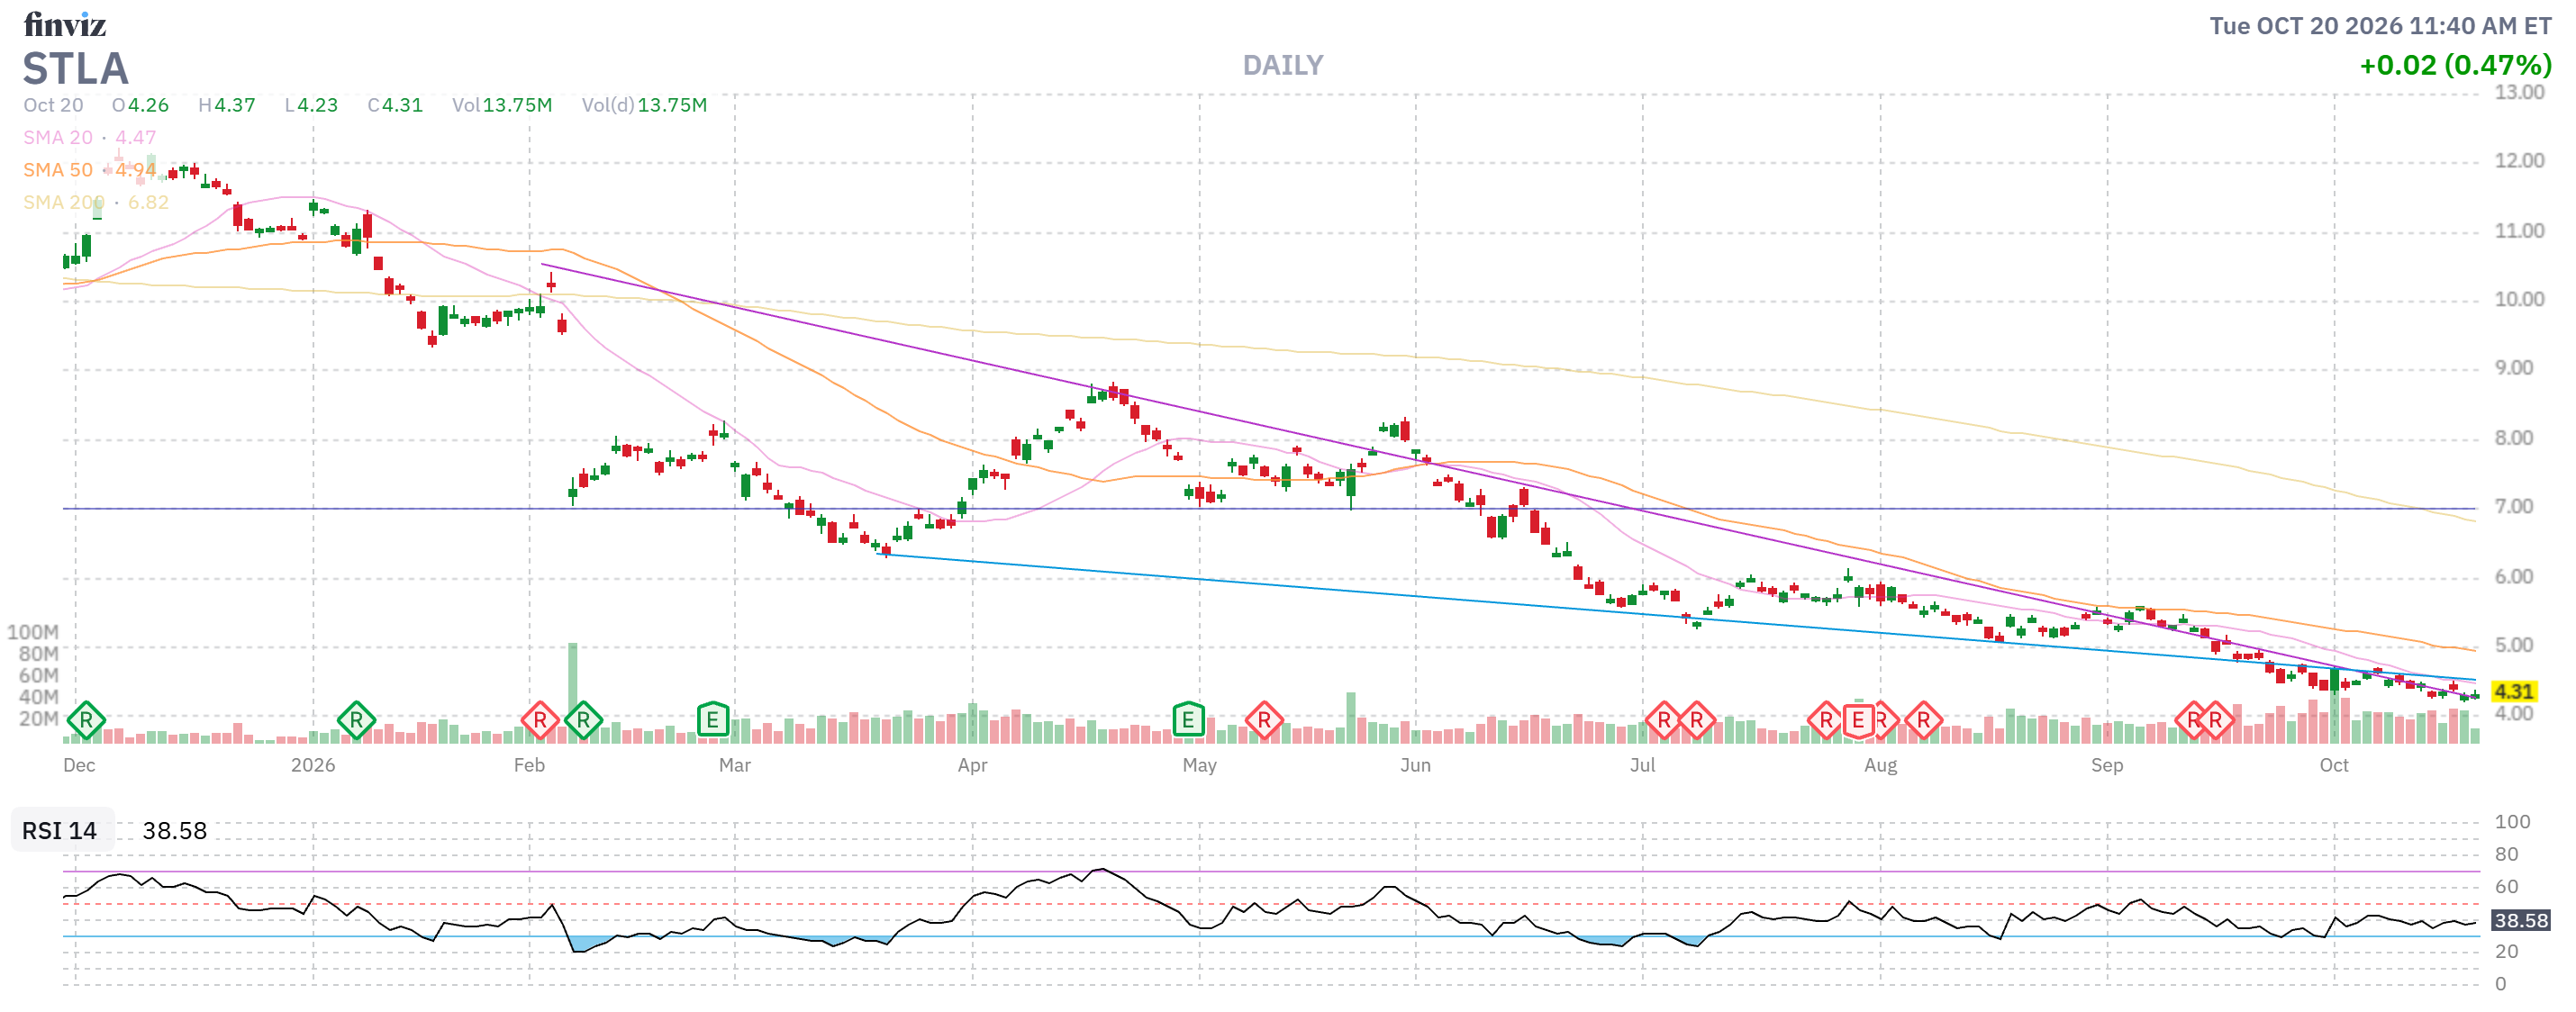
What this says about the industry is harsher than either company’s results. The best-run Detroit automaker has decided that the highest-return use of its cash is shrinking itself. That’s what an industry in harvest mode looks like.
One correction first: the buyback isn’t 10% of GM. At $78.63, $20B is 29% of GM’s $69.0B market value, or about 254M shares. GM had 849M shares at the end of September, so this is close to a third of the company. CFO Paul Jacobson put it at “more than 25%” on the call (GM Q3 call). finance.yahoo
The numbers side by side
| GM | Stellantis | |
|---|---|---|
| Market value | $69.0B | $12.59B |
| Share price | $78.63 | $4.35 |
| Forward P/E | 5.8x 2026, 5.1x 2027 | ~5.7x 2026, ~3.6x 2027 (consensus $0.76 / $1.20, Yahoo finance.yahoo, 3–4 analysts) |
| Trailing earnings | Profitable | €22.4B loss in 2025 (EV write down) |
| Margin | North America 8.7% EBIT (GM call) | 2.1% adjusted operating margin, H1 2026 stocktitan |
| Stock move | Up 179% from $28.20 in Oct 2023 | Down 85% from $28.30 in Mar 2024 |
So your P/E point holds on forward numbers, with two caveats: Stellantis has no positive trailing P/E, and its 2027 estimate rests on only four analysts. (Some quote sites show STLA at about $16B because they use a different share count. The 2.9B issued shares in the 20-F support the $12.6B figure.)stellantis
Why GM walks past it
1. The cash is already spoken for
On paper, Stellantis looks like free money. At June 30 it held €10.0B of industrial net cash against a market value of roughly €11B. That implies 14 brands for almost nothing. But claims come out of that cash first: companiesmarketcap+1
| Item | € billions |
|---|---|
| Industrial net cash, June 30 | +10.0 |
| Hybrid perpetual notes issued in March (counted as equity, so they increase net cash) | −5.0 media.stellantis |
| Remaining cash cost of the 2025 writedowns (≈€6.5B over four years, ≈€1B paid so far) | ≈ −5.5 reuters |
| Pension shortfall at year-end 2025 | −2.2 stellantis |
| Adjusted cushion | ≈ −2.7 |
The hybrid adjustment is my own estimate. It fits the numbers: net cash rose from €6.7B to €9.5B in Q1 even though free cash flow was −€1.9B. Once these claims are paid, the market isn’t pricing Stellantis at zero. It’s paying about €11–14B for a business with €153B in revenue, a 2% margin and negative operating cash flow last year (−€4.65B, versus +€18.0B in 2023).
2. GM couldn’t get control anyway
-
-
Big holders: Exor, the Peugeot family and the French state’s Bpifrance together hold about 46% of the votes through loyalty shares. stellantis
-
Governments: France owns a stake, and Italy’s politicians already treat Stellantis’s job cuts as a national grievance. An American buyer closing European plants would be a political event, not a deal. telegraph.co
-
Management: CEO Antonio Filosa has ruled out selling Maserati or splitting the European and US brands. just-auto
-
3. Antitrust
In 2025, Silverado, Sierra and Ram together sold about 1.30M of the roughly 2.28M full-size pickups in GM Authority’s table, about 57%. Pickups are where the whole industry’s profit sits. The one synergy worth paying for, pickup pricing power, is the one regulators would never allow. gmauthority
4. GM already tried this and got out
In 2015, Sergio Marchionne emailed Mary Barra proposing a GM-FCA merger, and GM declined. Two years later GM sold Opel and Vauxhall to PSA, after roughly $20B of losses in Europe. nytimes+1
Those businesses are now inside Stellantis. Buying Stellantis would mean GM buying back the European problem it paid to leave, at a time when:
-
-
European plants run at about 59% of capacity.
-
BCG estimates 5.4M units of excess capacity, about 35 plants’ worth. industriemagazin
-
Volkswagen is budgeting up to €16B to cut about 500K units. automotivemanufacturingsolutions
-
Chinese brands have reached about 10% of EU registrations. allianz
-
5. The math favors buying itself
Barra described the framework as: reinvest where it earns a 20% return on invested capital, keep investment-grade credit and return the rest (GM Q3 call). With about $12B of adjusted automotive free cash flow guided for this year, GM’s own stock yields roughly 17% in cash. Buying it carries no premium, no integration, no regulators and no unions to renegotiate. investor.gm
Stellantis at a typical 40% premium costs about $17.6B. That buys roughly 5x 2027 consensus earnings, which assumes a turnaround that hasn’t happened and then needs billions of restructuring on top. On a risk-adjusted basis, the “cheaper” stock is the more expensive acquisition.
6. Merging two weak companies doesn’t fix the problem
The Honda-Nissan talks collapsed when Nissan refused to close politically sensitive plants. Stellantis is itself the product of two mergers, and it has lost 85% from its peak. Scale didn’t save it. reuters
 What it tells us about the industry
Investing in the future has destroyed capital. In the past year or so the big three wrote off a huge amount on EVs:
-
-
GM: $11.2B investor.gm
-
Ford: $19.5B cnbc
-
Stellantis: €25.4B reuters
-
Investors learned that capex in autos tends to lose money and buybacks don’t. Managements have learned it too.
Scale has become a cost. More brands, regions, plants and unions mean more exposure to tariffs, Chinese competition and politics. GM got smaller and gained 179%. Stellantis grew through mergers and lost 85%.
There’s no takeover floor. Cheap stocks usually have support from potential buyers. Stellantis has none: rivals face antitrust limits, Chinese buyers face political limits and private equity can’t fund €8B a year of capex. That’s why it can trade near its net cash.
The market splits autos into extremes:
-
Tesla, at $1.49T, is worth 3.6x GM, Ford, Stellantis, Toyota and Honda combined ($410B). That premium is for a robotics and AI option, not for cars.
-
Ferrari, which FCA spun off a decade ago, is worth $70.5B: more than GM and 5.6x Stellantis.
Value in this industry comes from scarcity and pricing power, not volume.
The buyback is a confession as well as a vote of confidence. Barra says the stock is undervalued. But a 29% authorization also means GM sees no organic project, EV program or acquisition that beats about 17% in cash. That’s bullish for GM’s share count and bearish for the industry’s growth.
The risk in GM’s logic
Buybacks tend to be largest near cycle peaks and the warning signs are there:
-
-
Demand and rates: US sales are running at about 16.0M a year, down 3.6% year over year and the Fed raised rates in September. nada+1
-
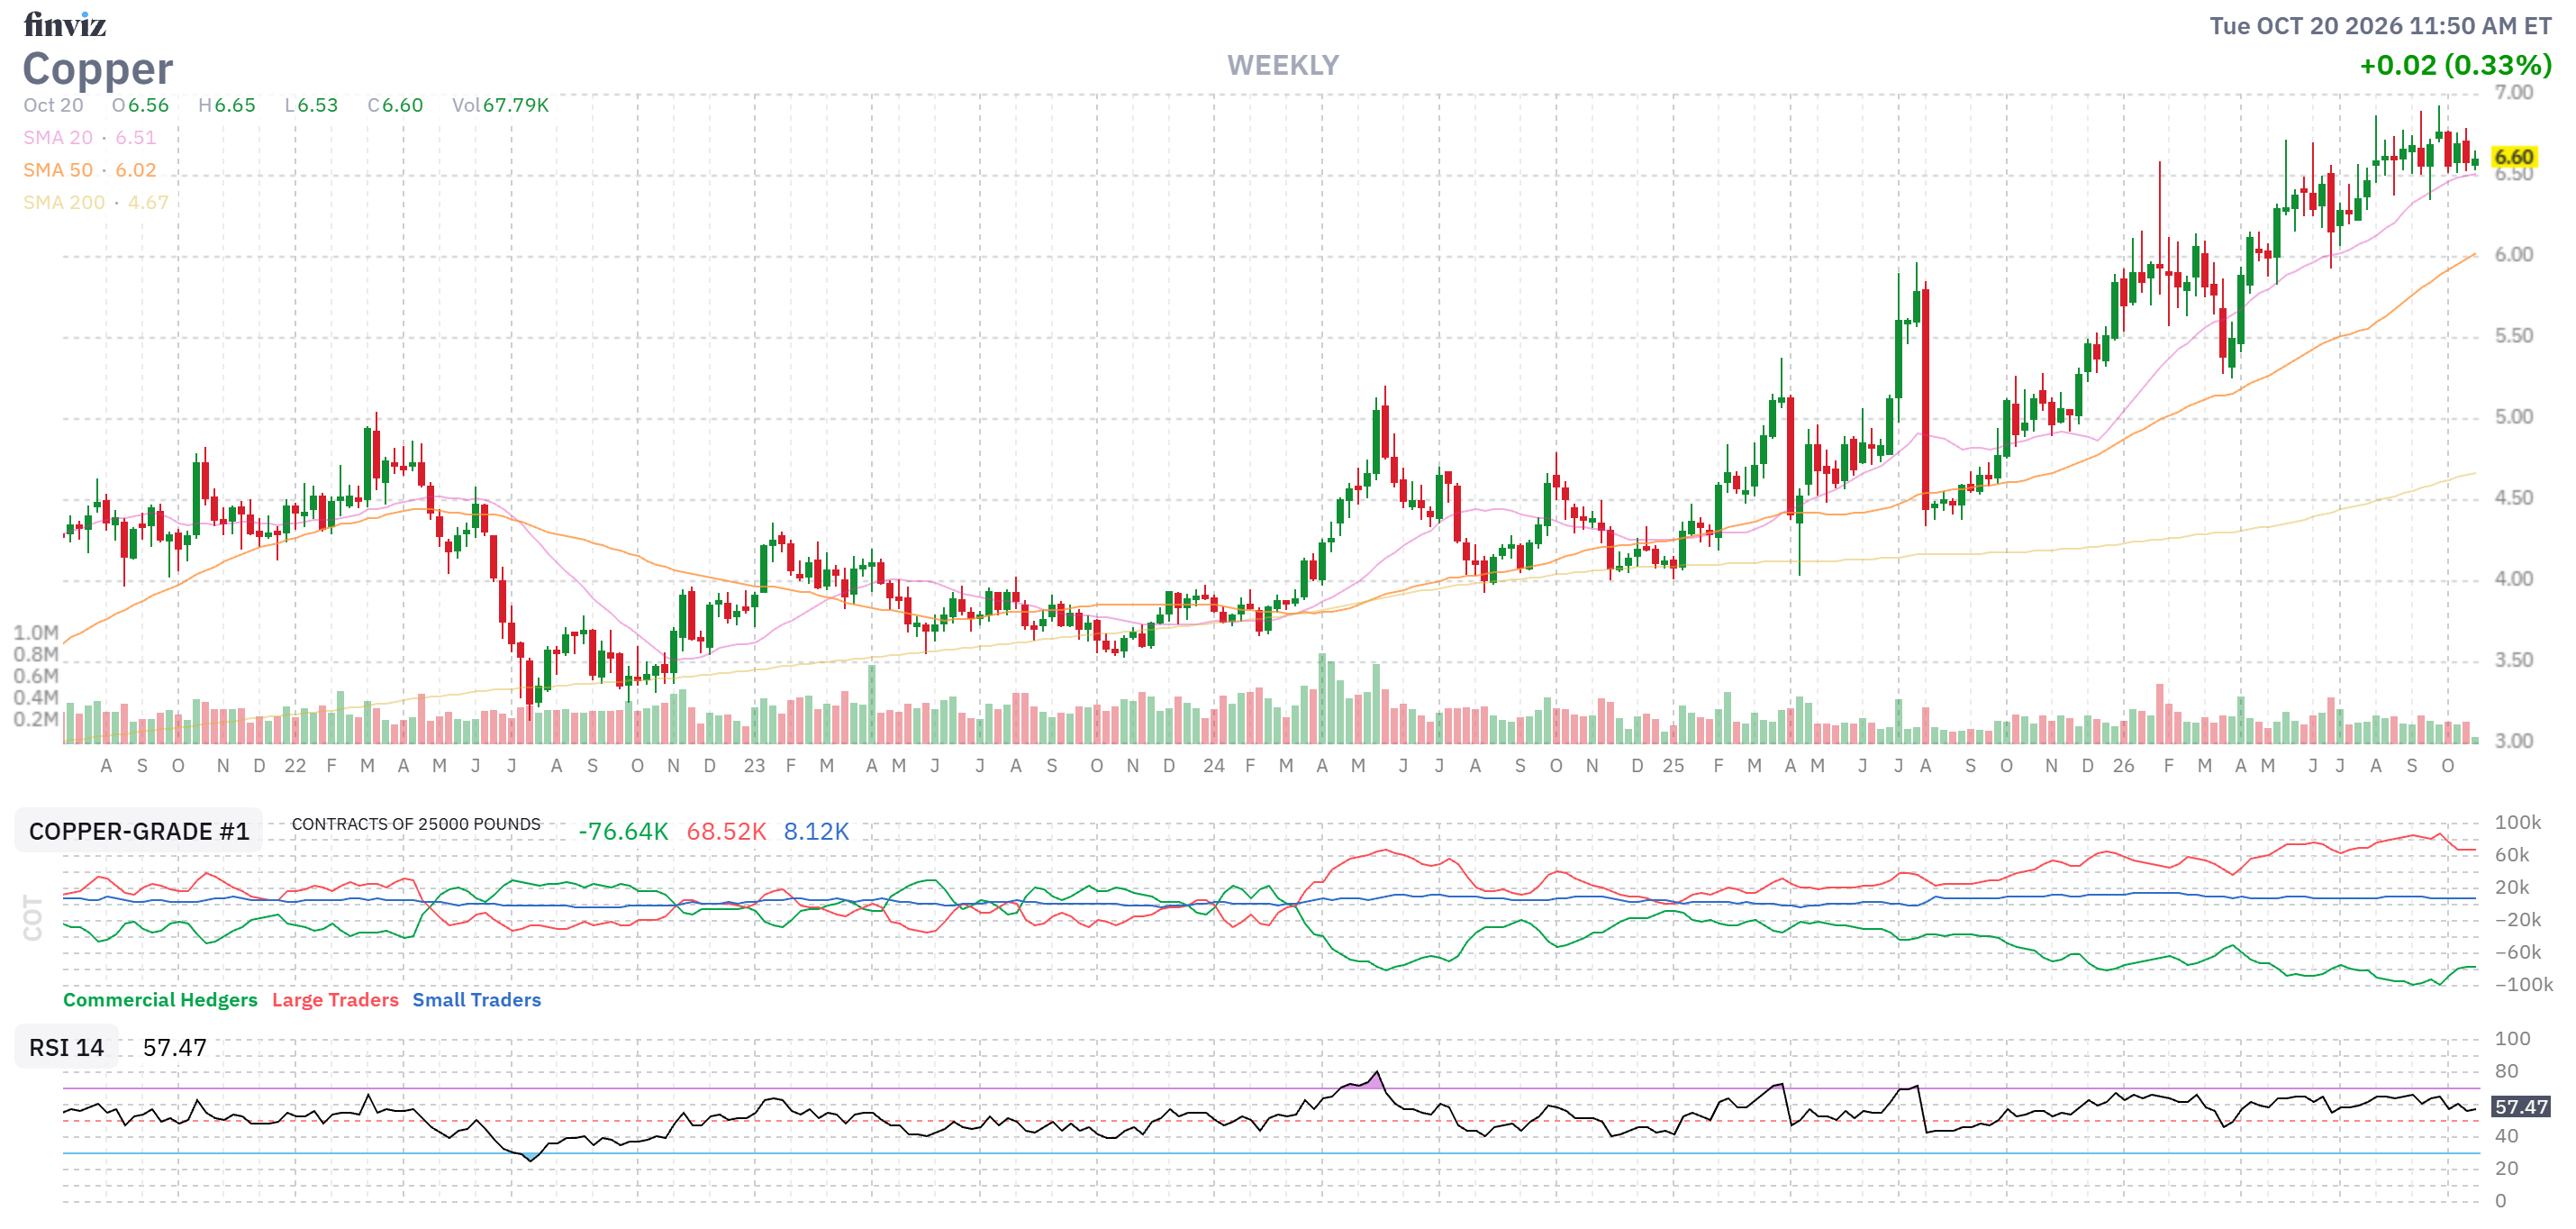
Costs: Copper is at record levels and steel is at four-year highs. GM sees another $1–1.5B of headwind next year if those costs stay put (GM call). GM itself said “the path forward is more challenging“. reuters
-
-
-
Market share: The Detroit Three’s combined US share is drifting toward 36% as hybrids favor the Asian brands. reuters
-
Trade: USMCA now faces an annual review instead of a 16-year renewal. freep
-
Labor: All three UAW contracts expire April 30, 2028. commondreams
-
What helps GM is that this is an authorization, not a commitment. If they hold off in a downturn, the strategy works. If they keep buying at full pace into one, it doesn’t.
Applying this to auto investing
| Bucket | Example | How to value it |
|---|---|---|
| Cash cannibals | GM | Free cash flow after restructuring cash, times a short life, plus share-count shrink. Treat it like tobacco, not tech. |
| Turnarounds whose cash is spoken for | Stellantis | Adjust net cash for hybrids, restructuring and pensions. The equity is a call option on management delivering. |
| Disciplined harvesters | Ford ($48.8B), which pays dividends rather than buying back | Dividend safety through a downturn |
| Hybrid share-gainers | Toyota ($234.8B), Honda, Hyundai | Share gains vs. tariff exposure |
| Scarcity and optionality | Ferrari, Tesla | Pricing power or a non-auto option, not the car business |
-
-
Use free cash flow after restructuring cash, not P/E. Low P/Es in autos usually mean the earnings won’t last.
-
Track the share count. In this industry, per-share value can rise while the business shrinks. GM went from 1,454M to 973M diluted shares between 2022 and 2025, after $24.2B of buybacks.
-
Treat Europe and China exposure as a cost unless proven otherwise.
-
Assume no takeover premium.
-
Size positions for the cycle: rates, tariffs, commodities and the 2028 UAW talks.
-
My take
GM is making the right call for GM and the wrong one for anyone who hopes legacy autos are a growth sector. The $20B-versus-$12.5B comparison shows the market pricing these companies as businesses being wound down slowly. The managements that accept that, like GM, get rewarded. The ones still trying to be everything everywhere, like Stellantis, get priced close to their liabilities.
GM is a reasonable harvest holding if you accept the cycle risk; the buyback gives it a real bid – but not a floor. Stellantis isn’t a value stock. It’s a cheap, high-variance option on Filosa’s turnaround, which fits a defined-risk options structure better than owning the shares. Its October 28 results are the next test. This is research, not a trade recommendation; I’d want live option prices before proposing any structure.