Woops!
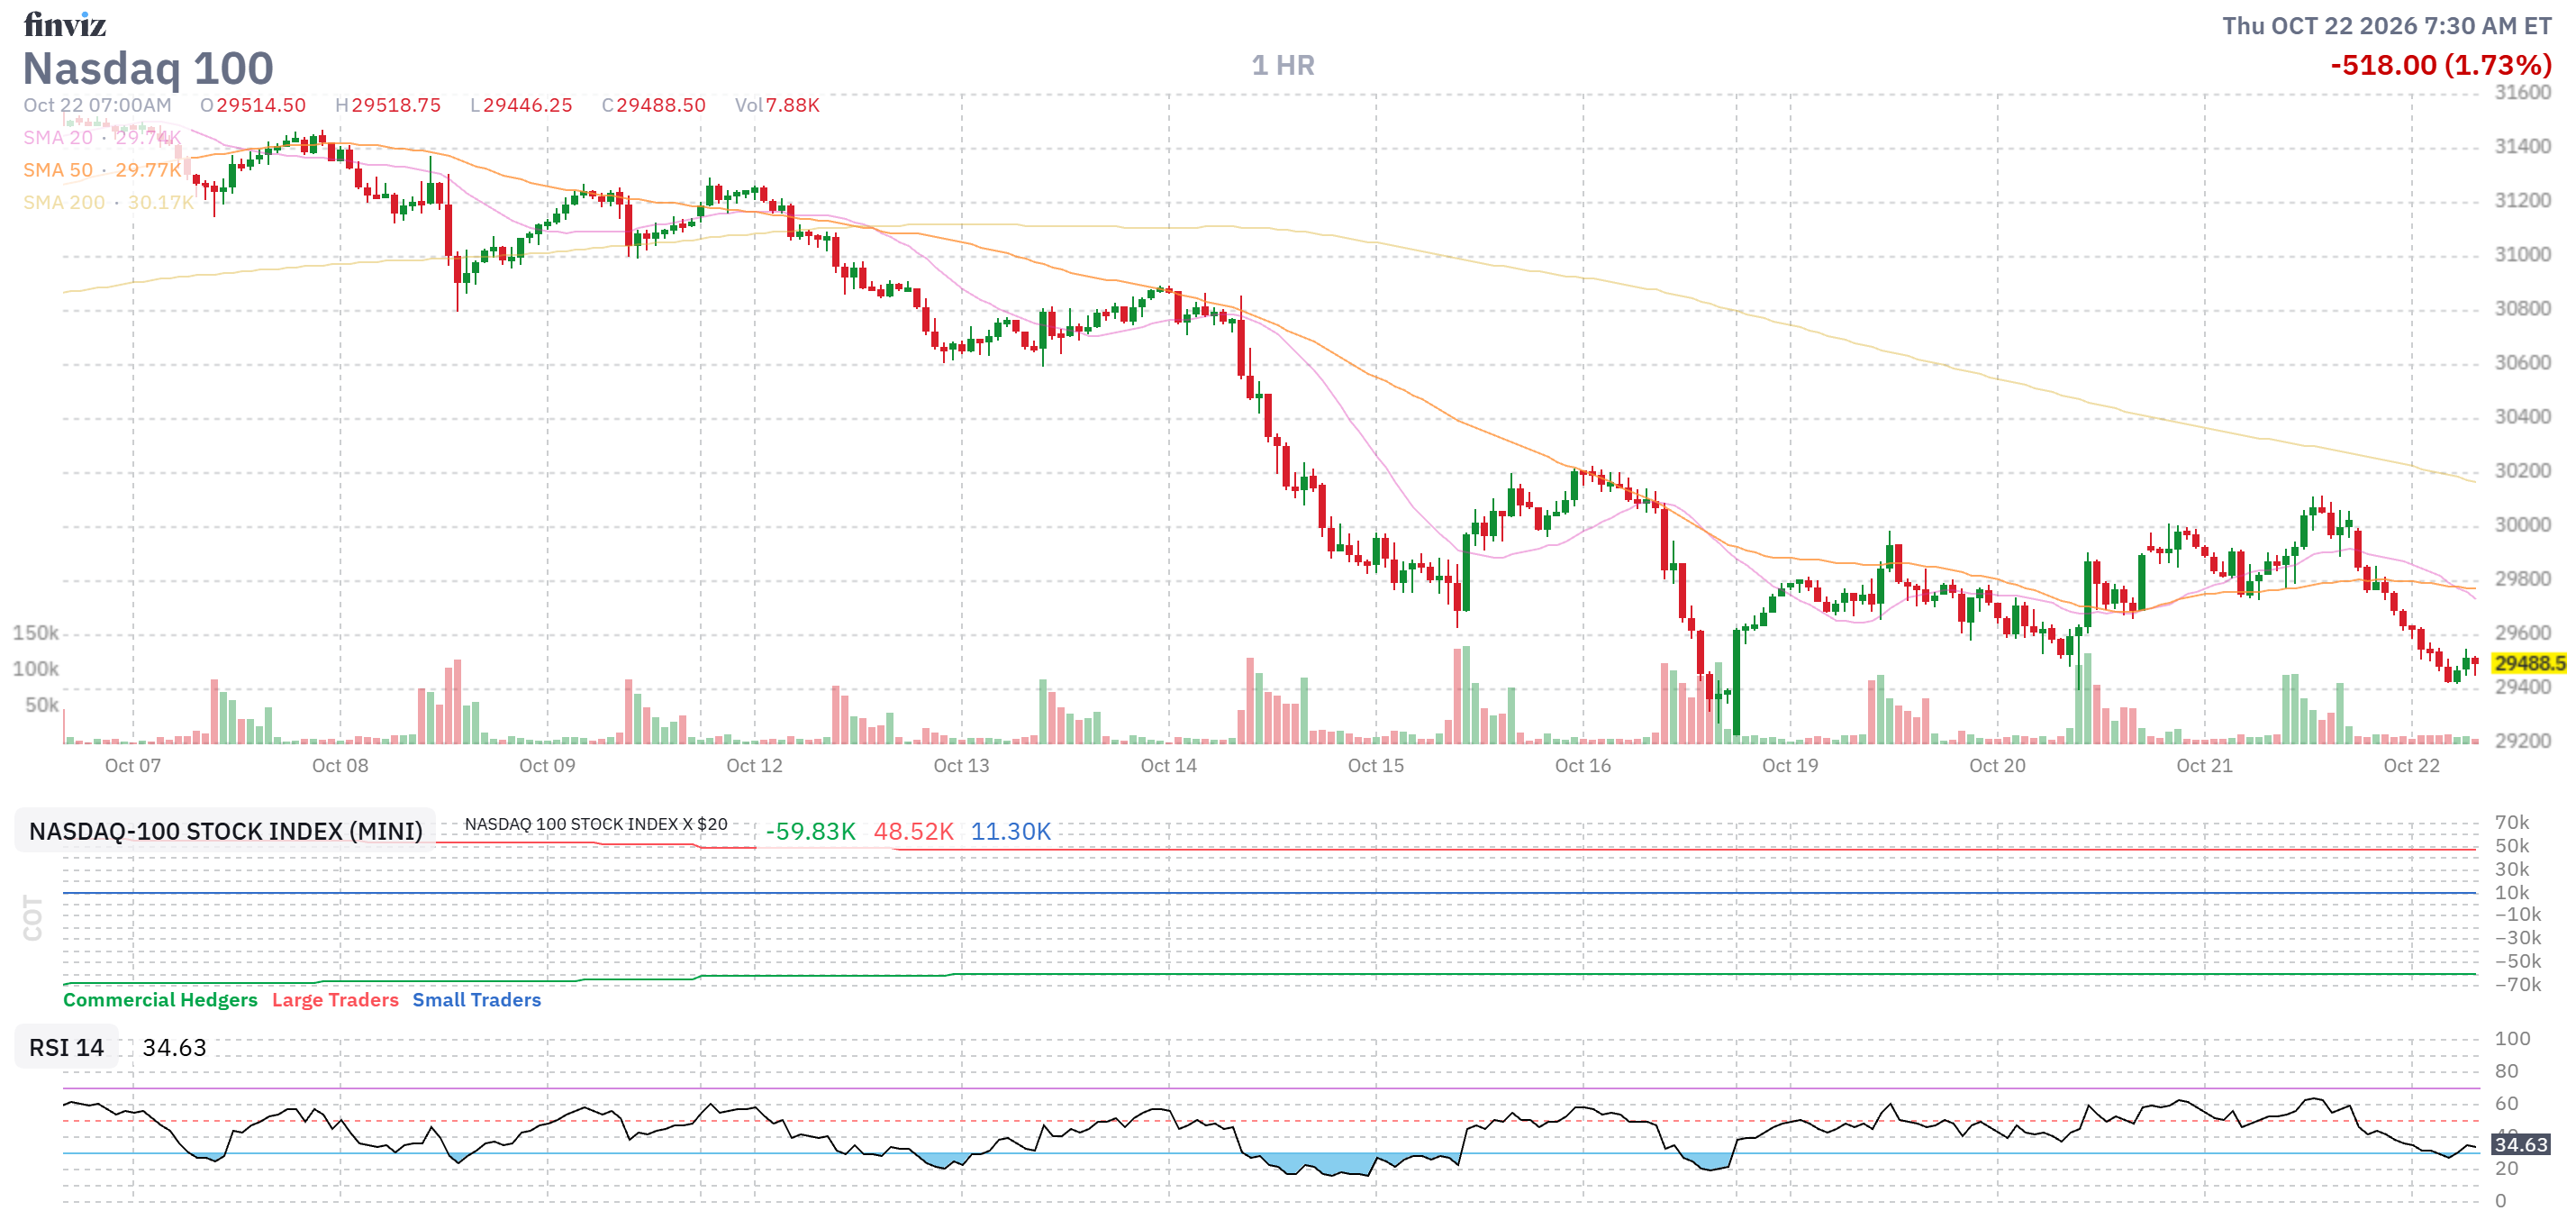
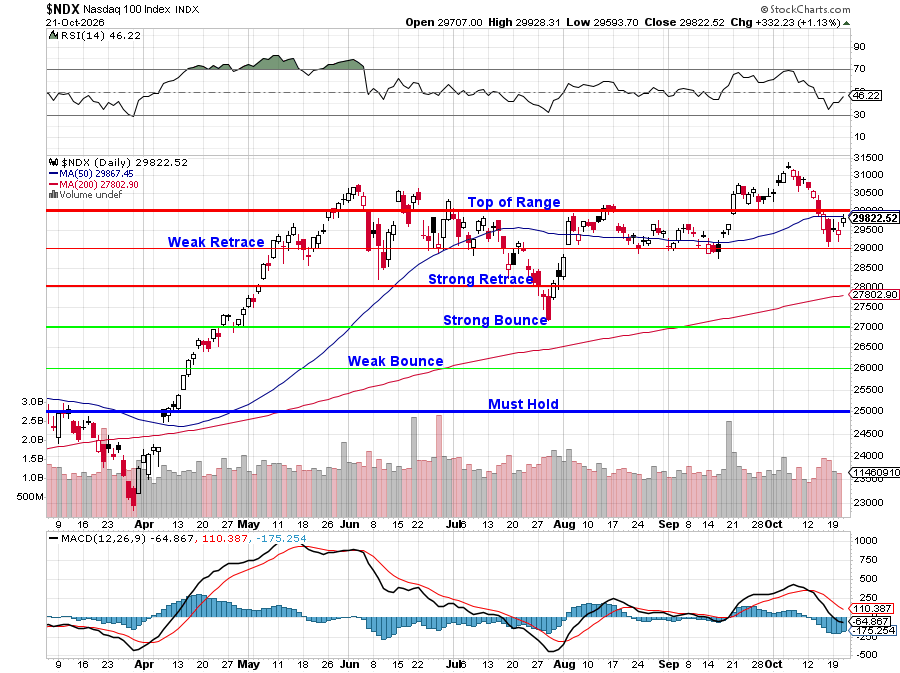
We’re back to Friday’s close at 29,400 on the Nasdaq – down a quick 500 points this morning after a comically low-volume rally that began Friday evening – AFTER the close. If we take a look at the bigger chart, we can see that the Nasdaq has been rejected at the 50-day moving average at 29,867 (and 30,000 on the above Futures) and that is, technically, NOT GOOD!
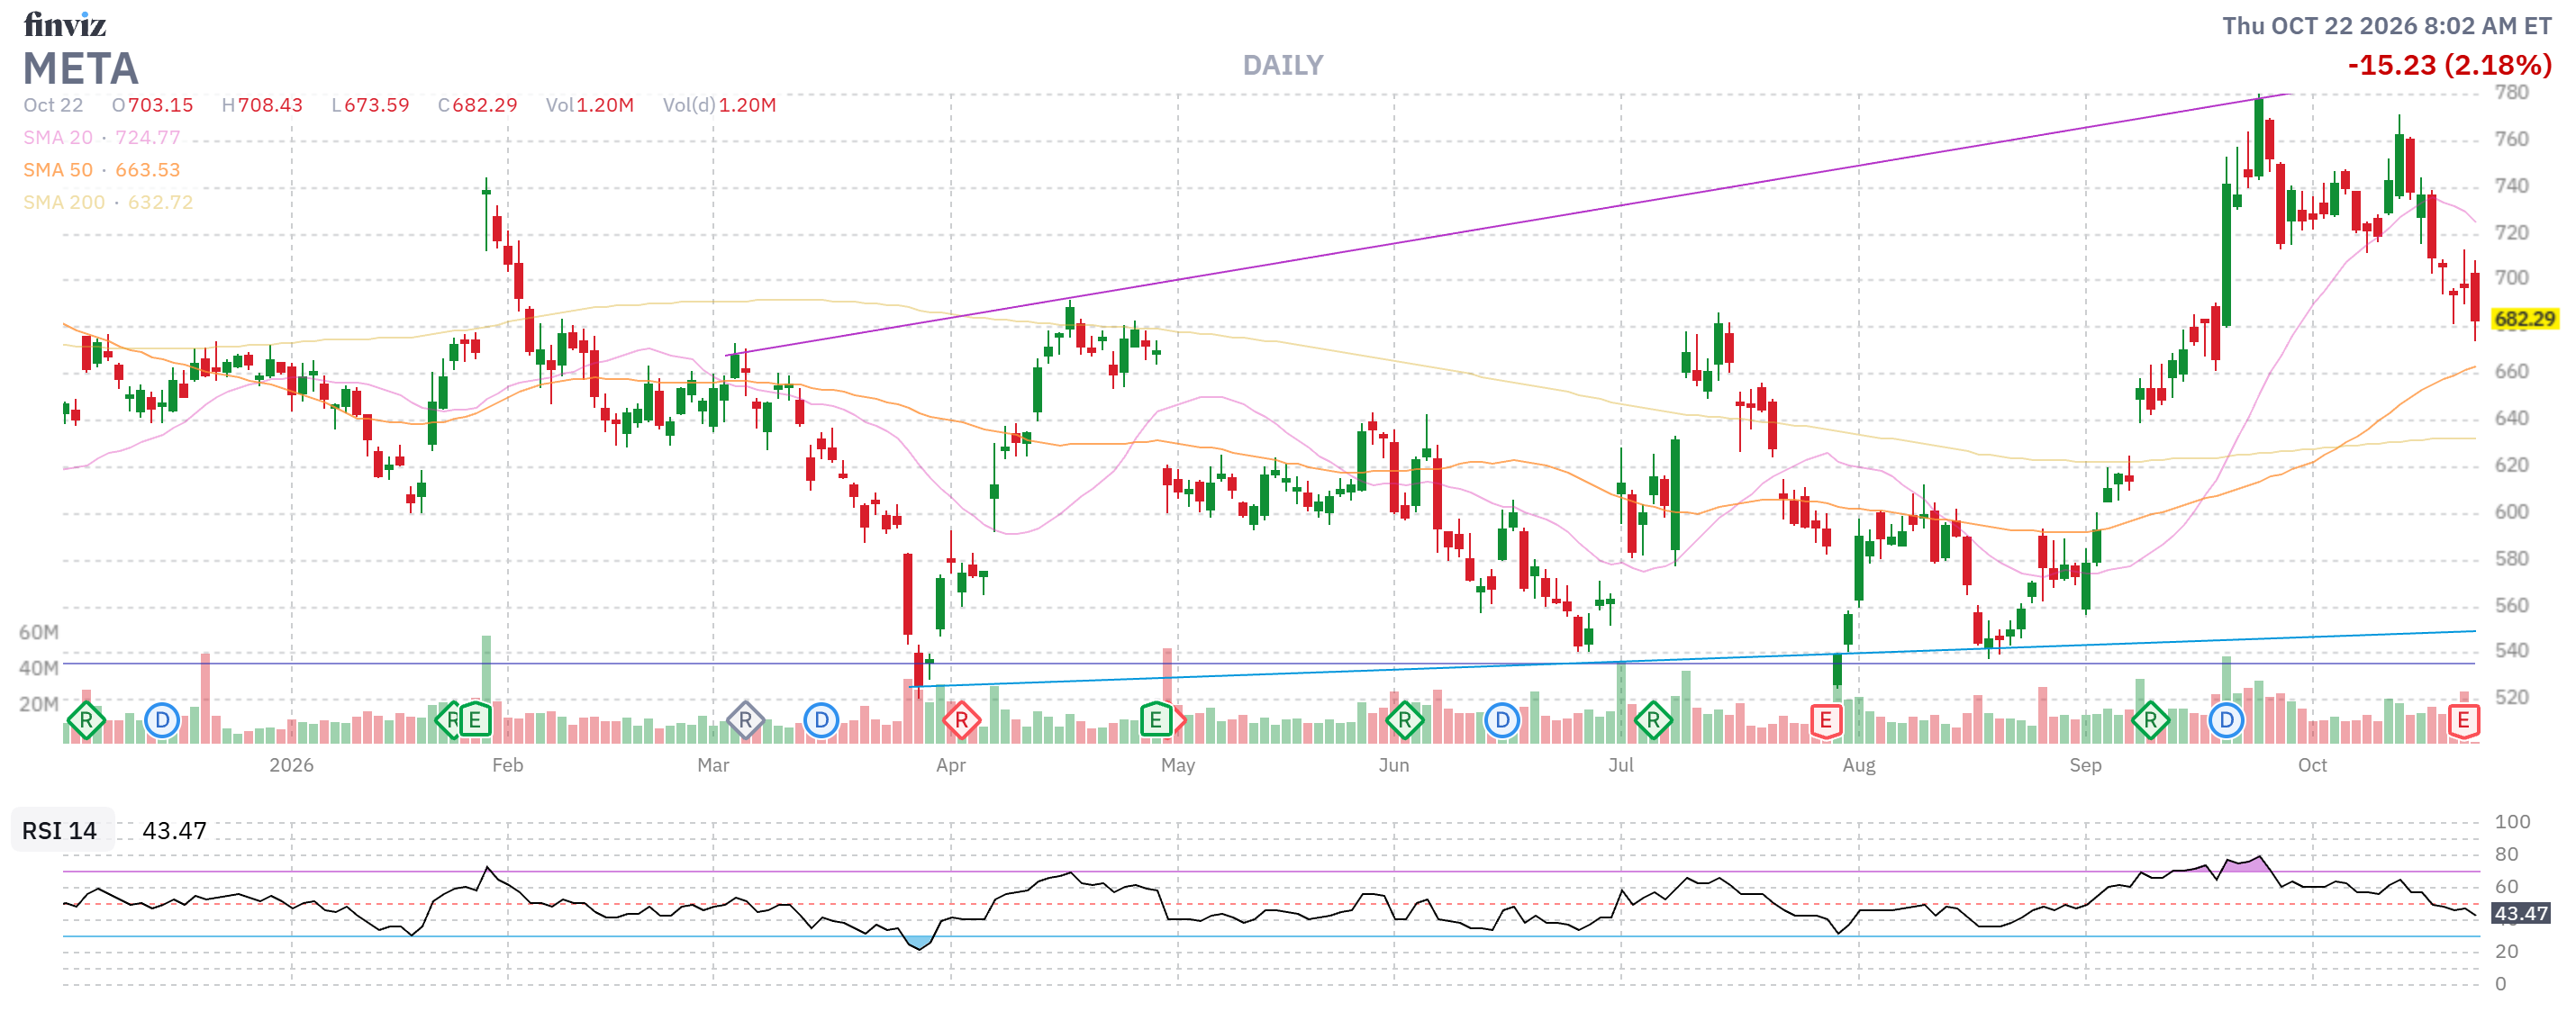
Specifically, we took a few hits last night as META beat on Revenues (up 26% to $64.6Bn) but they are spending $140Bn to get there and now they are creating a class of non-voting shares, in a 2:1 stock split, to fund further AI spending – solely so the owner, Mark Zuckerberg, can keep borrowing money without being stopped by other shareholders, who will become massively diluted.
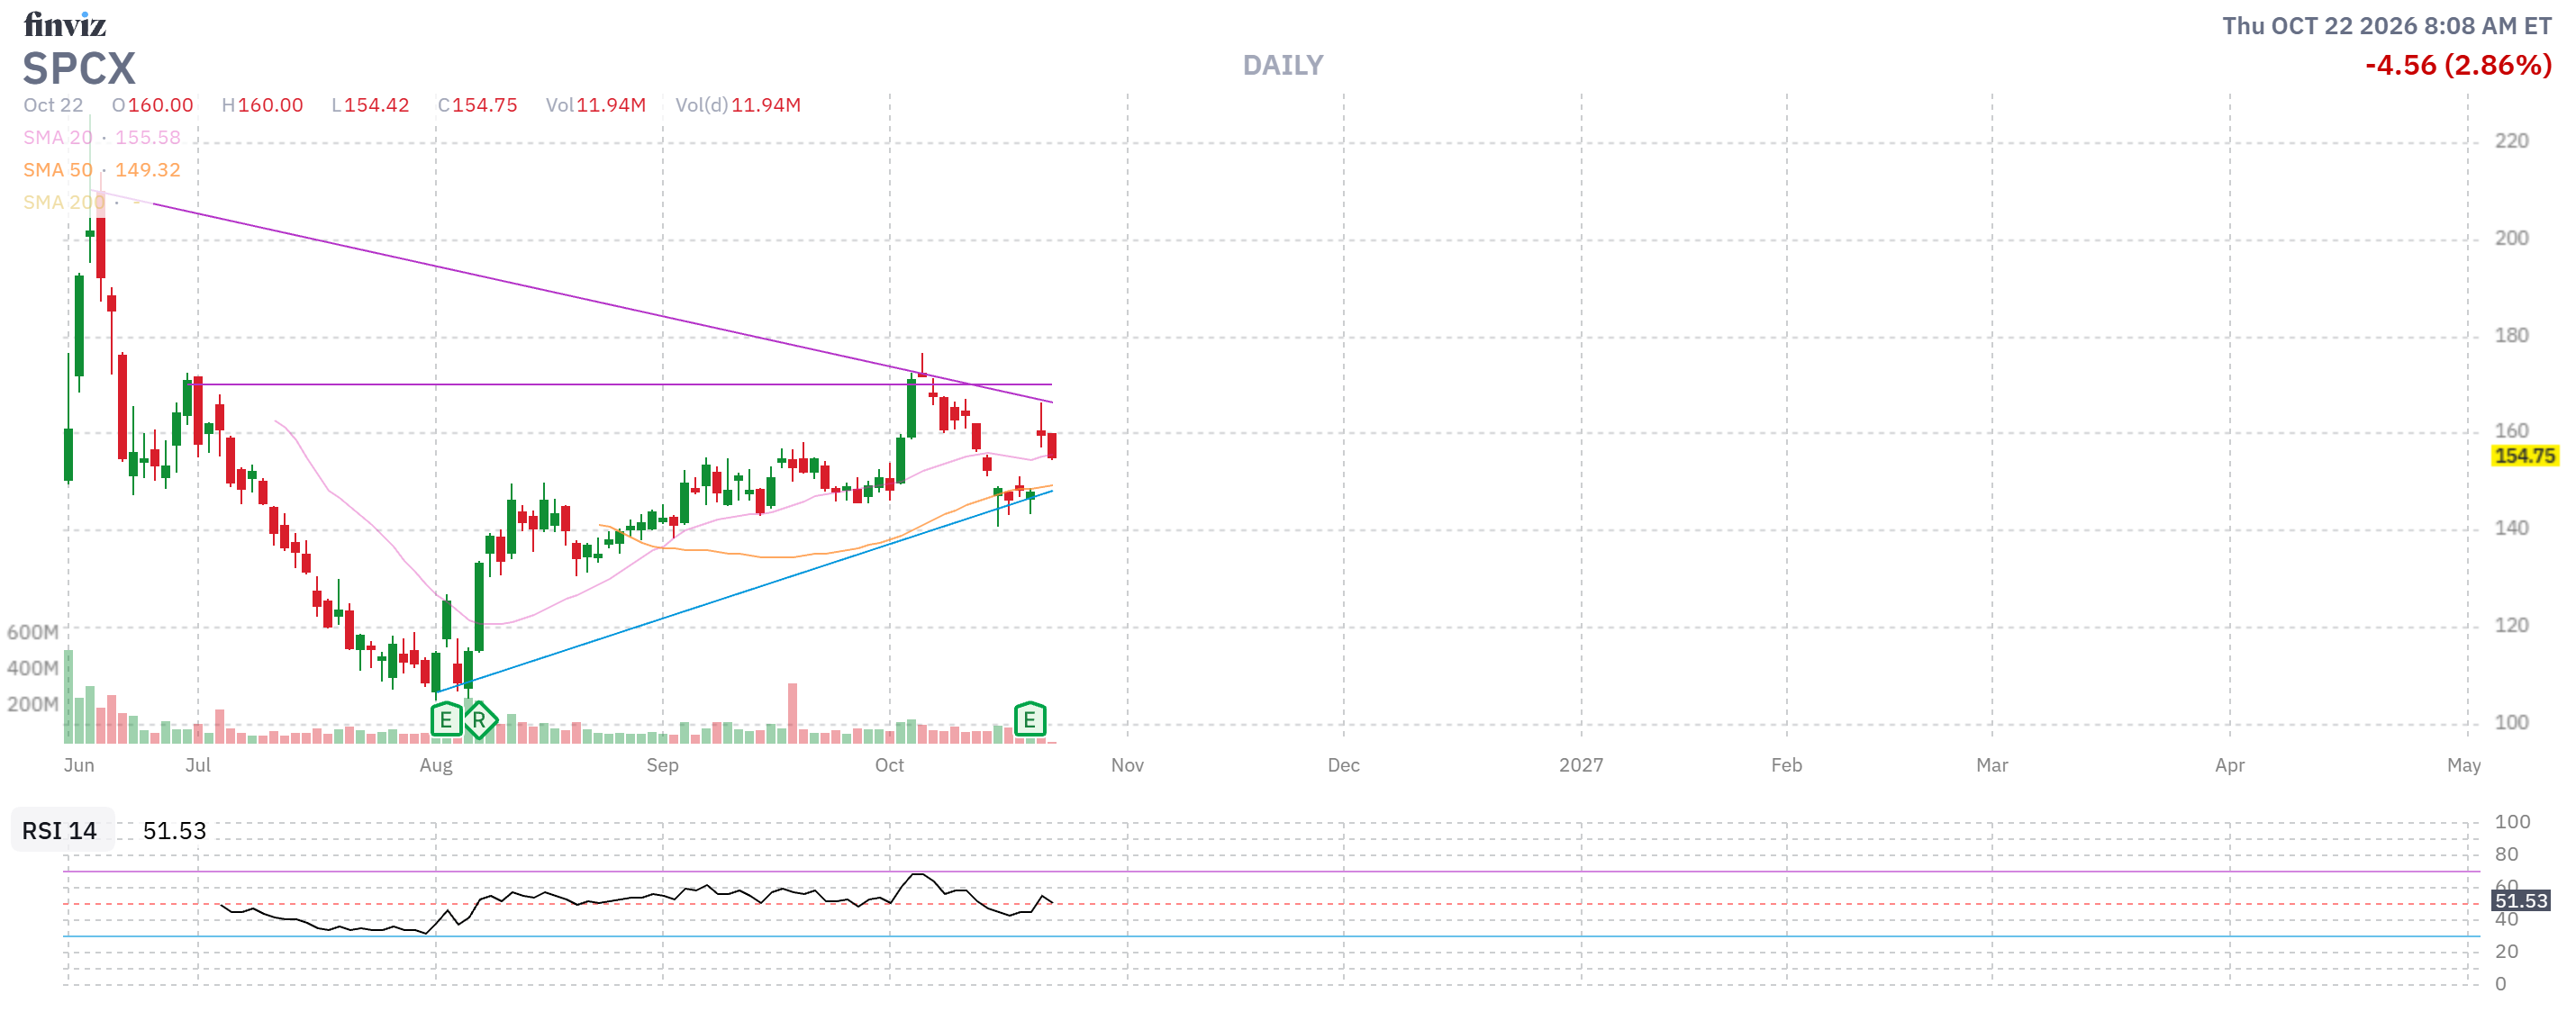
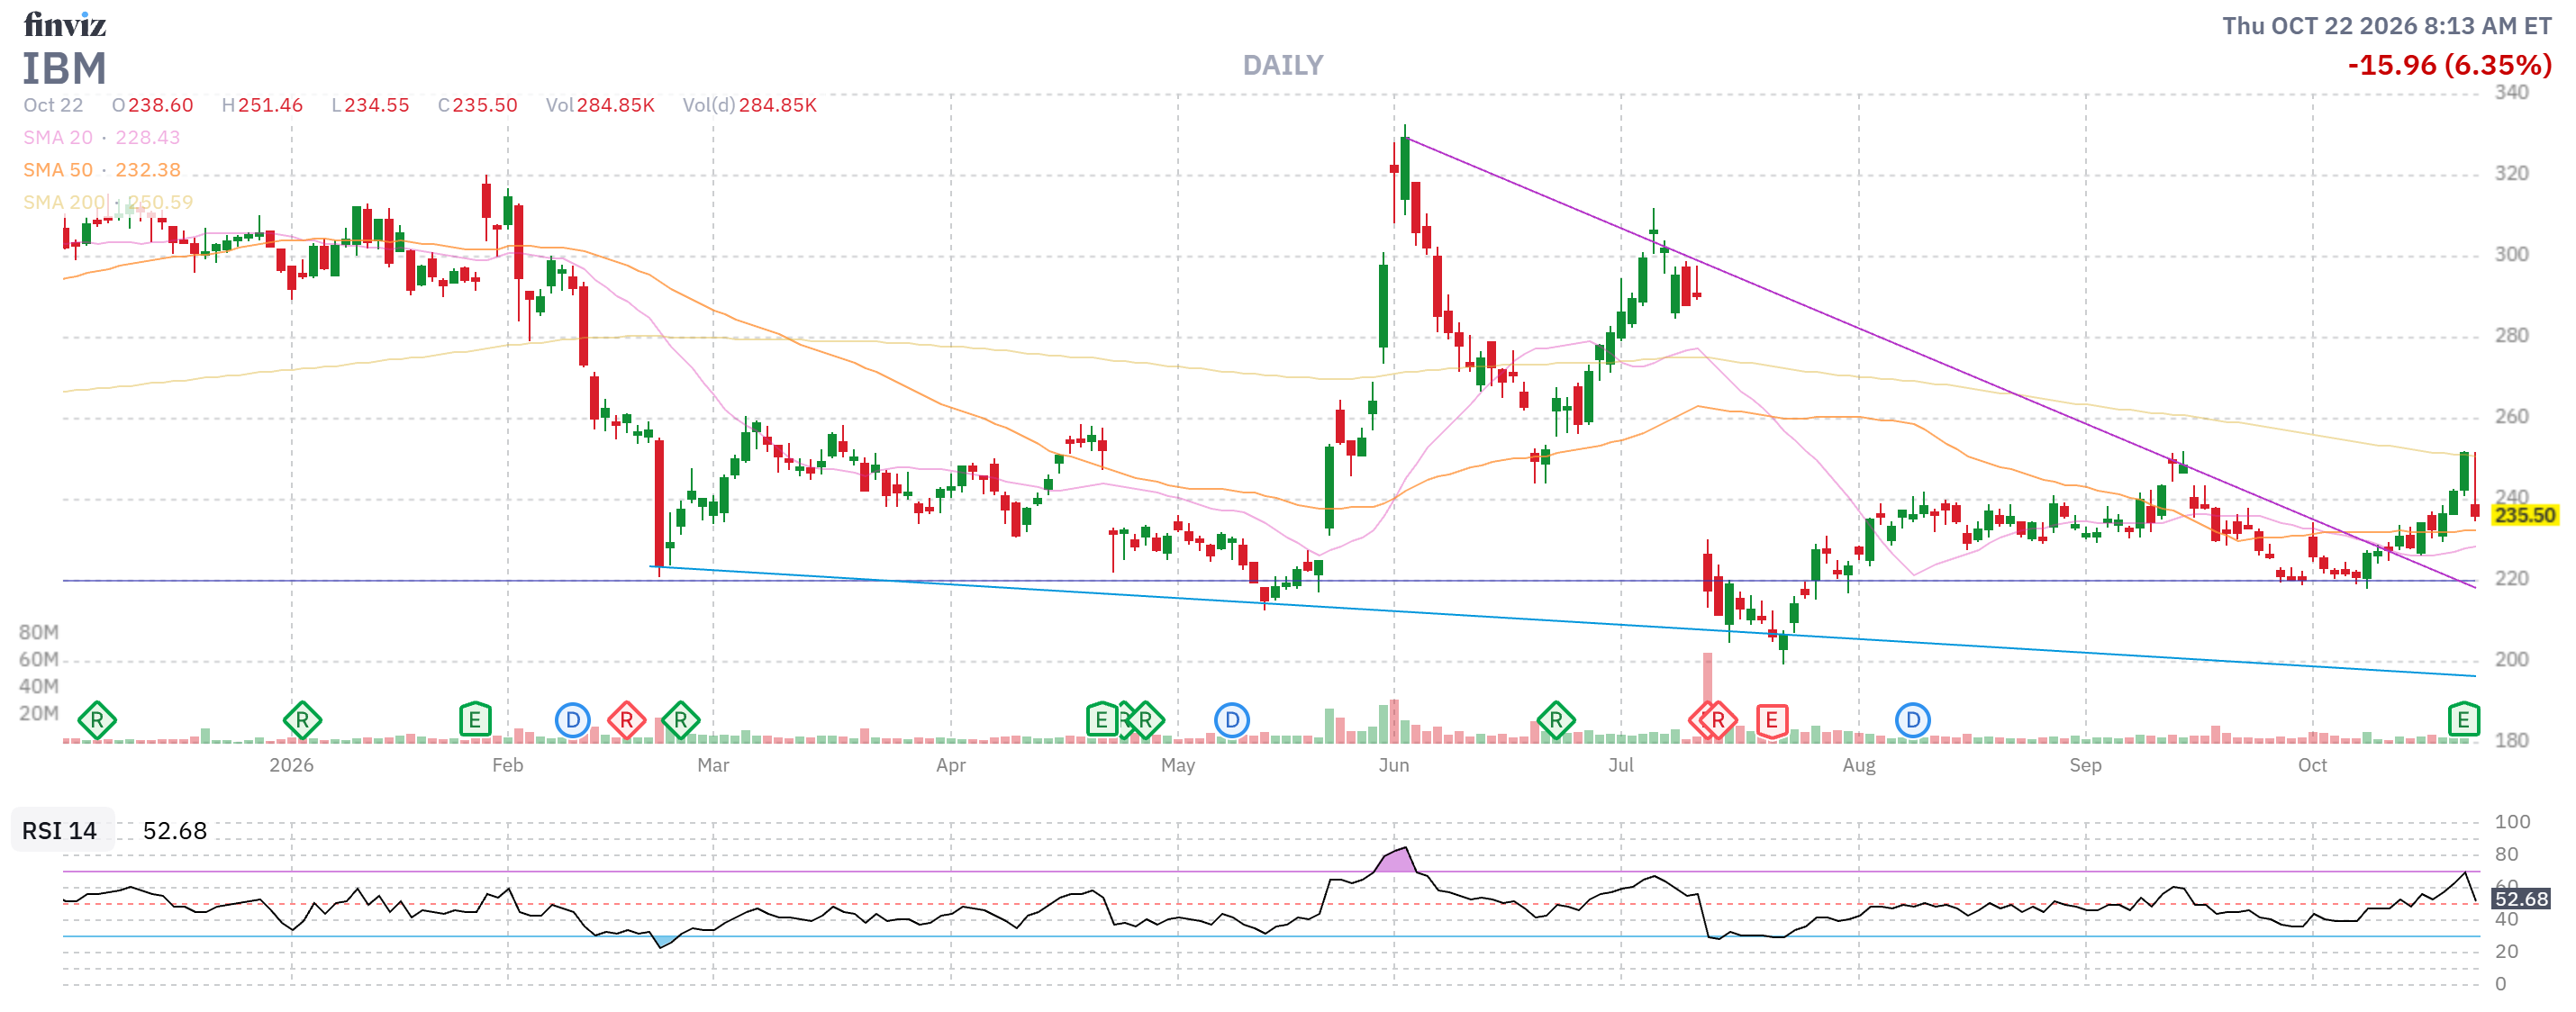
IBM, who we own in the LTP, beat and raised and still sold off 6% this morning – investors are getting fed up but I’d rather stick with IBM’s slow and steady pace of development than give my money for Musk and Zuckerberg to set on fire in a race to see whose AI can violate more people’s privacy.
SOXX and DRAM (ETFs) are down about 4% this morning, INTC is down 5% – even NVDA (clouds part, angels sing) is down 2.4% along with AMD, AVGO, MRVL, QCOM and (gasp!) MU after South Korea’s Kospi fell 4.2% along with Hang Seng down 3.2% and the Nikkei down 2.6% – good morning, indeed!
And, of course, the war rages on (I know, which war?) as oil is back at $99.45 in the US and $112 in Europe (Brent) as Houthis attacked Saudi Arabian oil fields, killing a couple of people and damaging infrastructure. The State Department ordered non-emergency staff out of Saudi Arabia and the NY Times says the US and Israel have drawn up plans to strike Iran again “AFTER the November 3rd mid-term elections” – because it worked so well last time, I guess…
Meanwhile, over in France (isn’t it funny how we’re a week ahead of these things?), the 10-Year Yield has hit 5% for the first time in 24 years while the UK’s 10-Year is at 5.37% and US rates have pulled back from 5.34 to 5.13 but the International tide is rising and we’ll have to see if the next round of debt auctions drown US (there’s a 5-Year TIPs auction at 1pm we should watch).
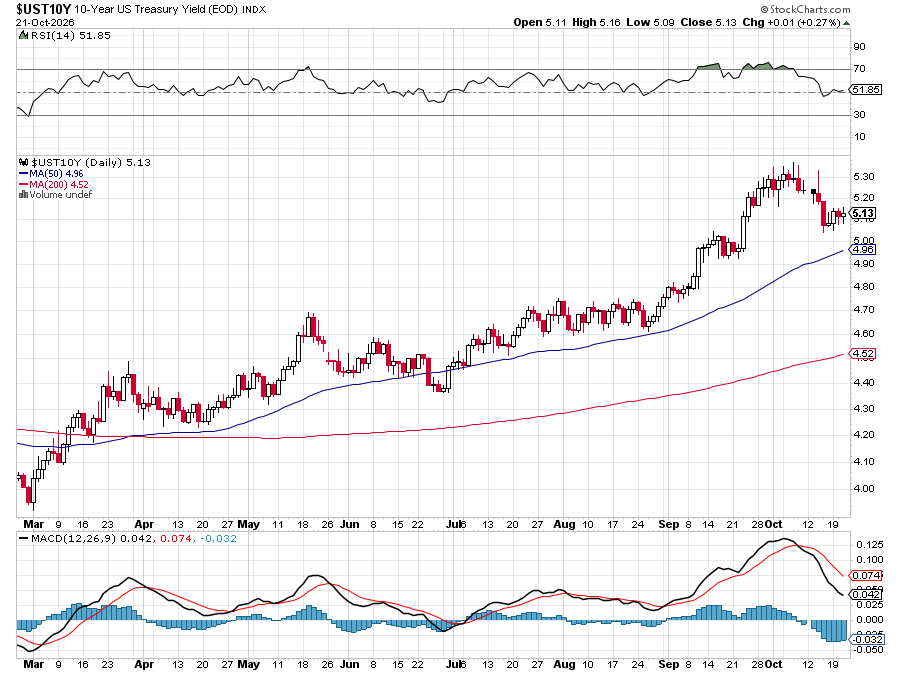
Yesterday’s $13Bn, 20-Year Bond Auction went off at 5.469% – UP from 5.42% las month and that is the highest yield since January of 1986, when the Government discontinued them for a period of time. Bidding was weak (soft foreign demand) enough that the Government settled for 0.9 basis points more than the opening offer in order to sell “just” $13Bn worth of paper. NOT GOOD!
Money, money, money is the theme of the day as META needs it to hook your children on AI “assistants” and the US Government needs it to fund $2.5Tn in annual deficit spending (that they admit to) and Consumers need it to fill up their tanks – literally taking $100 per barrel and lighting it on fire (internal combustion), leaving NOTHING to show for their “Transportation Investment” on the way to the voting booths.
How will this play out? We don’t know! That is why we are sticking to CASH!!! for now!