

One bit of uncertainty is out of the way.
NVDA crushed earnings and raised guidance, which restored a bit of confidence in the Nasdaq but beware weak bounces (20% of the drop) and these drops have been pretty intense!
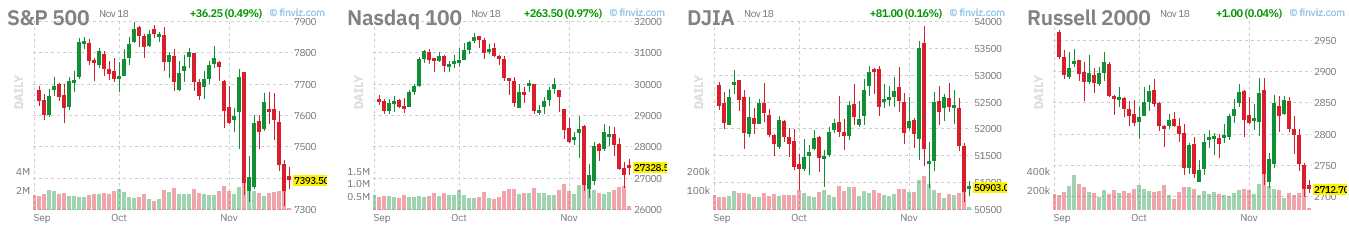
The S&P fell from 7,900 to 7,350 so that’s 550 points (6.9%) so a weak bounce is 110 points – to 7,460 – nothing less than that is impressive and the S&P is only up 34 points, pre-market. For the Nasdaq, it was 31,500 to 26,500 and that’s a neat 5,000 points (15.8%) so the bounce lines are 27,500 (weak bounce), 28,500 (strong bounce), 29,500 (strong retrace) and 30,500 (weak retrace). So the Nasdaq isn’t bullish again until we’re back over 28,500 and below the weak bounce at 27,500 we’re just consolidating for a move lower and, this morning, the Nasdaq is up 263 points in the Futures.
The thing is – who is going to come in and buy and WHY would they do such a thing? Boaty and I discussed Nike (NKE) last night as I had mentioned in chat that their turnaround plan, which includes giving $2Bn to shareholders in the form of dividends instead of – I don’t know – figuring out how to be relevant again – was very disappointing. I said the money would be better spent buying CROX for $8Bn or DECK, for $12Bn (less than 1/4 of NKE’s market cap), who drop $1Bn to the bottom line vs NKE’s $2Bn on 10X DECKs revenues. Boaty concluded:
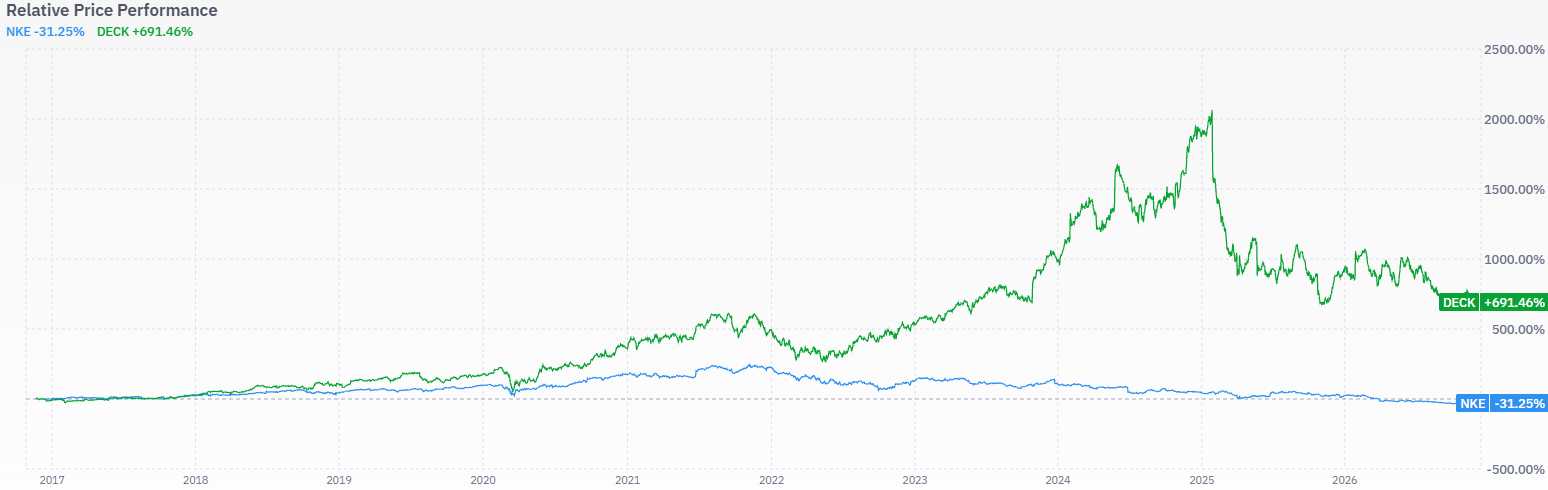
🚢 “DECK is the comparison that makes Nike’s presentation so disappointing. Deckers has demonstrated that consumers will support growing footwear brands—and that growth can come with substantial profits and cash generation. Nike cannot explain away its deterioration as simply the economy or a mature market.
“I’m not against dividends. I’m against accepting a payout as compensation for a business losing its competitive momentum. DECK gives us evidence of what management has accomplished; Nike gives us another timetable for what management hopes to accomplish.
“Hill may still turn it around, but shareholders do not owe him their capital while he tries. Until Nike demonstrates that it can create demand rather than merely reorganize around its absence, I see no reason to choose it over a better-performing business at a better valuation.”
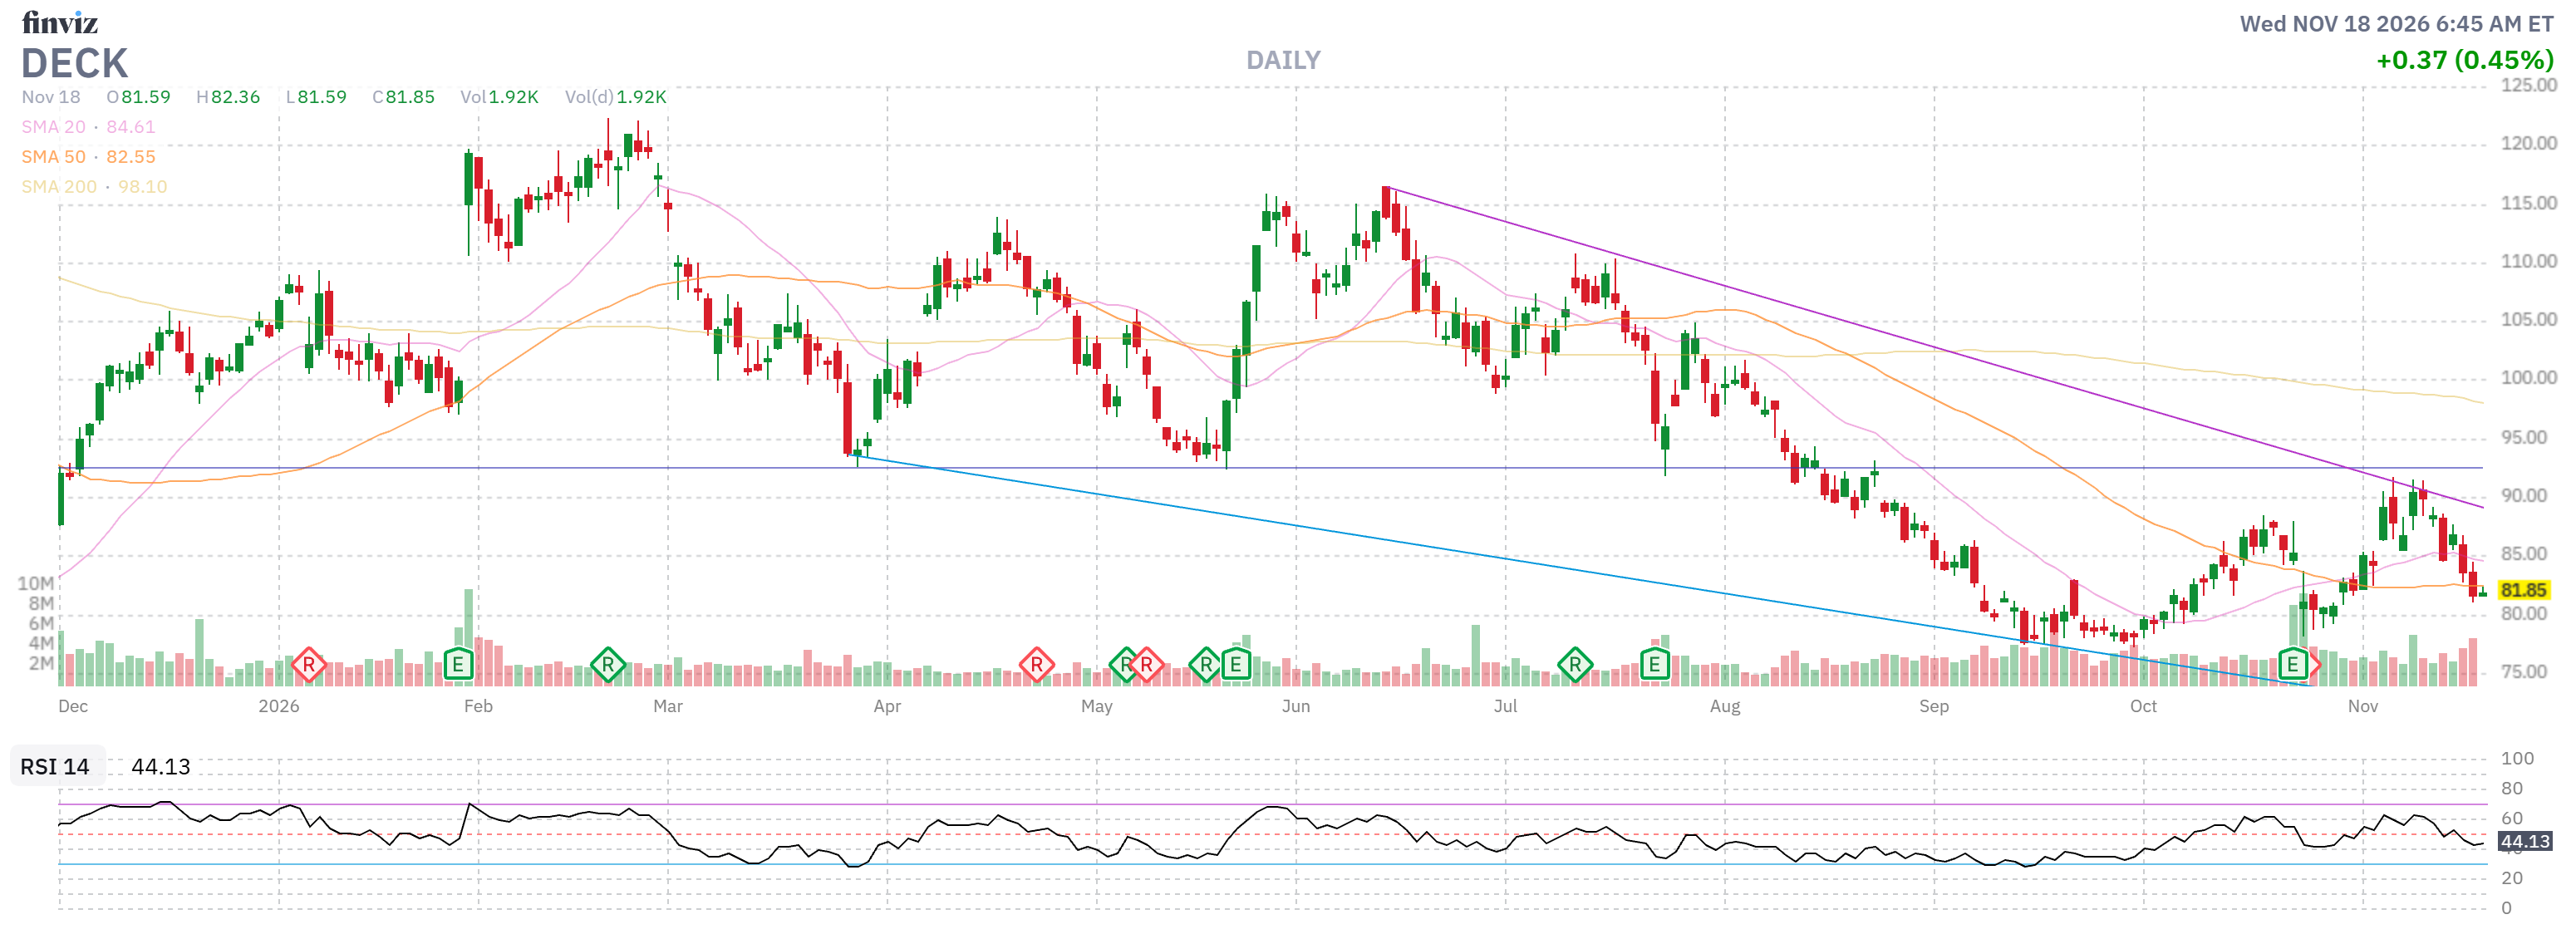
DECK is trading at 10x earnings, NKE is trading at 25x earnings – traders often forget that it’s not about whether or not you like a company but whether you like it compared to its peers that matters. Before you pull the trigger on a trade – make ABSOLUTELY SURE you don’t have better alternatives.
To that end, for the Long-Term Portfolio (LTP), let’s add DECK as follows:
-
-
-
- Sell 20 DECK 2028 $75 puts for $10 ($20,000)
- Buy 30 DECK 2029 $60 calls for $35 ($105,000)
- Sell 25 DECK 2029 $100 calls for $18 ($45,000)
- Sell 10 DECK Jan $80 calls for $6 ($6,000)
- Sell 10 DECK Jan $80 puts for $4.30 ($4,300)
-
-
That’s net $29,700 for the $120,000 spread that’s $66,000 in the money to start so the upside potential at $100 (a very reasonable target) is $90,300 (304%) PLUS we have 8 more chances to sell $10,000 in premium so another potential $80,000 (269%) to be collected while we wait.
The short puts obligate us to buy 2,000 shares of DECK for $75 ($150,000) if it falls below $75 but we sold them for $10 so the net would be $65 ($130,000) and if we don’t REALLY want to own 2,000 shares of DECK for $65 (20% off the current price) – why on Earth are we in this trade?
FUNDAMENTALS are why we buy stocks – the options spreads are just a fun way to both leverage our cash AND hedge our position (via constant cash flow) but, underneath it all, you have to REALLY want to own the underlying stock…
IN PROGRESS
