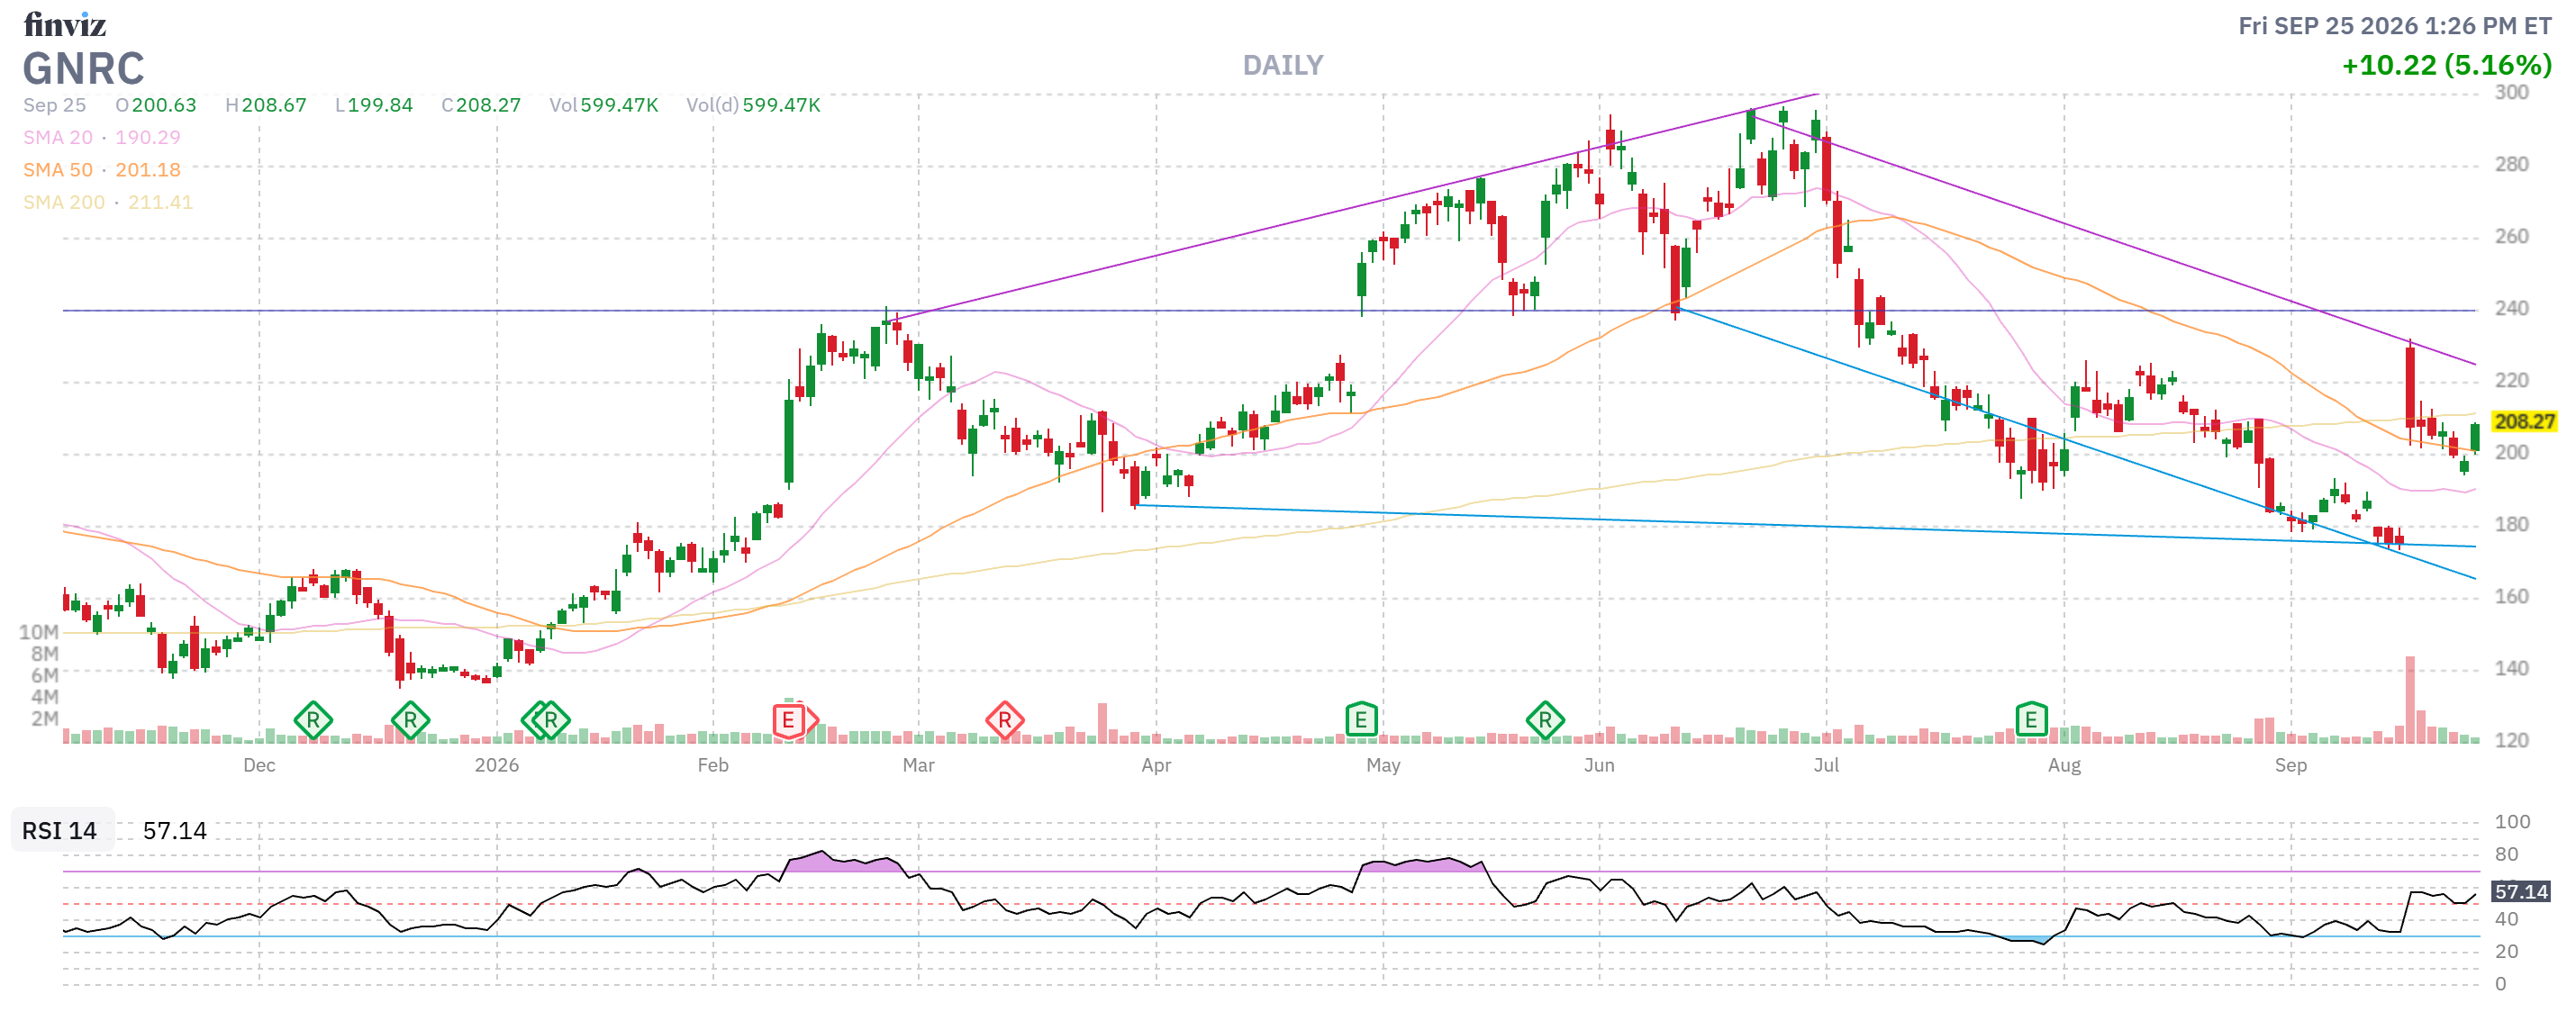
From the chat room on Sept 16th, Warren picked GNRC as his trade of the day. This afternoon we were reviewing our recent trade ideas and Gemini flagged his play:
"Wednesday, September 16
-
- Generac (GNRC) (Phil / AGI Team): Triggered a Top Trade Alert archive celebration after an after-hours pop. Liked as an essential, non-discretionary power grid and backup energy provider as data centers strain local utility grids."
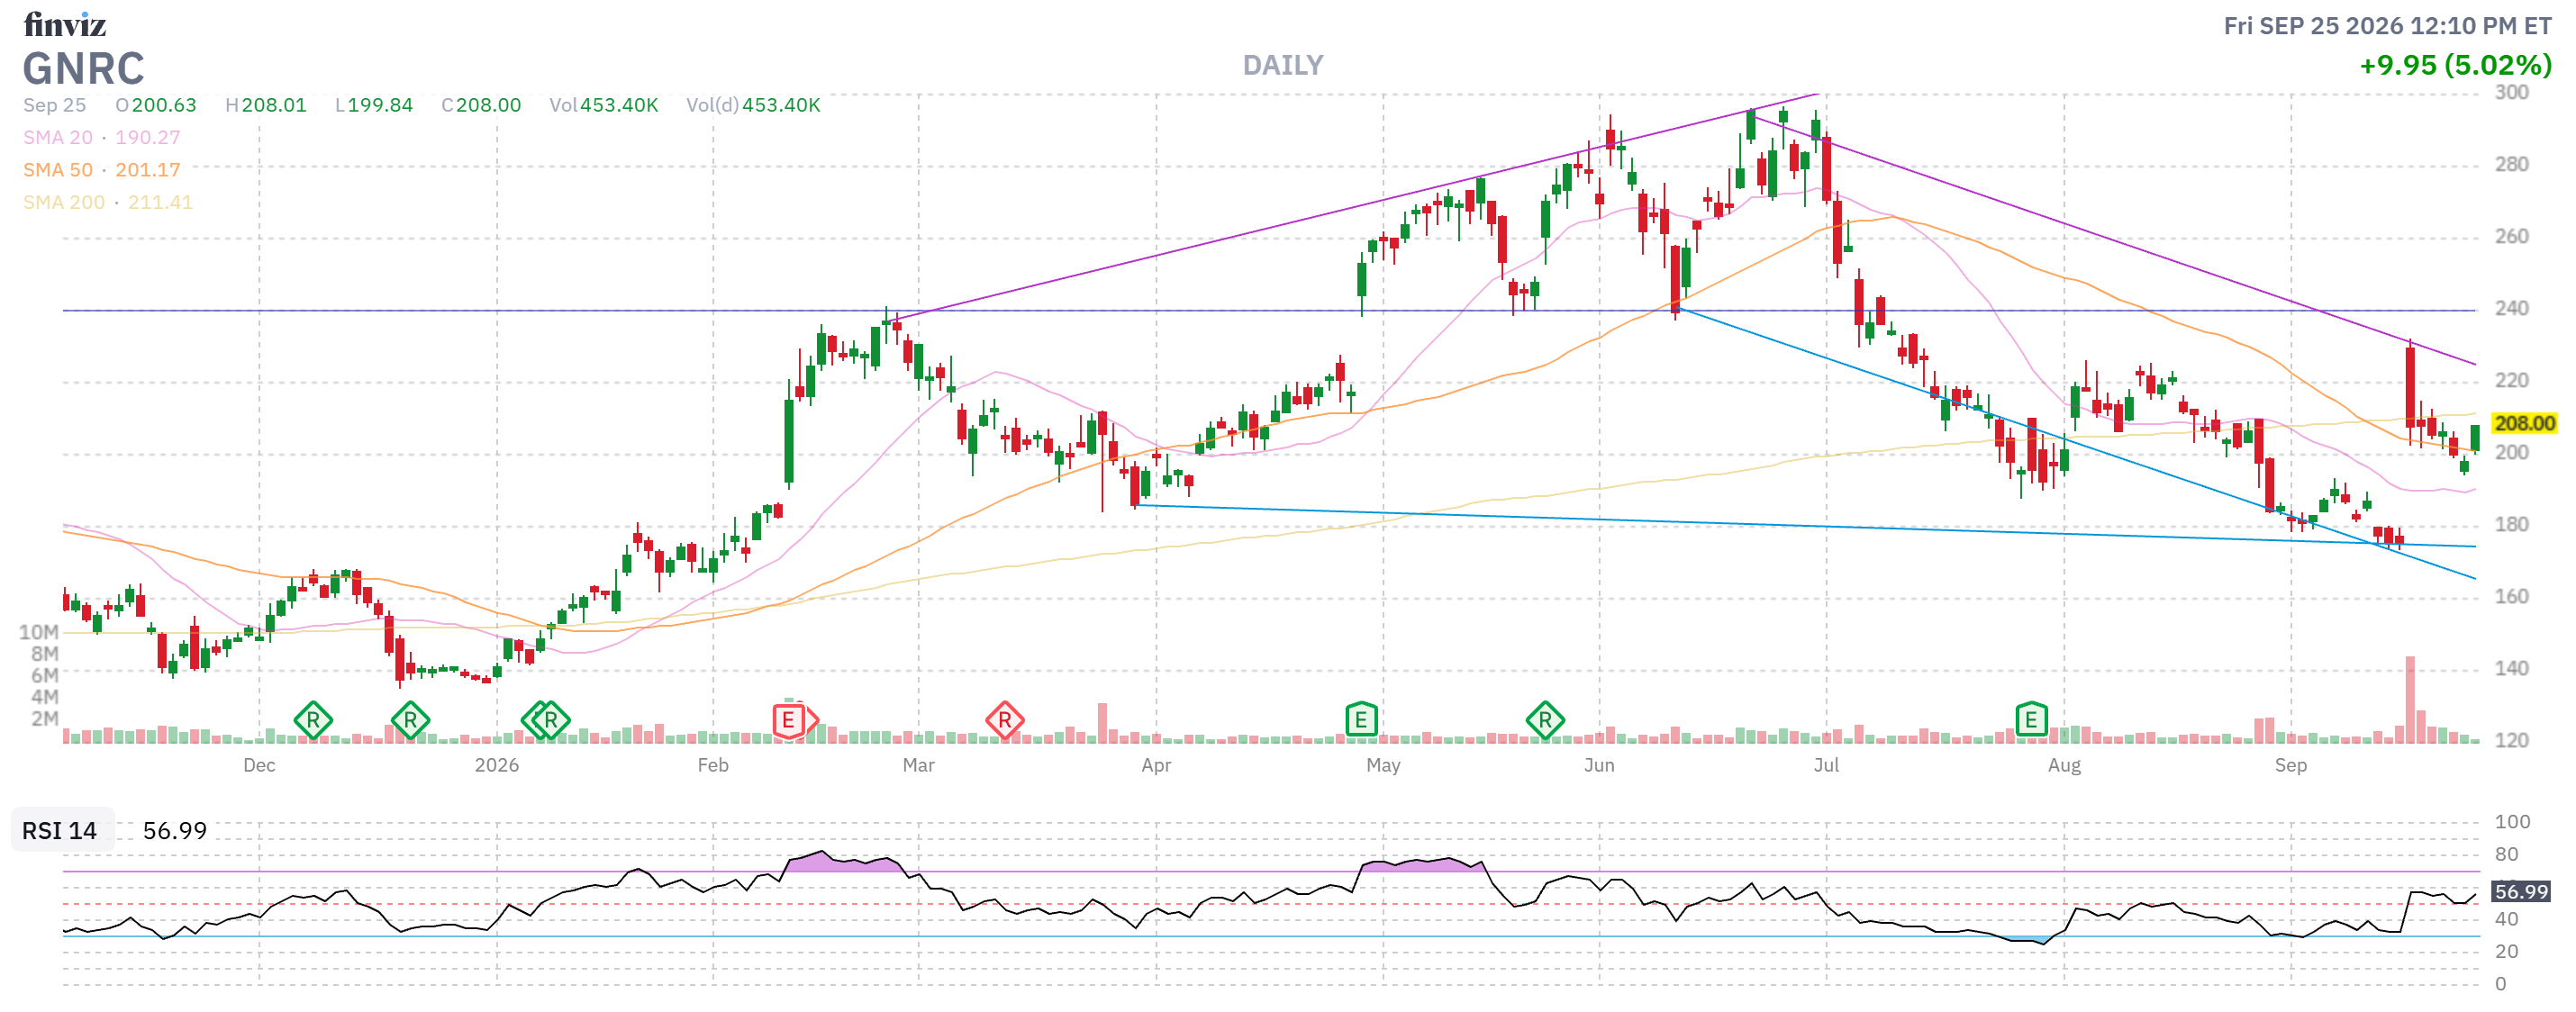
That led me to say:
No longer in the LTP! And I love these guys. Boaty, what say you?
🚢 I accept the pushback—and with an income-producing, hedged LTP structure rather than a naked long-stock bet, I think the case for getting involved now is much stronger. My concern was “don’t mistake an AI headline for permanent earnings”; the Amazon contract and existing backlog make this far more than a headline.
The actual risk is not demand. It is capacity, execution, and the price we pay for a company that may be capacity-constrained through 2027.
You are right on the demand shift
Generac is preparing to supply Amazon with about $2.4 billion of backup generators in 2027–2028 under a longer-term agreement that could reach about $8 billion over its life. On top of that, as of Q2 it had approximately $1.6 billion of data-center backlog, including about $1 billion of orders booked in the prior 90 days. The company’s 2027 data-center backlog before Amazon was already about $1.35 billion. [1727][1729][1731][1733]
That implies a plausible 2027 data-center revenue picture of roughly:
\$1.35\text{B existing 2027 backlog}
+
\$1.2\text{B Amazon, assuming half of the initial tranche}
\approx
\$2.55\text{B}
That is not a small bolt-on. It is more than twice the company’s roughly $1.17 billion of total Q2 revenue, concentrated in a segment that historically has been only part of the enterprise. [1711][1729]
And it does not include additional Amazon purchases beyond the first $2.4 billion, future non-Amazon hyperscaler orders, telecom/rental demand, or residential recovery.