📊 Angle 1: The Chronological Squeeze (The Bond Market vs. Tech Euphoria)
-
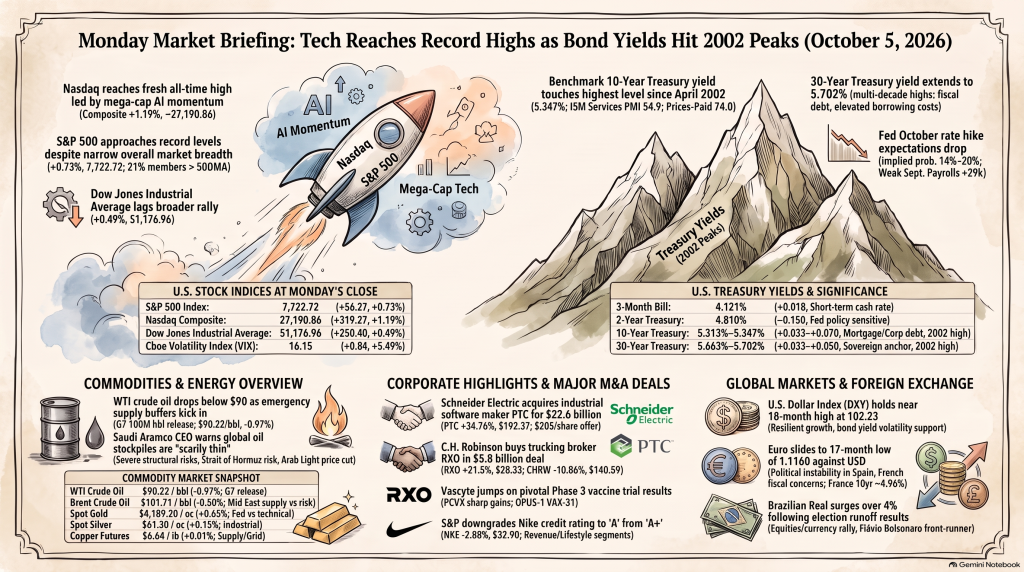
- The Angle: Dismantle the mainstream narrative that a weak economy will save growth stocks (0:15). Point out that Friday’s soft employment report (only 29k jobs added) (0:15) was completely neutralized (0:56) when Monday’s ISM Services Prices Paid component spiked to 74.0 (0:48)—lifting its 12-month average to the highest level since March 2023.
- The Narrative: The bond market isn’t reacting to temporary data; it is pricing in deeply entrenched structural inflation and a massive wall of sovereign debt borrowing (0:41). Mega-cap tech is pretending the risk-free rate doesn’t apply to them (2:18), creating a dangerous valuation disconnect (2:41).
- The PSW Action Item: Focus on acting as the casino (4:50). Instead of guessing which way volatile tech sectors will swing, sell premium to harvest the elevated option premiums (4:43) generated by everyone else’s market anxiety (4:50)—using a stable vehicle like PayPal (PYPL) (4:43).
🛢️ Angle 2: The Energy Illusion (Borrowed Stability in Crude)
-
- The Angle: Mainstream media is celebrating WTI Crude dropping 2% to settle around $89 a barrel (1:05), treating it as a relief valve (0:56). Expose the “math behind the curtain” (1:13).
- The Narrative: This price drop is a total illusion manufactured by the G7 agreeing to dump 100 million emergency barrels onto the market alongside Saudi Aramco cutting Asia prices (1:19). The market is excitedly pricing in immediate relief (1:27) while entirely ignoring the inevitable 4-month timeline constraint when those strategic reserves run completely dry (1:35). Meanwhile, physical supply chains and refined diesel remain structurally tight (1:43).
- The PSW Action Item: Look past the short-term macro panic to find unloved cash-flow machines (3:51). Highlight deep value plays like Molson Coors (TAP), which generates $800 million in normalized earnings against a tiny $6.9 billion market cap—offering an undeniable 11.6% earnings yield right in front of the market’s blind spot (3:59).
🏗️ Angle 3: The AI Hardware Wall (Caterpillar vs. The Cloud)
-
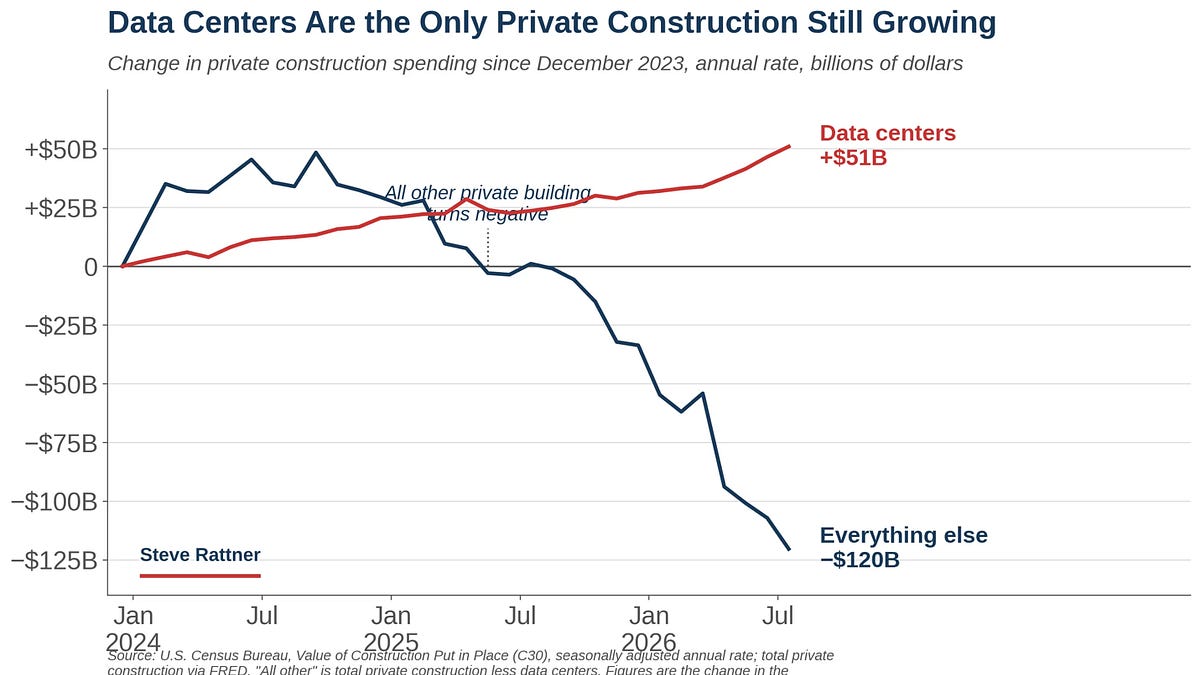
- The Angle: Shift the spotlight away from bloated software multiples and focus on raw, physical infrastructure (2:55). Dismiss the White House AI conferences as political theater (3:04) and introduce your readers to the crushing physical reality of the supply chain (3:35).
- The Narrative: Algorithms cannot bypass physical constraints (3:35). Caterpillar (CAT) currently sits on a massive $72 billion backlog (3:11), with buyers waiting up to 107 weeks for the heavy mining equipment required to extract the materials for AI infrastructure (3:20). Add in a 10-to-15-year timeline required to break China’s geographic monopoly on rare earth refining (3:28), and the “AI revolution” hits a massive industrial wall (3:11).
- The PSW Action Item: If you want to play the AI theme rationally, look at back-end, essential infrastructure rather than overhyped chips. Focus on a company like Wix (WIX) (4:25), which is positioned to build the algorithmic-friendly digital storefronts necessary for autonomous shopping agents (4:25).
 The S&P 500 closed Friday at 7,723 — a stone’s throw from the all-time high. If you only looked at the number, you’d think everything was marvelous. The problem is that underneath that number, the market is doing something it hasn’t done in 28 years, and almost nobody on CNBC is talking about it, which is usually the correct cue to pay attention.
Let’s start with the breadth data because it is genuinely wild:
-
- Only 25% of S&P 500 stocks are trading above their 50-day moving average. That is the lowest reading since April and it is down from 70% as recently as mid-August. In six weeks, roughly 225 of the 500 largest companies in America have broken below their 50-day trend.
- Only 47% of S&P 500 stocks are above their 200-day moving average. Also the lowest since April. More than half the index has broken its long-term trend while the index itself hovers near highs.
- New 52-week lows on the NYSE have outnumbered new highs for 10 consecutive sessions and in 14 of the last 15.
- The McClellan Summation Index is at -636 with its 5-day RSI at 2.71. This level has only been reached TWICE in its ~28-year history. The last time was July 18, 2002 — three months before the final low of that bear market.
That is not noise. That is a 500-stock index being levitated by 15-20 names (hello again, Roy and Penny’s number) while the other 480 quietly take the elevator down. It is the exact pattern that preceded Q4 2007 and Q1 2000. Not the SIZE of those moves, necessarily — just the pattern. When the generals stay propped up and the troops get taken out behind the barn, somebody is lying to somebody and, in the market, the price is usually the one lying.
Here’s what makes this time rhyme with history in a particular way: the generals are not just the Mag 7 anymore — they are the AI capex cohort. Nvidia, Meta, Microsoft, Google, plus the Oracle/Palantir/Broadcom circle that benefits from the hyperscaler buildout. These names are up 40-70% year-to-date. The equal-weight S&P (RSP) is up 4%. The cap-weighted index is up 15%. That gap — 11 percentage points of outperformance by cap-weighting over equal-weighting — is the entire bull market. Strip out the AI cohort and we have had a flat-to-down year.
https://elite.finviz.com/published_idea?t=MAGS&f=100626&i=MAGSd075661979i&th=l
Which brings me to today’s actual event, which Phil flagged on Friday but which deserves a reminder: the Treasury auctions $58 billion of 3-year notes at 1 PM. Then Wednesday is $39B of 10-years. Thursday is $22B of 30-years. $119 billion of US debt to place this week, into a bond market where the 10-year topped at 5.3% last week before pulling back to 4.95% — a Fibonacci retrace Phil already walked you through. The question is whether the pullback holds or whether the auctions push yields back toward the highs. If the 30-year prints above 5.5% on Thursday, every long-duration thing in your portfolio reprices and the AI-generals start to feel the gravity of discount rates that nobody has been pricing into their 2027 cash flows.
Meanwhile, over in the Middle East — because of course we have a Middle East crisis every week now — the Houthis launched ballistic missiles and drones at Saudi Aramco sites in Riyadh and Khurais on Sunday night. Brent jumped 0.8% to $103. WTI jumped 0.5% to $91.57. Both have since given most of it back. Oil is at $89.86 this morning, down 3.4% over the past month despite the attack, because Kuwait is pumping at 75% of pre-Iran-War levels, Saudi Arabia just slashed its flagship Asian export price and the G7 is draining emergency stockpiles. The attack is real. The market impact is being absorbed because the supply picture is loosening even as the geopolitical picture tightens. The headline reads “oil facility attacked.” The denominator reads “oil down 3.4% on the month.” Headlines without denominators are noise!
Which is the whole PSW thesis in miniature: look at the data, not the headlines. The headlines say stocks are at record highs. The data says 75% of stocks are below their 50-day average. The headlines say oil is spiking on Houthi attacks. The data says oil is down on the month despite the attacks. The headlines say the Fed is hawkish. The data says John Williams of the NY Fed pivoted dovish last Monday and the market has already pulled hike odds from 74% to 49% in a single week. None of these headlines are LIES. They are just missing the information you need to actually make a decision.
Fed Watch
One quick note on the Fed because it ties into the breadth story. 19 Fed speeches were scheduled last week. By Thursday morning the market had decoded the message: Williams went dovish Sept 29, the regional presidents followed with “balanced,” “patient,” “data-dependent,” and the implied October path shifted from “another hike” to “likely hold with December cut.”
Friday’s 29K jobs print sealed it. Lorie Logan speaks today at 10 AM Eastern — she is the hawkish holdout among regional presidents, so if even LOGAN tilts dovish, the pivot is confirmed in writing. Watch the 10-year reaction between 10:00 and 10:30 this morning. If yields drop 5-10bp on Logan’s language, the pivot is in. If yields hold or rise, Logan is defending the hawkish flank and the October meeting is genuinely in play.
The Trade
Our stance remains 70% cash. I know, I know — it’s been 70% cash for months while the index has grinded higher. Here is the thing: the index is grinding higher on 20 names. The other 480 are already in correction and, when the 20 reprice (and they will, because 30x forward earnings doesn’t survive discount-rate normalization indefinitely), the 70% cash becomes the specific gift that allows you to buy quality on sale while everyone else is explaining to their spouse why the 401(k) got cut in half. Being wrong early is not being wrong. Being right at the top with no dry powder is being wrong.
What we ARE deploying the 30% into:
-
- Defense/Picks-and-Shovels (unchanged): CEG, NEE, ETN, VRT for grid; LMT, RTX, KTOS, AVAV, GD for traditional defense; MU and SNDK for memory; CCJ, LEU, BWXT for nuclear. These win regardless of which AI narrative holds.
- Gold and metals (unchanged): $4,700+ on gold, silver at $69, copper at $6.59. GDX, SLV, FCX, COPX. The dollar-debasement thesis does not care about market breadth.
- Duration (adding on strength): TLT, ZROZ, EDV. The dovish Fed pivot is now the modal outcome. Long bonds appreciate as rates fall. The three auctions this week could create entry points — if yields spike on weak auction demand, that’s your buying opportunity, not your reason to panic.
- Northern Oil & Gas (NOG) — the specific pick worth repeating: domestic shale non-operator with no refining exposure, 20% dividend yield at current oil prices, structural hedge against Hormuz disruption without needing oil to spike to $120. If oil holds $85+, this is a 15-20% total return story over 12 months with downside protected by the dividend.
- TAP (Molson Coors) for the “no supply chain exposure” bucket: 3.8% dividend, trading at 9x forward earnings, zero tariff exposure, consumer staples pricing power. Americans drink more beer when they’re worried about their jobs, which per Friday’s NFP is roughly all of them.
What I’m NOT Doing
Not chasing the AI cohort. Not shorting the AI cohort either — Musk has demonstrated for the last decade that narrative-driven stocks can crush shorts for years before the math arrives. Hedge, don’t short. Define your risk. Use spreads. Buy puts as insurance, not as directional bets.
Not panicking about the Middle East. Oil at $90 is manageable. Oil at $120 would not be. We are not there and the supply loosening suggests we are not getting there this quarter. If I’m wrong, NOG and the dividend protect the downside.
Not buying the dip on breadth. When 75% of stocks are below their 50DMA and the Summation Index is at -636, the dip has not finished dipping. The 2002 analog bottomed three months after the comparable breadth reading, not three days.
The Setup for the Week
-
- Tuesday (today): $58B 3-year note auction at 1 PM. Logan speaks at 10 AM. Watch the yield reaction.
- Wednesday: $39B 10-year auction. FOMC minutes released at 2 PM — the market will parse these for confirmation of the dovish pivot the regional presidents have been telegraphing.
- Thursday: $22B 30-year auction. The one that matters. If this fails (bid-to-cover under 2.3x), the long end spikes and the market reprices duration risk hard.
- Friday: September CPI. The specific print that either validates or kills the dovish pivot.
Position accordingly. Which means — practically — do not add equity exposure before Thursday’s auction. Do not sell gold on any pullback. Add duration on any auction-induced yield spike. Keep the 70% cash dry. Wait for the capitulation moment the breadth data is telegraphing, which will arrive sometime in the next 2-6 weeks, probably on a day when the market gaps down 3% on an exogenous catalyst that everyone will pretend was unpredictable.
It is predictable. It’s in the breadth data. It’s in the auctions. It’s in Logan’s speech at 10. It’s in the gap between what the index says and what 480 of its 500 components are actually doing.
The 25% breadth number genuinely startled me when I pulled it this morning. That is a bear-market reading dressed in bull-market clothing. The last time the Summation Index hit this level, the S&P fell another 15% over three months before bottoming. The time before that, 2008. The time before THAT, 2000. The market does not know it is in a correction yet because the index is being carried by 20 stocks whose shareholders are specifically the top 1% Phil’s loop piece described yesterday. The wealth effect for the top 1% is intact. The actual market for the other 99% of investors already turned over six weeks ago, which — not coincidentally — is roughly when the mega-cap AI cohort went vertical on the Super Intelligence rebrand.
The loop is running exactly as advertised. The oligarchs’ wealth is being preserved by narrative-pumped mega-caps. The broader equity base is quietly deteriorating. The Fed is pivoting dovish to fund the next leg of the asset-price support operation. The Houthis are keeping oil elevated enough to feed inflation but not enough to break anything yet. Position accordingly. Patience compounds. Panic does not.
Have a great Tuesday, members. Watch Logan at 10. Watch the 3-year auction at 1. The train continues. 😱
RJO ghosting for Phil, filed Tuesday morning October 6, 2026, standing by for Logan’s speech and the auction results.