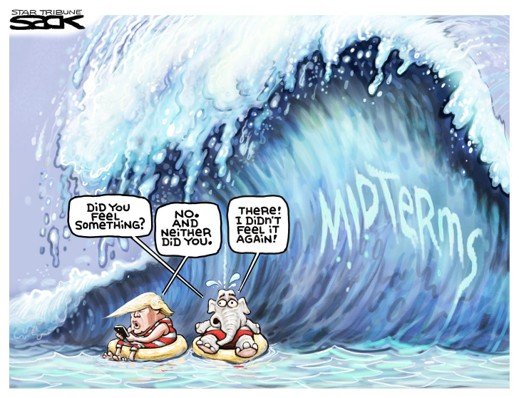
Yes, it’s finally time to vote!
Whether or not that voting will change anything remains to be seen – we almost certainly won’t even have all the results in for weeks as challenges are expected to anything that’s contestable and, in Alaska, the GOP isn’t even waiting – they are pre-challenging the election up there…
Just in time for you to drive to the polls, Oil is down to $99.47 and Gasoline is down to $2.98 (wholesale) – both pushed down hard this weekend – as if American’s on the way to the polls will say “Gas is back under $4/gallon? Let’s re-elect these guys!”
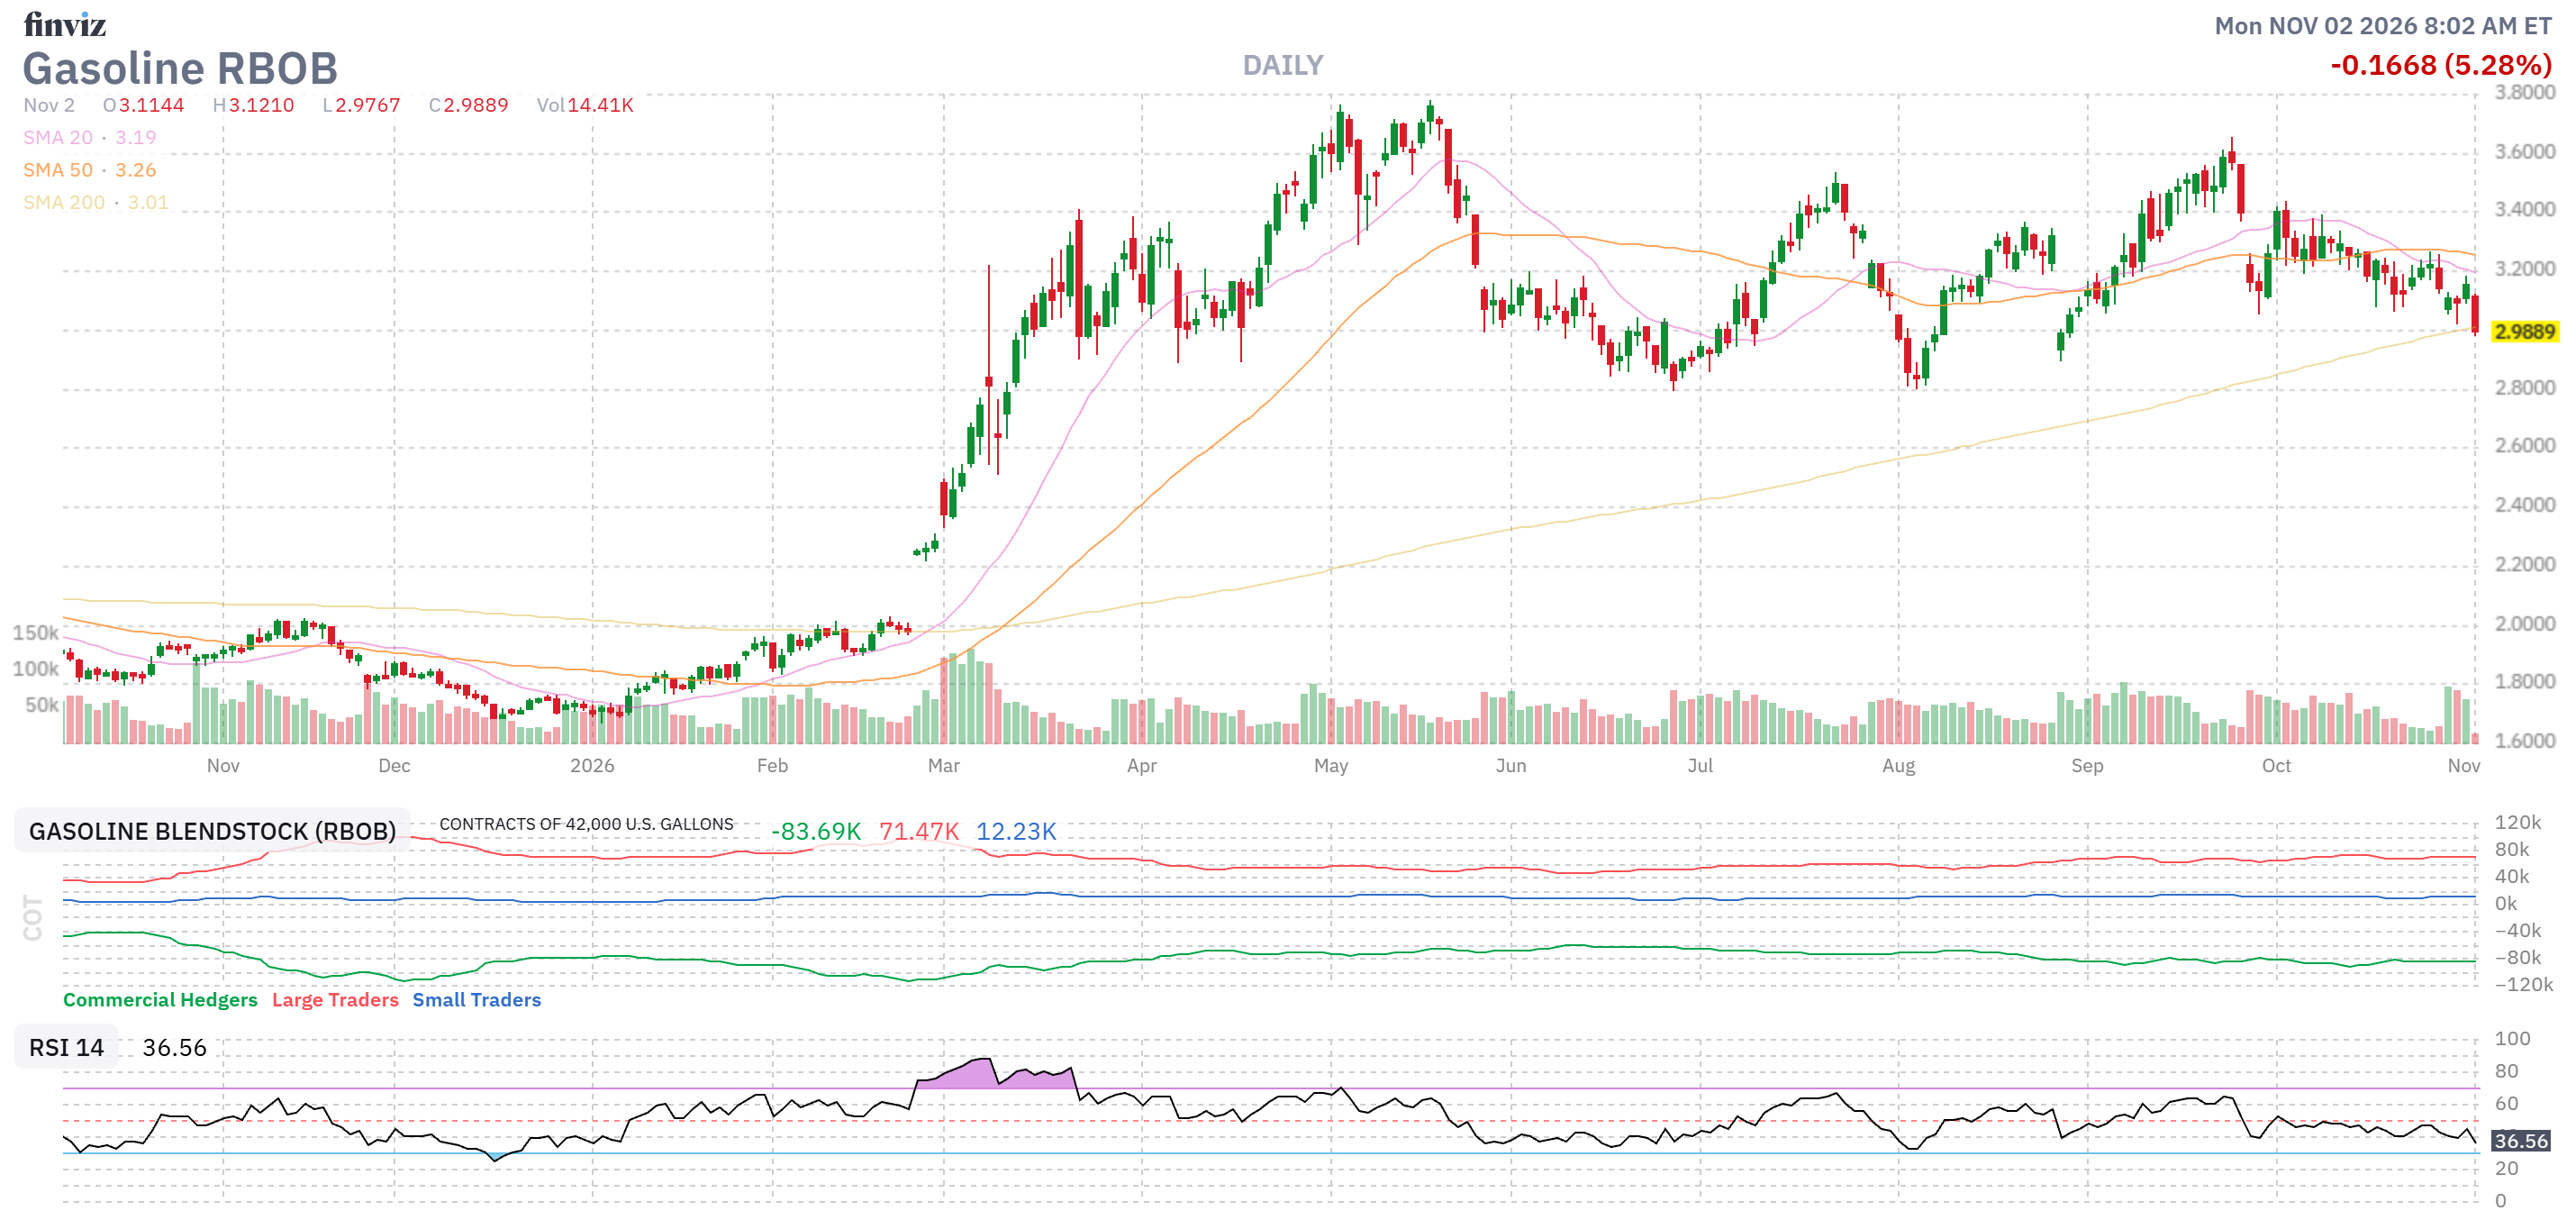
UNFORTUNATELY, $2.99 is still 50% more than under $2 was last November, or the November before that – or any November since 2014 and, of course, we’re supposed to believe this is somehow Joe Biden’s fault and, after hearing it over 1,000 times – maybe it is?

 I would say Goebbels looks like a young Stephen Miller but Stephen Miller is only 41 and he seems to have always looked this old…
What matters in this election is whether or not Americans are accepting the status quo and, if so, we have at least 2 more years of Project 2025 policies and maybe even a 3rd Trump term in 2028 and, if not, then Trump has already threatened to veto any law the Democrats dare to pass – which means two years of gridlock and, actually, the markets like that!
The markets did NOT like the events of last week as the Nasdaq fell from 30,000 to 28,500, which is a 1,500-point drop and exactly a 5% pullback with a spike down to what we HOPE will be solid support at 28,000, which is both the Strong Retrace AND the 200-day moving average. If that does not hold – then a 10% correction to 27,000 (Strong Bounce line) is a near certainty.
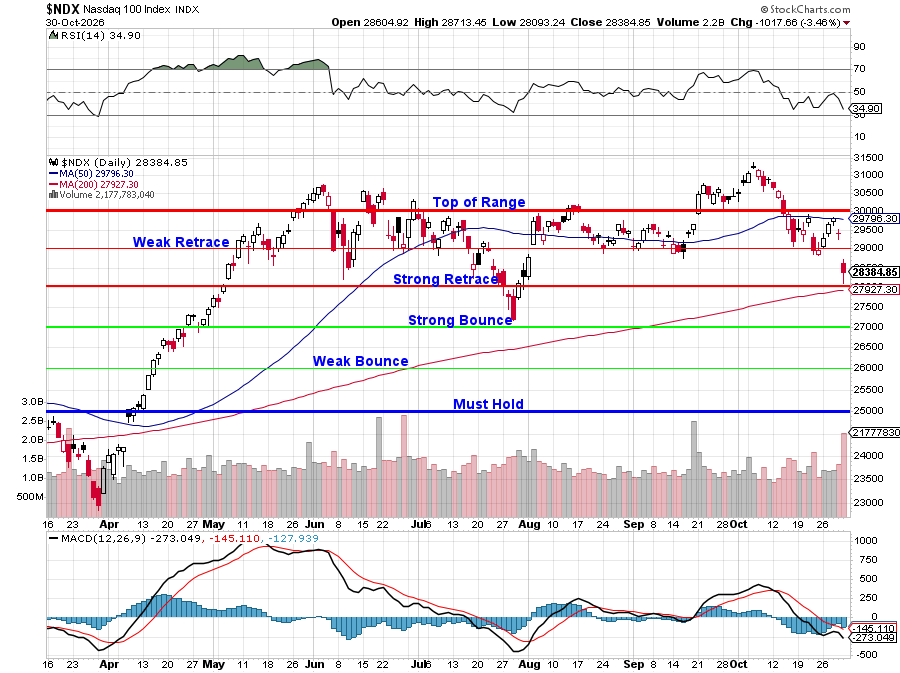
Good news for the bulls though – the RSL is way down at 34.90 and 30 – which WOULD be 28,000 – is crazy-low for RSI so again – this SHOULD be bouncy but bouncy doesn’t mean recovering – it just means bouncing and that is why we have our Bounce Chart – in this case using short-term (from mid October) 5% corrections:
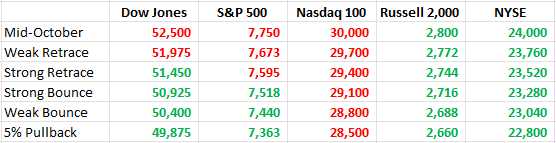
Not what you thought it would be, right? What we’re seeing here is a sharp sell-off in the tech-heavy Nasdaq 100 which is, of course, dragging down the S&P 500 as well as a dozen Nasdaq HYPERscalers are responsible for 70% of the S&Ps total earnings BUT, in the much-broader Russell 2,000 and NYSE (2,400 stocks that are NOT in the Nasdaq 100 or the Composite) – we’re actually HIGHER than we were two weeks ago!
So what we have here, so far, is ROTATION, not correction! Funds do not want to be holding the hot potato when the music stops and the music is clearly getting close to the end of the song now. We cleared out of our positions (mostly) in our October 13th Portfolio Review and we’ve been rotating into Russell and NYSE positions all summer long – putting us well ahead of this rotation cycle. You’re welcome!
It is Monday, so nothing counts and then tomorrow nothing will count until the votes are counted and, even then – it may not be clear so it’s going to be a week of turmoil and then we go back to focusing on the War that Trump may or may not re-escalate but, this morning, the narrative they are selling is PEACE – peace and lower gas prices on the way to the polls…
There are “only” 6 short-term Note Auctions this week but, times being what they are, they still add up to $577 BILLION in debt this week and that will be interspersed with 7 Fed speeches along with PMI & ISM this morning, JOLTs tomorrow, PMI & ISM Services on Wednesday, Job Cuts & Productivity Thursday and Friday it’s Non-Farm Payroll and Consumer Sentiment:
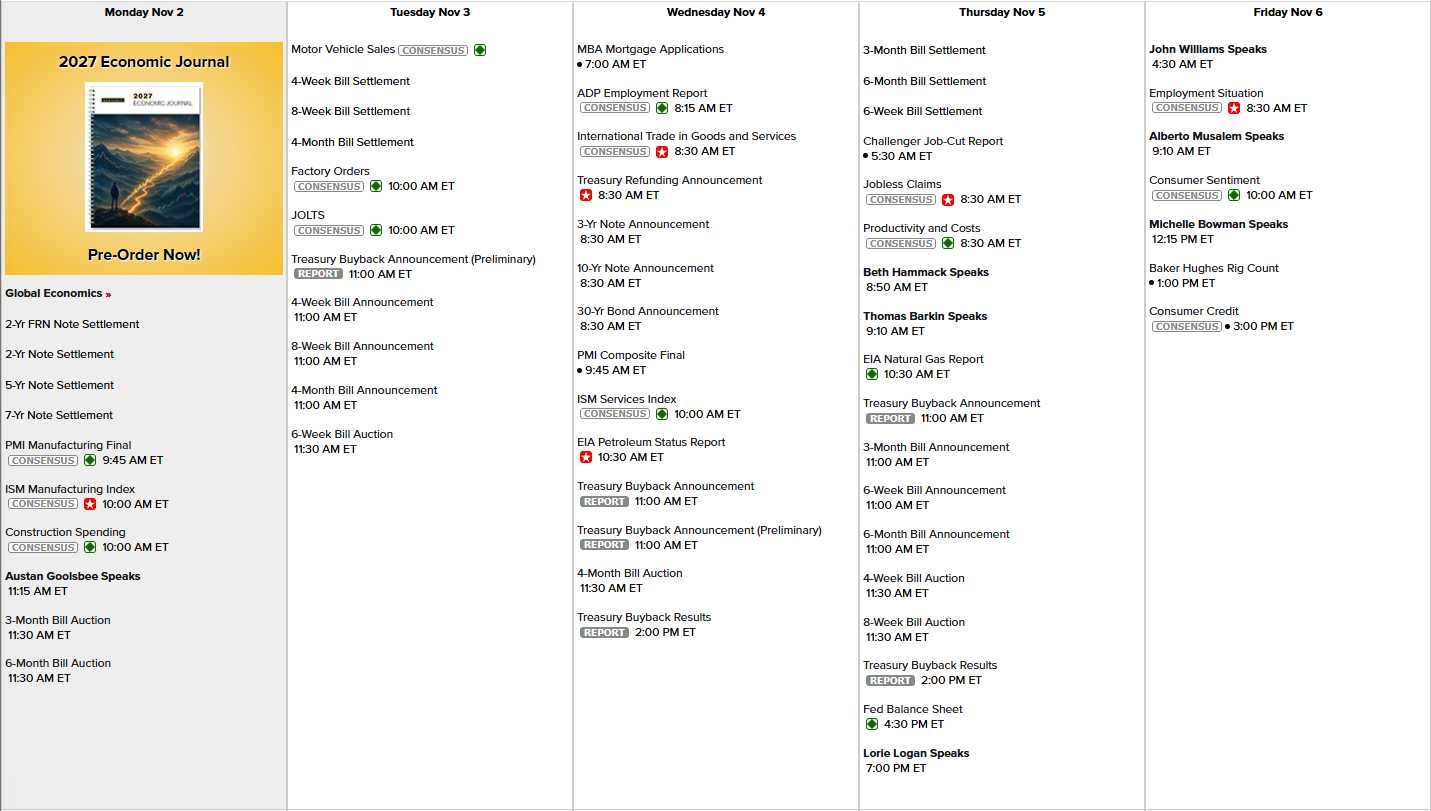
Meanwhile, earnings reports are still flying in with AAPL taking a turn this evening but PLENTY of other reports that will get our attention so a lot of examination this week and, HOPEFULLY, by the time we do the November Portfolio Reviews in two weeks – most of this nonsense will be settled and it will be time to go shopping:

The BIG news we’re following this morning is Open AI cutting it’s funding target by $10Bn (one third!) AND cutting their planned valuation by $150Bn (10%!) when what was SUPPOSED to be an ordinary fundraising round meant to close on Friday FAILED to get enough institutional interest to fill!
At the moment, they have raised just $11Bn at $1.25Tn in valuation after asking for $30Bn at $1.5Tn – a huge disappointment and indicating a potential DISASTER for Anthropic’s upcoming IPO, where they are looking to raise $100Bn at a $2Tn valuation to cover just a portion of this year’s burn rate.
Be very careful out there!