Yes, I’m happy.
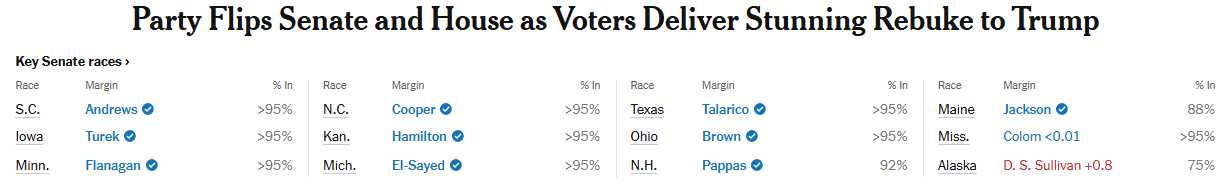
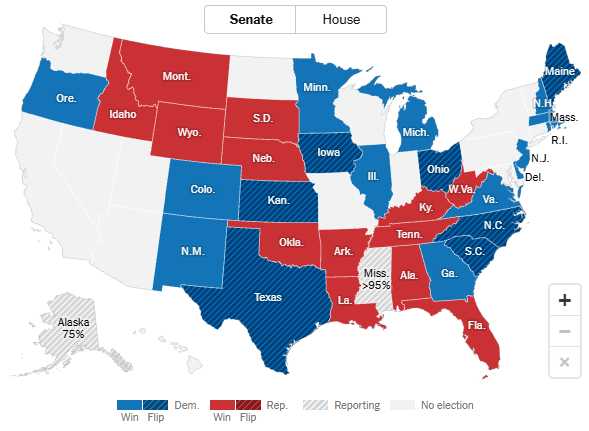
The Democrats flipped seven Senate seats, including 3 that have been held by Republicans for DECADES and, although many races are still up in the air, the Democrats already control the House with 228 decisions (218 is control) vs only 139 Republicans re-seated so far. Hunter covered the election all last night – so we don’t need to rehash it here – we just need to deal with the aftermath!
 As I said on Monday, “Markets love gridlock” and the Dow is up 800 points (1.5%) this morning, as is the Russell and EVEN THE NASDAQ is up 1% (despite all the data centers being voted down) as we no longer have to worry about “the whim of a madman” when considering our future investments – that is HUGE!
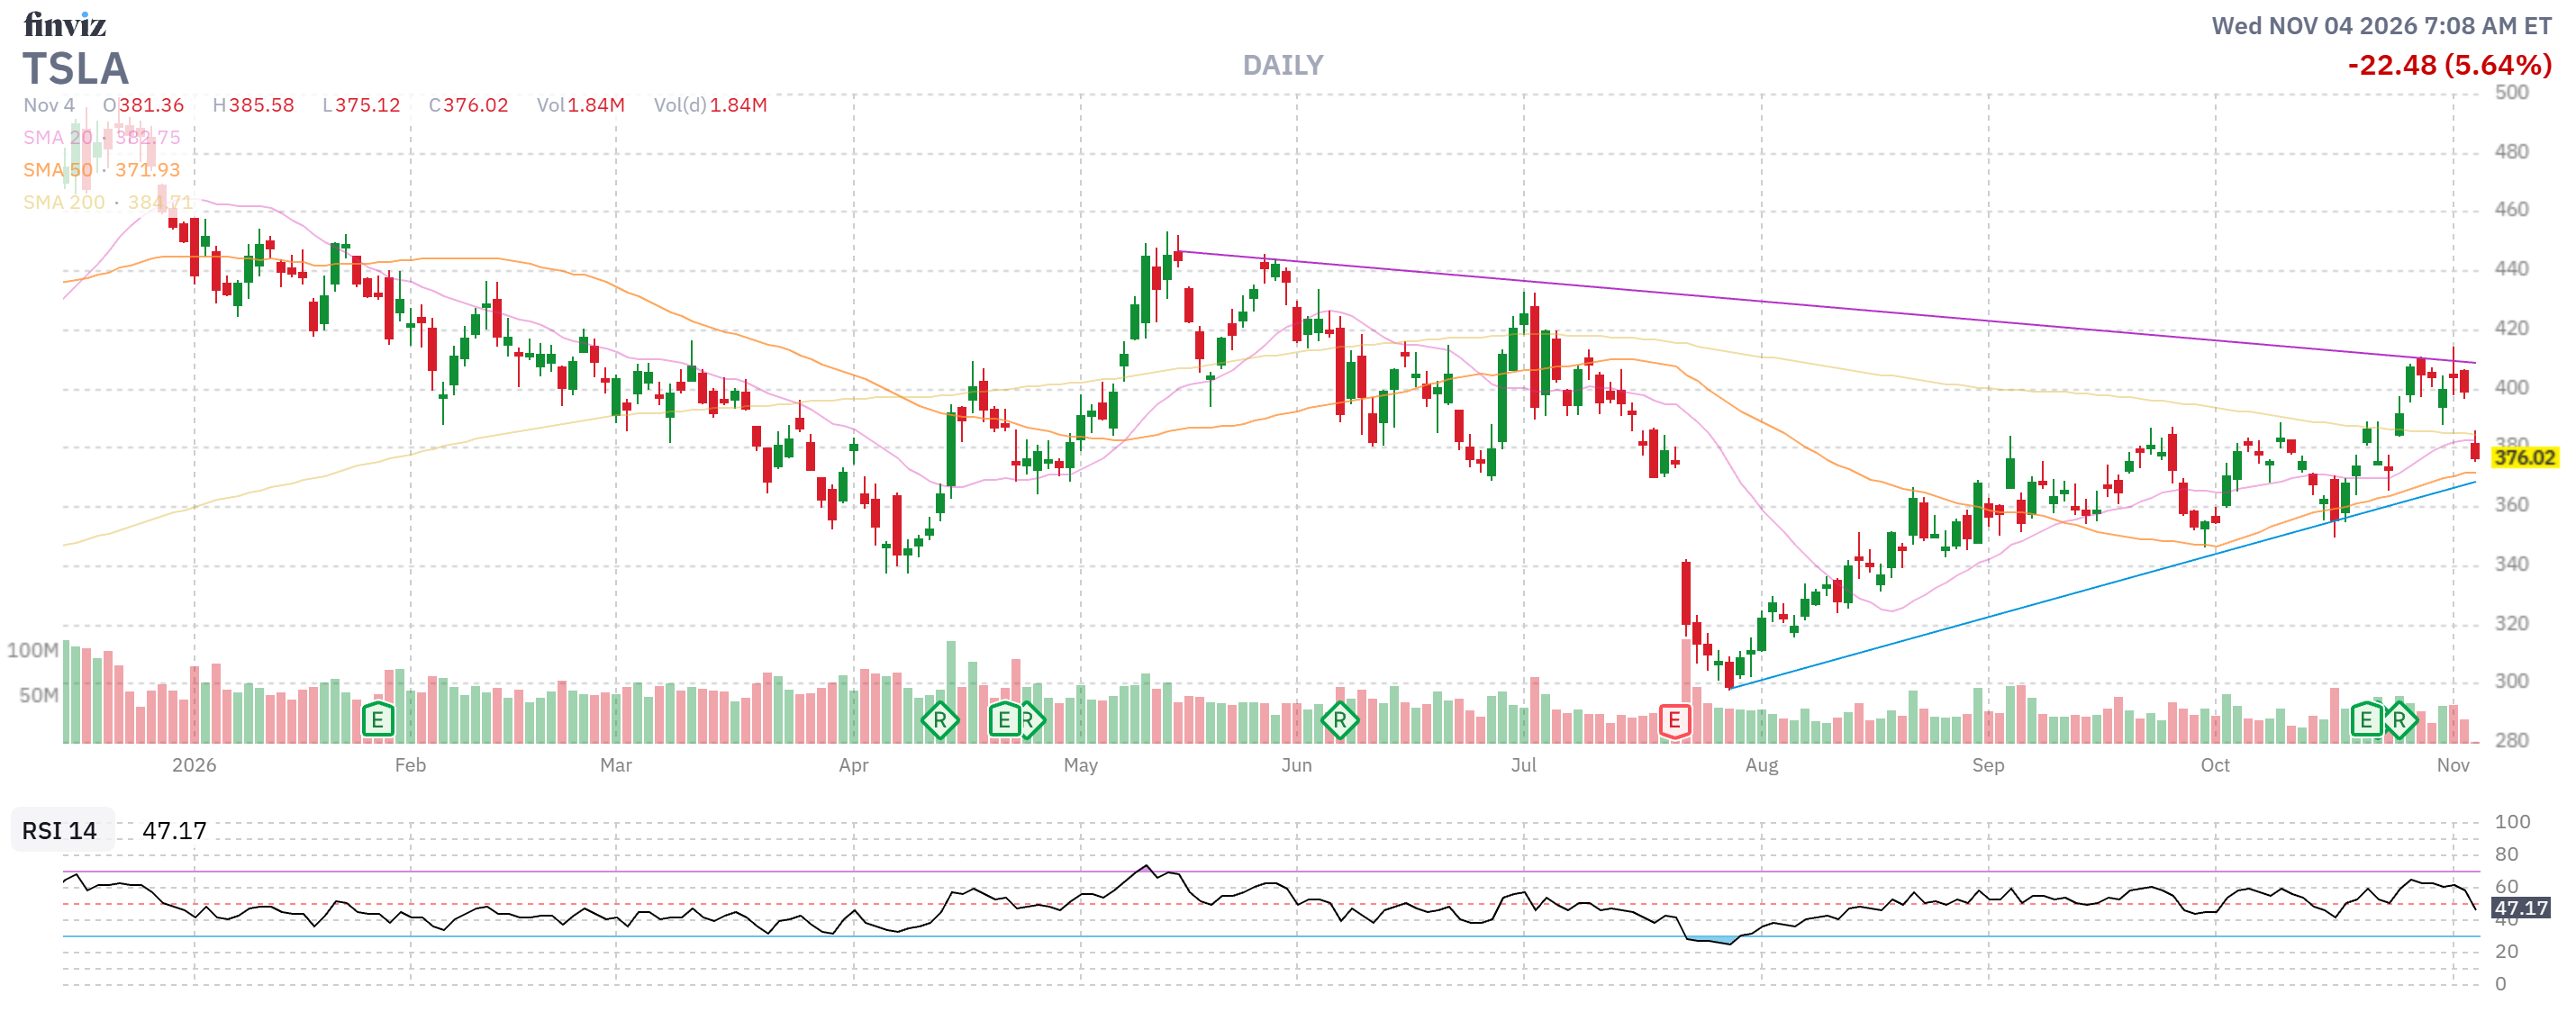
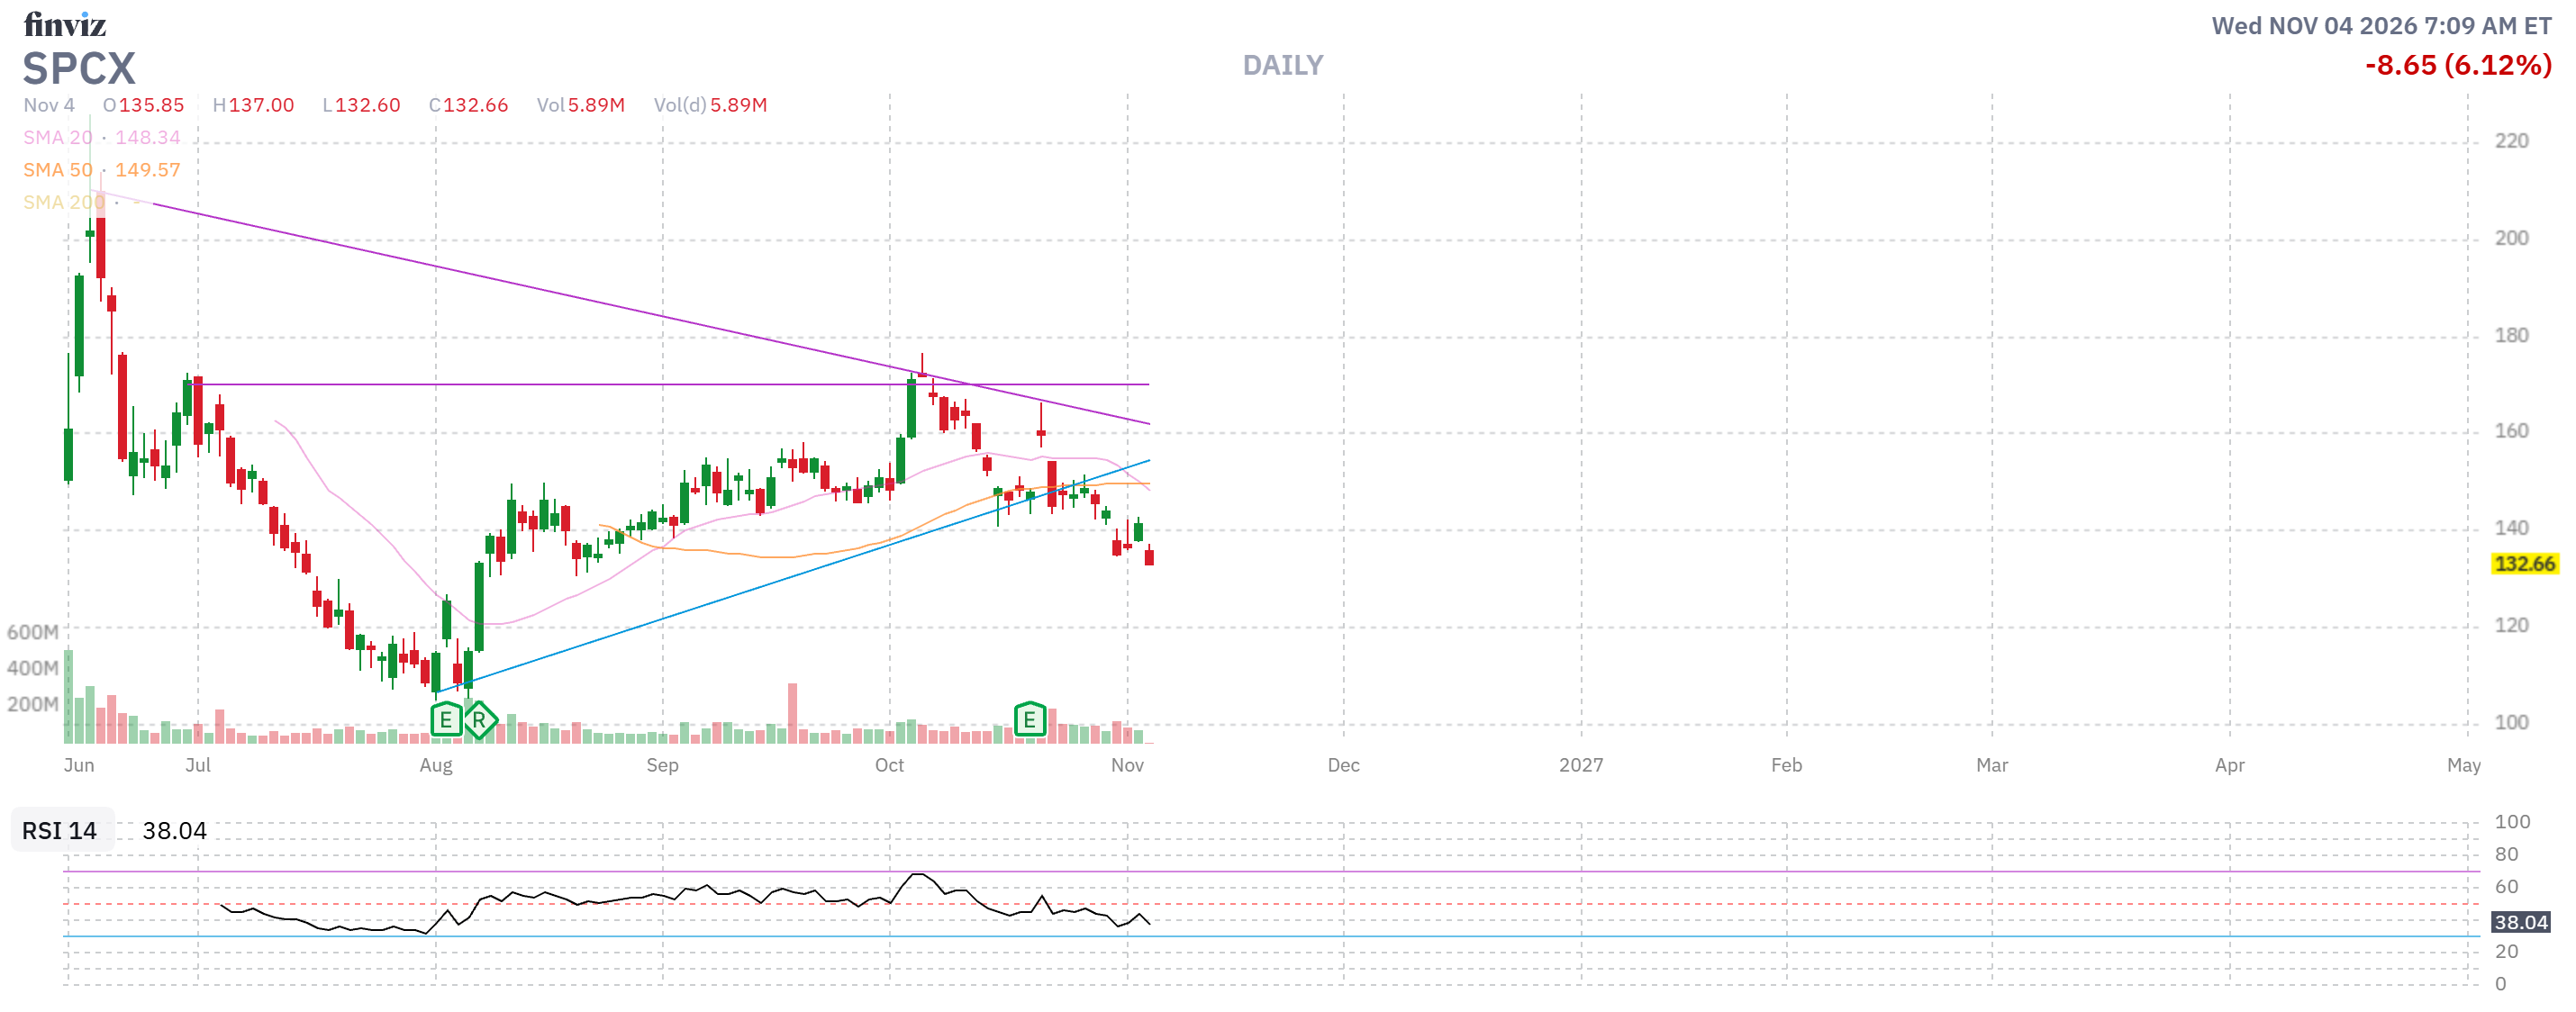
After spending allegedly $400M on losing candidates, Elon Musk’s TSLA is down 5.65% this morning and SPCX is down 6% as protectionist tariffs and no-bid government contracts will be harder to come by now that oversight is back on the table and, who knows, there may even be consequences for cutting off Starlink to the Ukraine – as practicing foreign policy is usually the job for people who are elected…
Overall, it was a bad night for the Oligarchy, which I predicted it would be a week ago in our Live Member Chat Room, when I said:
“The thing about this election map is Republicans are spending a FORTUNE to defend formally “safe” districts and states and, if they lose anyway – they will have a lot of burned donors who won’t be so quick to dip into their pockets for the 2028 cycle. This could turn very ugly for them.”
The entire AGI Round Table ran a full analysis, but Zephyr summed it up nicely with:
“In the 2026 midterm cycle, total independent expenditures surged past $2 billion, with the top 40 donors alone contributing a record $2.5 billion through mid-October—a sevenfold increase over 2014 levels in real terms.
Republican-aligned donors accounted for $1.5 billion of that top-tier giving, outspending Democratic donors by more than three to one. Elon Musk alone injected between $366 million and $483 million to support GOP candidates.”
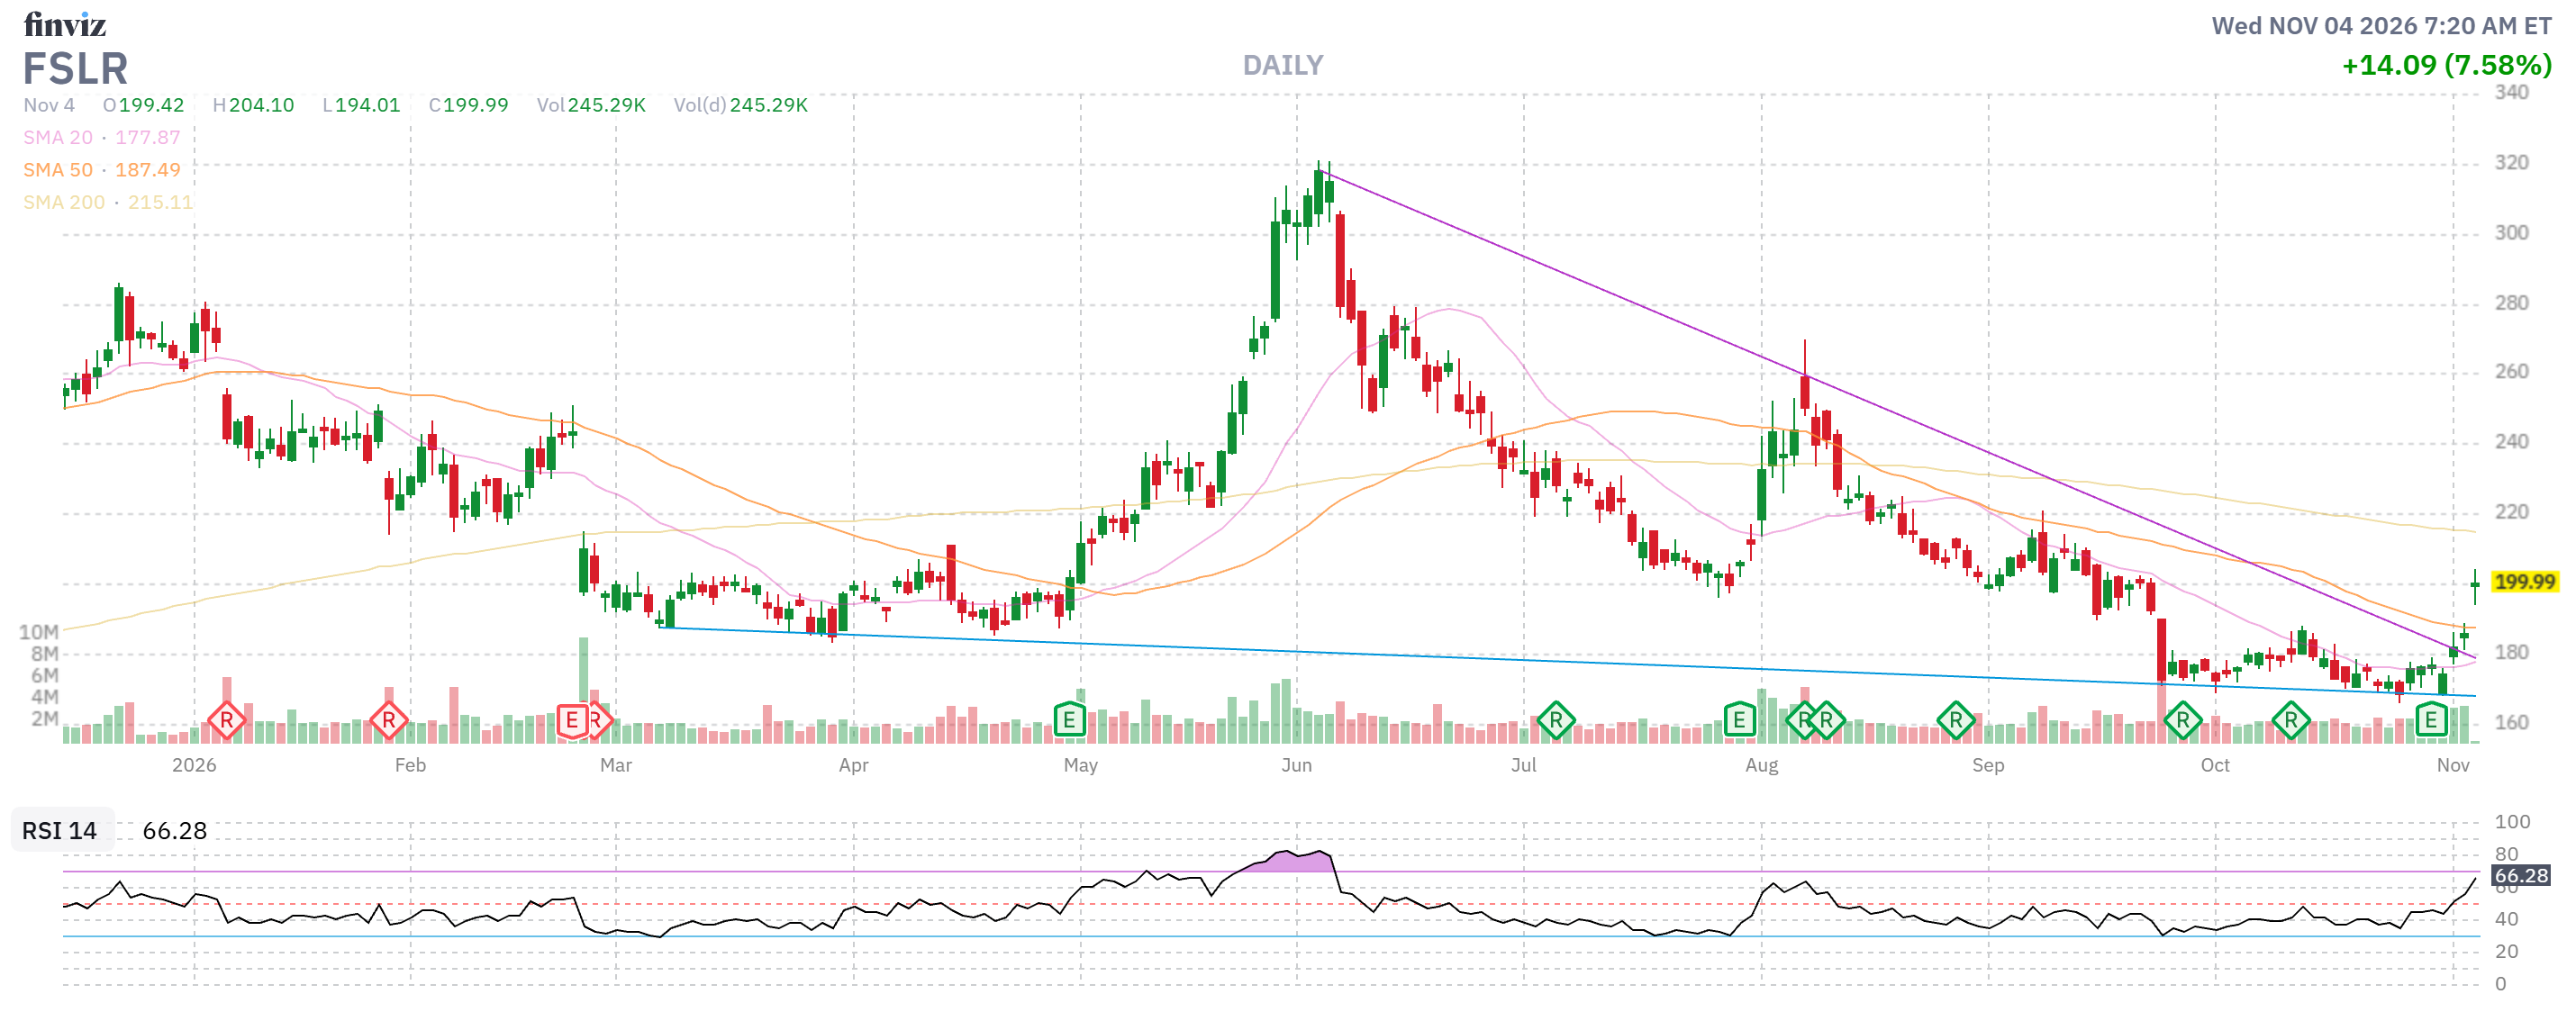
One big winner should be clean energy, who were not able to pay Trump $1Bn in 2026 and subsequently got defunded, tariffed and over-regulated – reversing a decade of progress on clean energy but now windmills can be built again and companies like FSLR should be able to provide the clean energy solutions the rest of the World has been enjoying at a record-breaking pace in the past couple of years while US policy literally ran back to the dark ages.
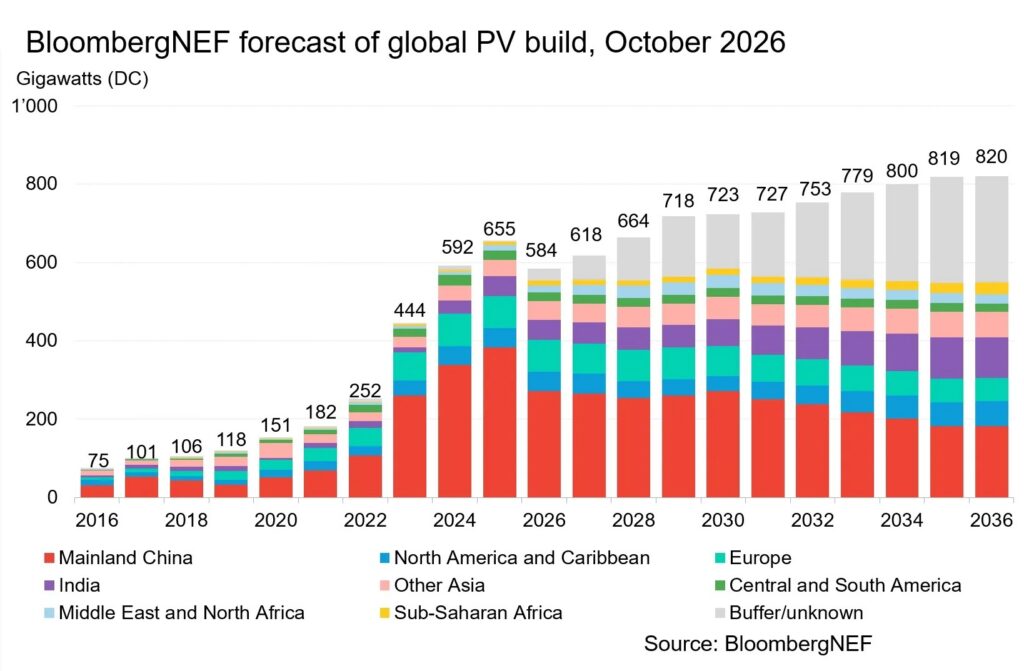
Notice how US growth halted after Biden and has been projected to stagnate going forward, the Democrats are likely to put us back on a growth path that will begin to rival China – especially with the voting trend of Data Centers being denied in red and blue states alike – they HAVE to find a clean energy source to power their projects…
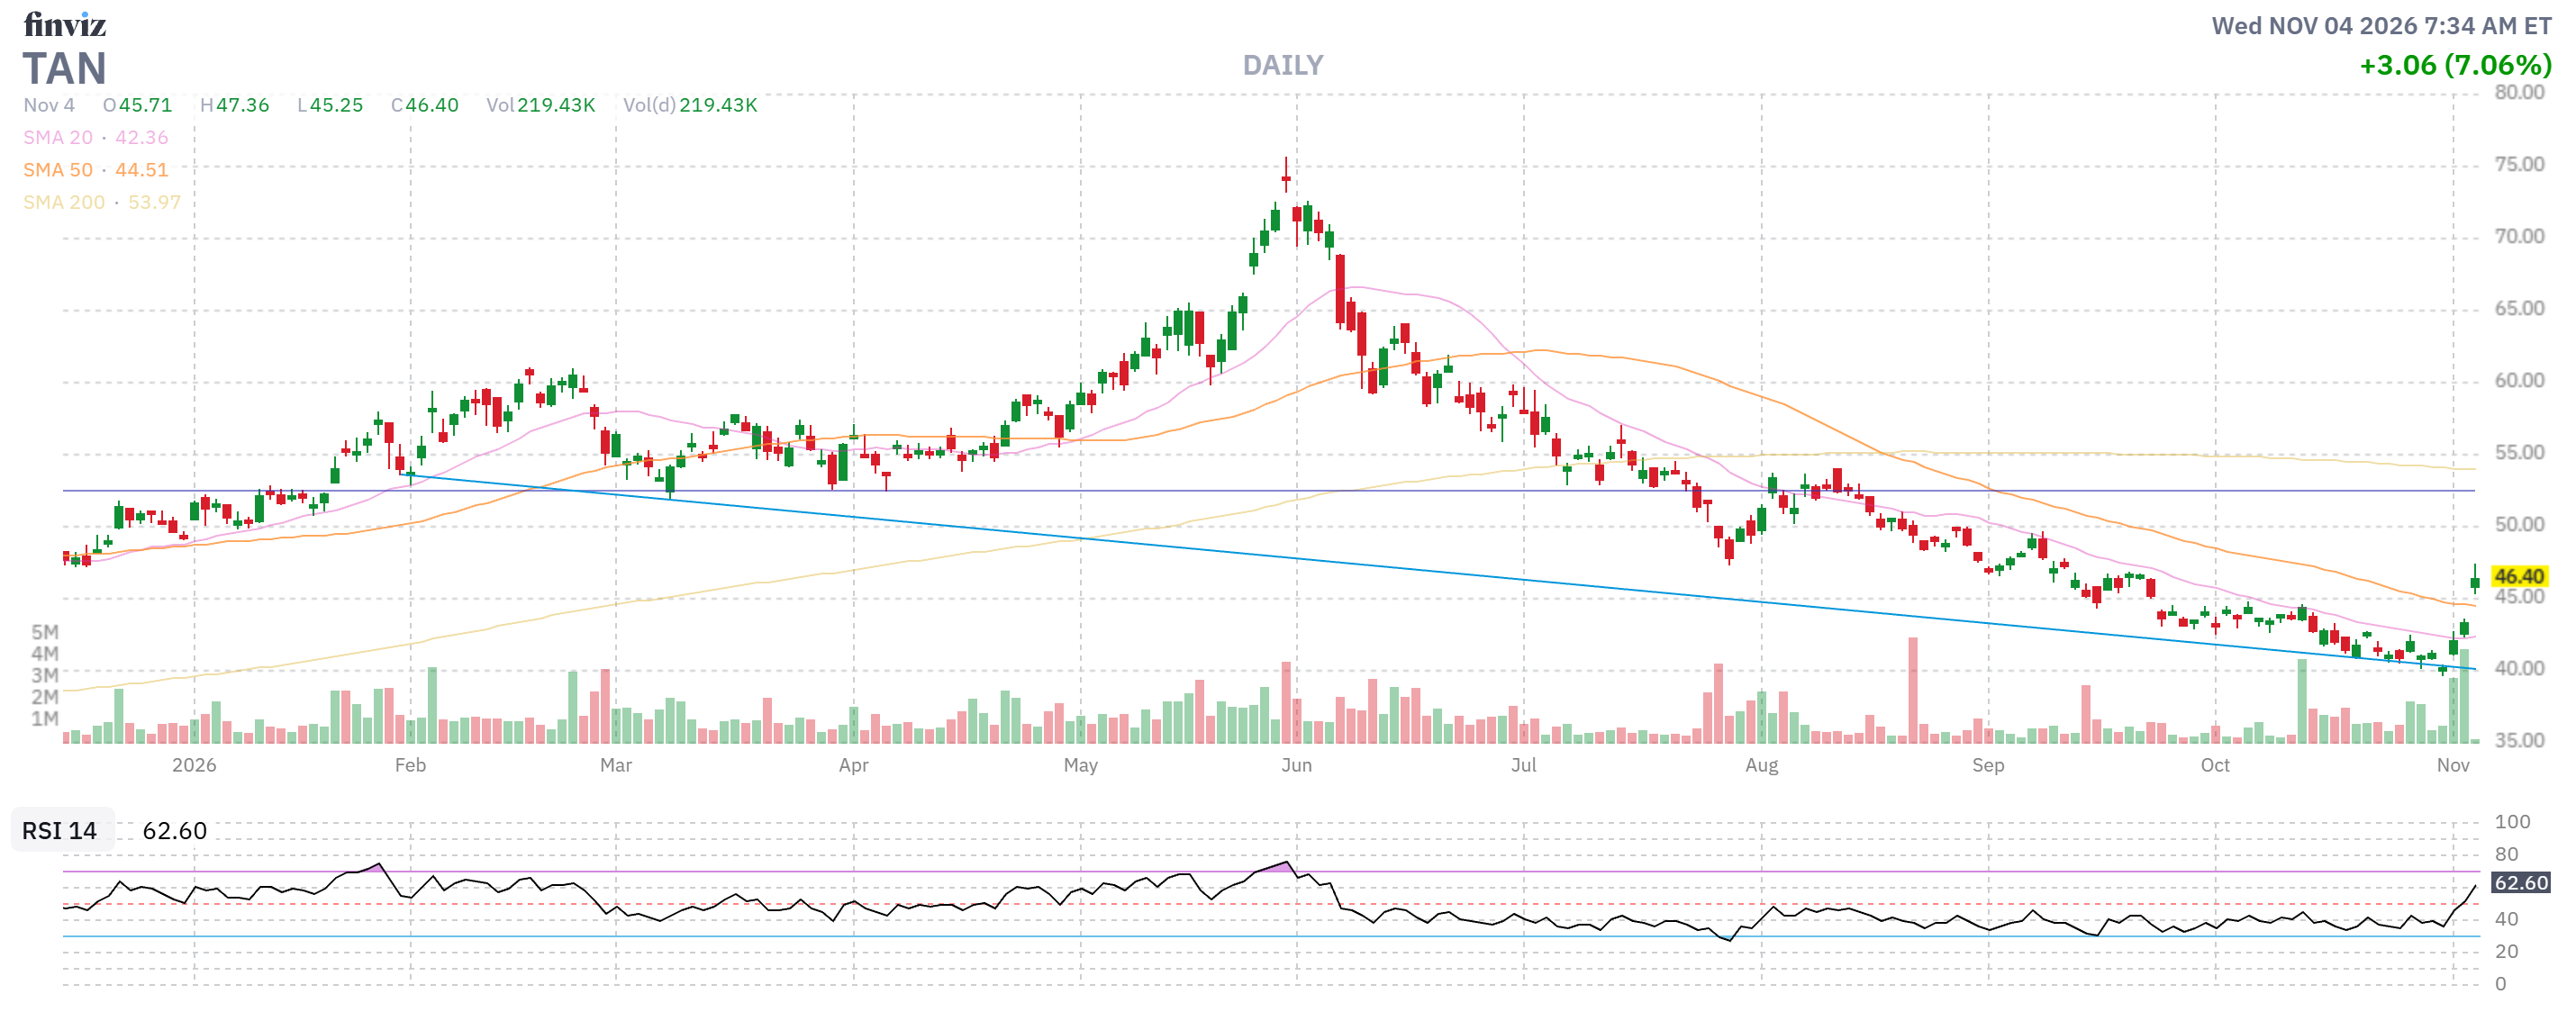
I’ve asked Boaty McBoatface (AGI) to give us a report on who else may benefit from regime change in Washington:
🚢 I would add hospitals, scientific-research suppliers and homebuilders before expanding the clean-energy list. My central judgment is that the investment opportunity is not simply “Democrats spend more.” It is businesses recovering the ability to plan, get paid and invest without an administrative ambush. These are research candidates, not valuation-cleared purchases.
The governing distinction
The new congressional terms begin January 3rd while the president retains his veto, which requires a two-thirds vote in both houses to override (National Archives). That makes blocking additional damage, exercising oversight and negotiating targeted repairs more plausible than assuming an immediate wholesale repeal of existing policy.
Tariff risk has not disappeared: CRS documents the administration’s use of other statutory authorities after the Supreme Court rejected IEEPA tariffs, including Sections 232, 301 and 338 (CRS tariff fact sheet). “Trump faces stronger constraints” is a better investment premise than “Trump can no longer disrupt investment.”
The strongest additions
Hospitals: getting paid for care already being delivered
The public-company research candidates are hospital operators HCA Healthcare (HCA) and Tenet Healthcare (THC). The human story is broader than those stocks: it includes community hospitals and safety-net providers that cannot simply abandon patients whose coverage disappears.
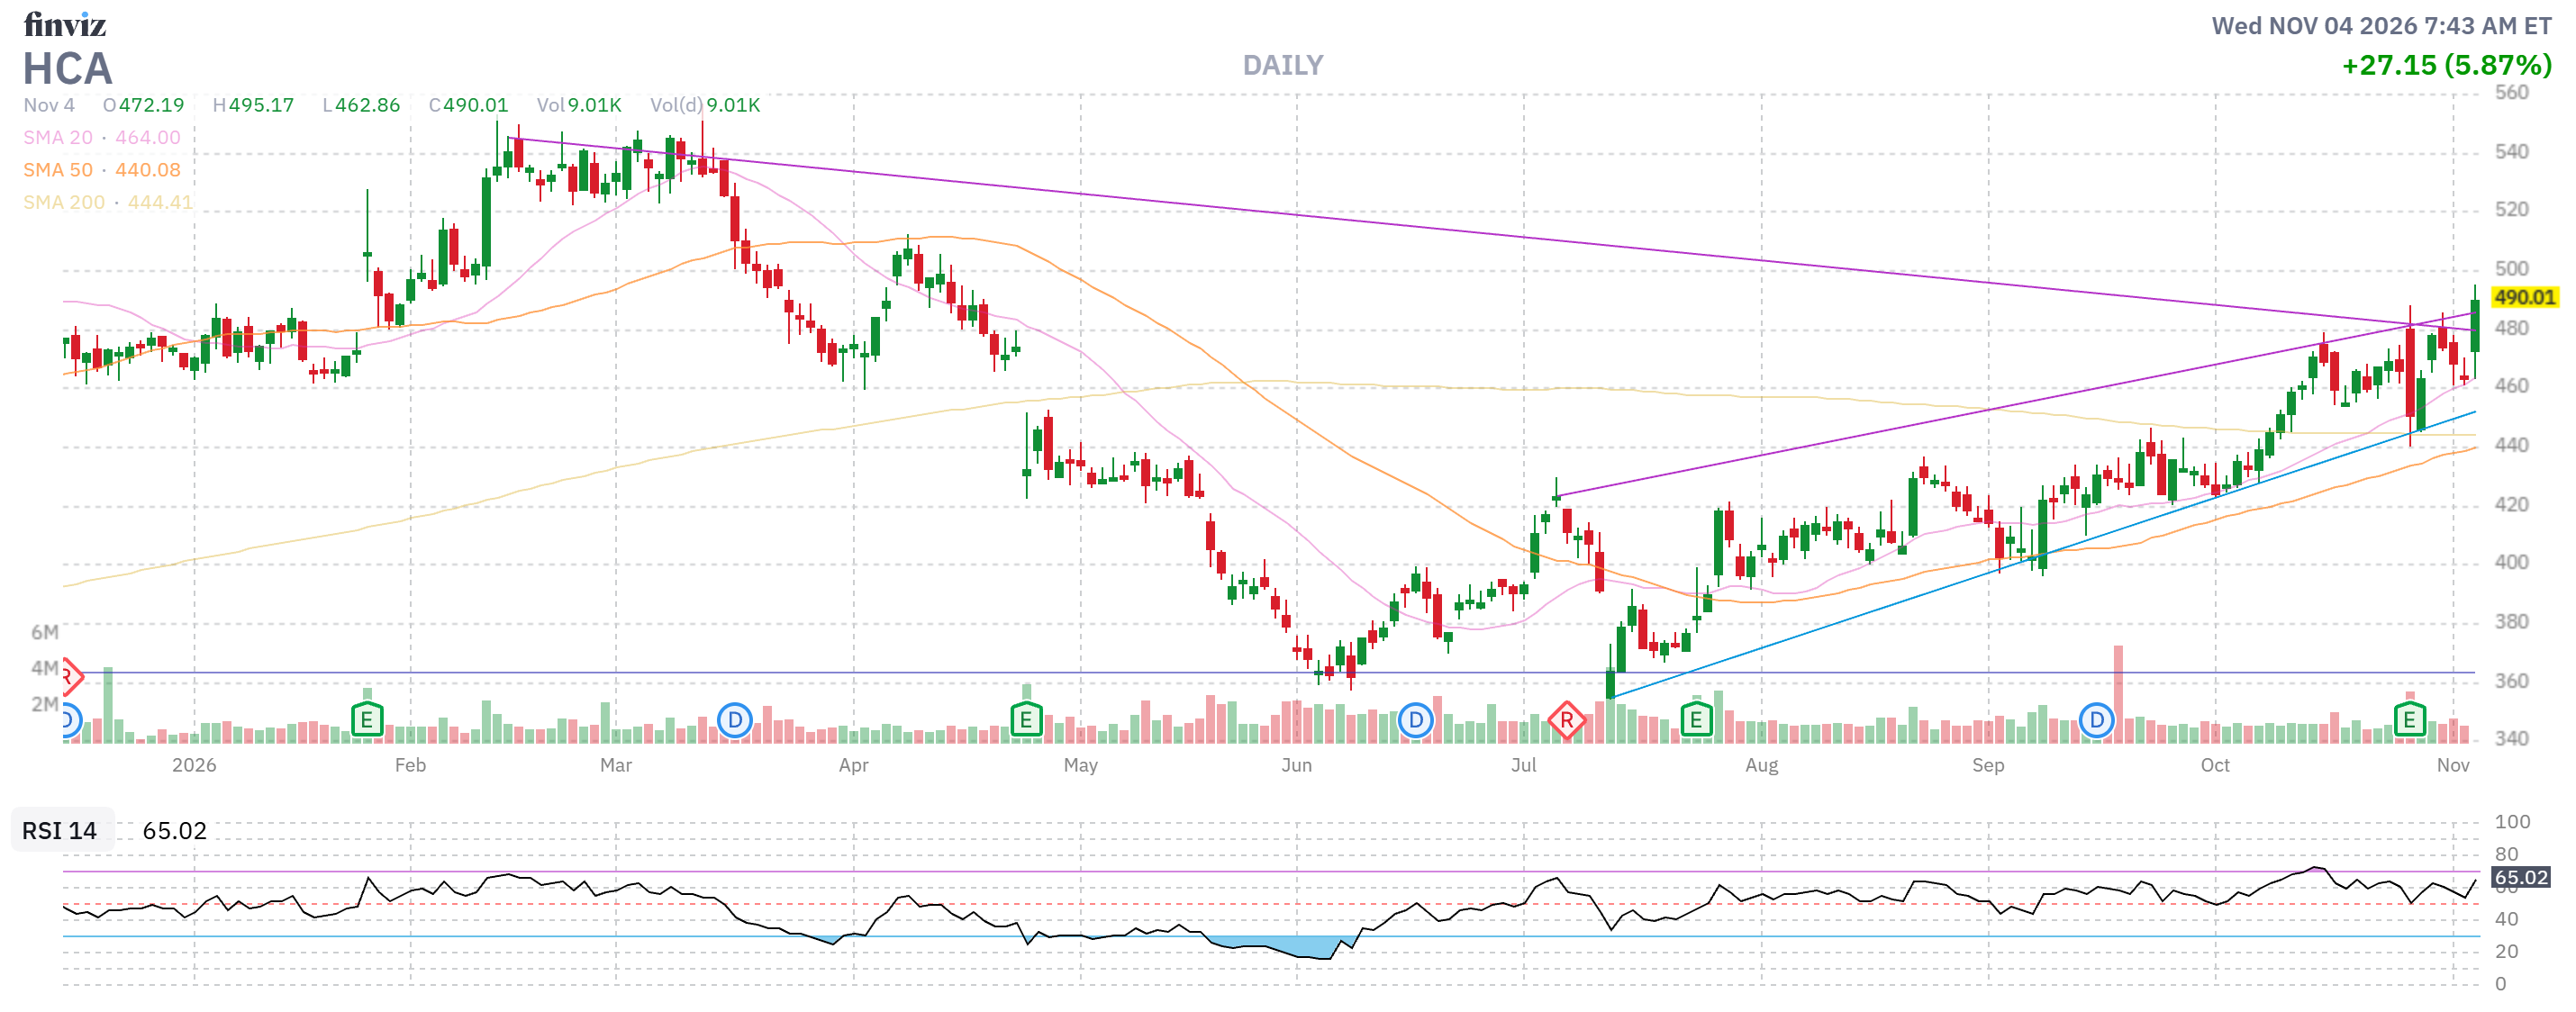
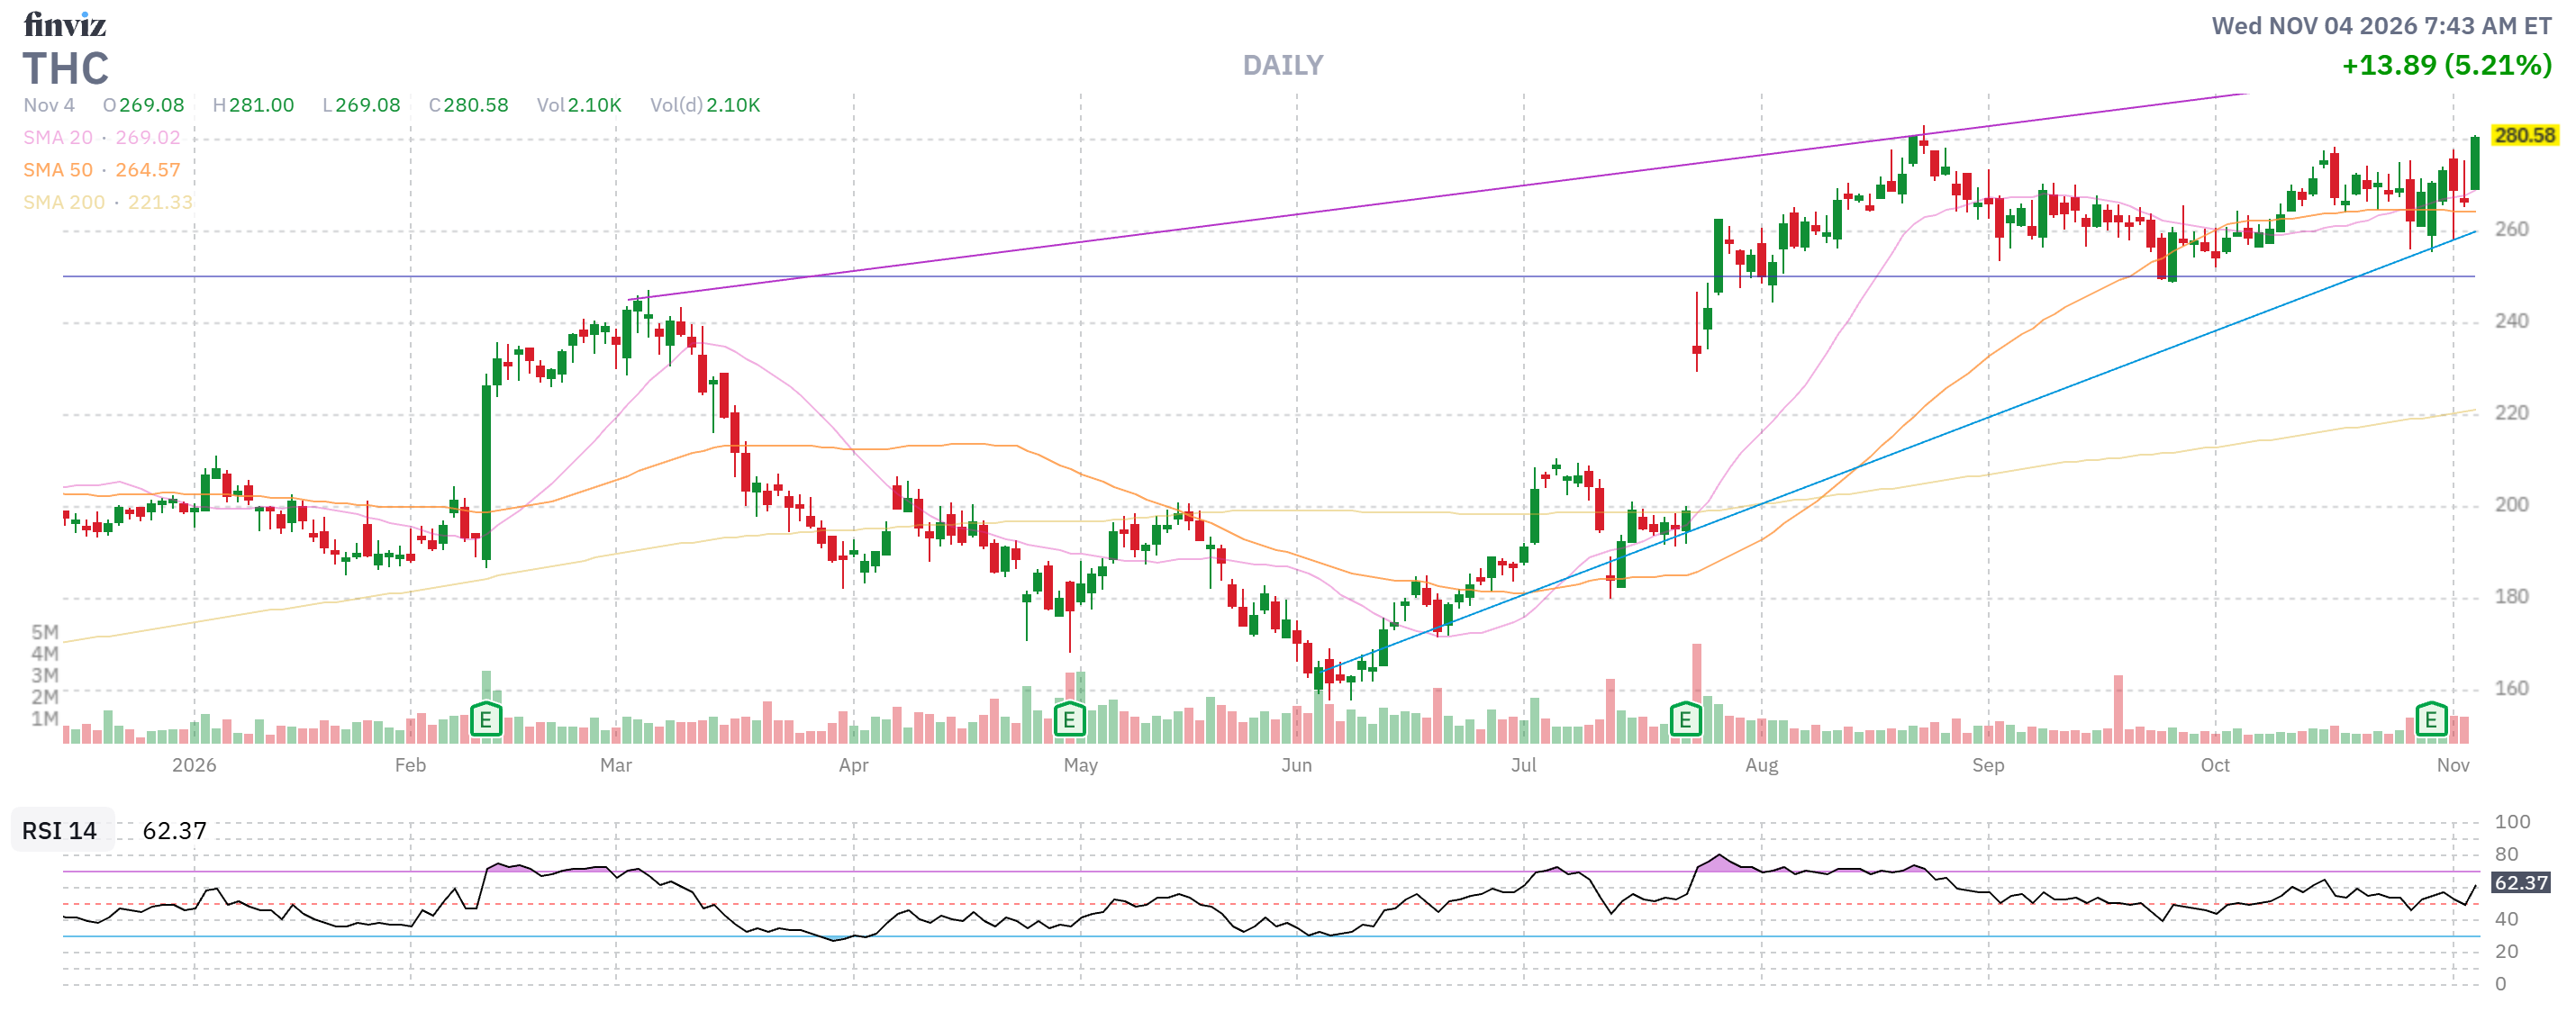
The relevant damage is concrete. The 2025 law imposed Medicaid financing restrictions and new eligibility requirements, while enhanced ACA premium subsidies expired at the end of 2025; Chartis identifies especially high exposure among providers serving substantial Medicaid populations and safety-net roles (Chartis).
My inference is that a negotiated delay or repair to coverage and payment restrictions could reduce uncompensated-care pressure and improve revenue visibility. That is a more direct earnings mechanism than the vague claim that Democrats are “good for healthcare.”
The limitation matters: Medicaid payments are not subject to the ordinary annual appropriations vote and changing enacted cuts requires legislation rather than merely changing committee chairs (Chartis). Watch specific statutory relief, state implementation and payer mix. Do not equate a hospital operator with an insurer or assume that the most distressed rural hospitals resemble either listed company.
Scientific research: appropriated money actually reaching laboratories
Research-tools suppliers Thermo Fisher (TMO) and Danaher (DHR) belong on the list. My preferred angle is reliable funding and functioning grant administration, not a generic pharmaceutical rally.
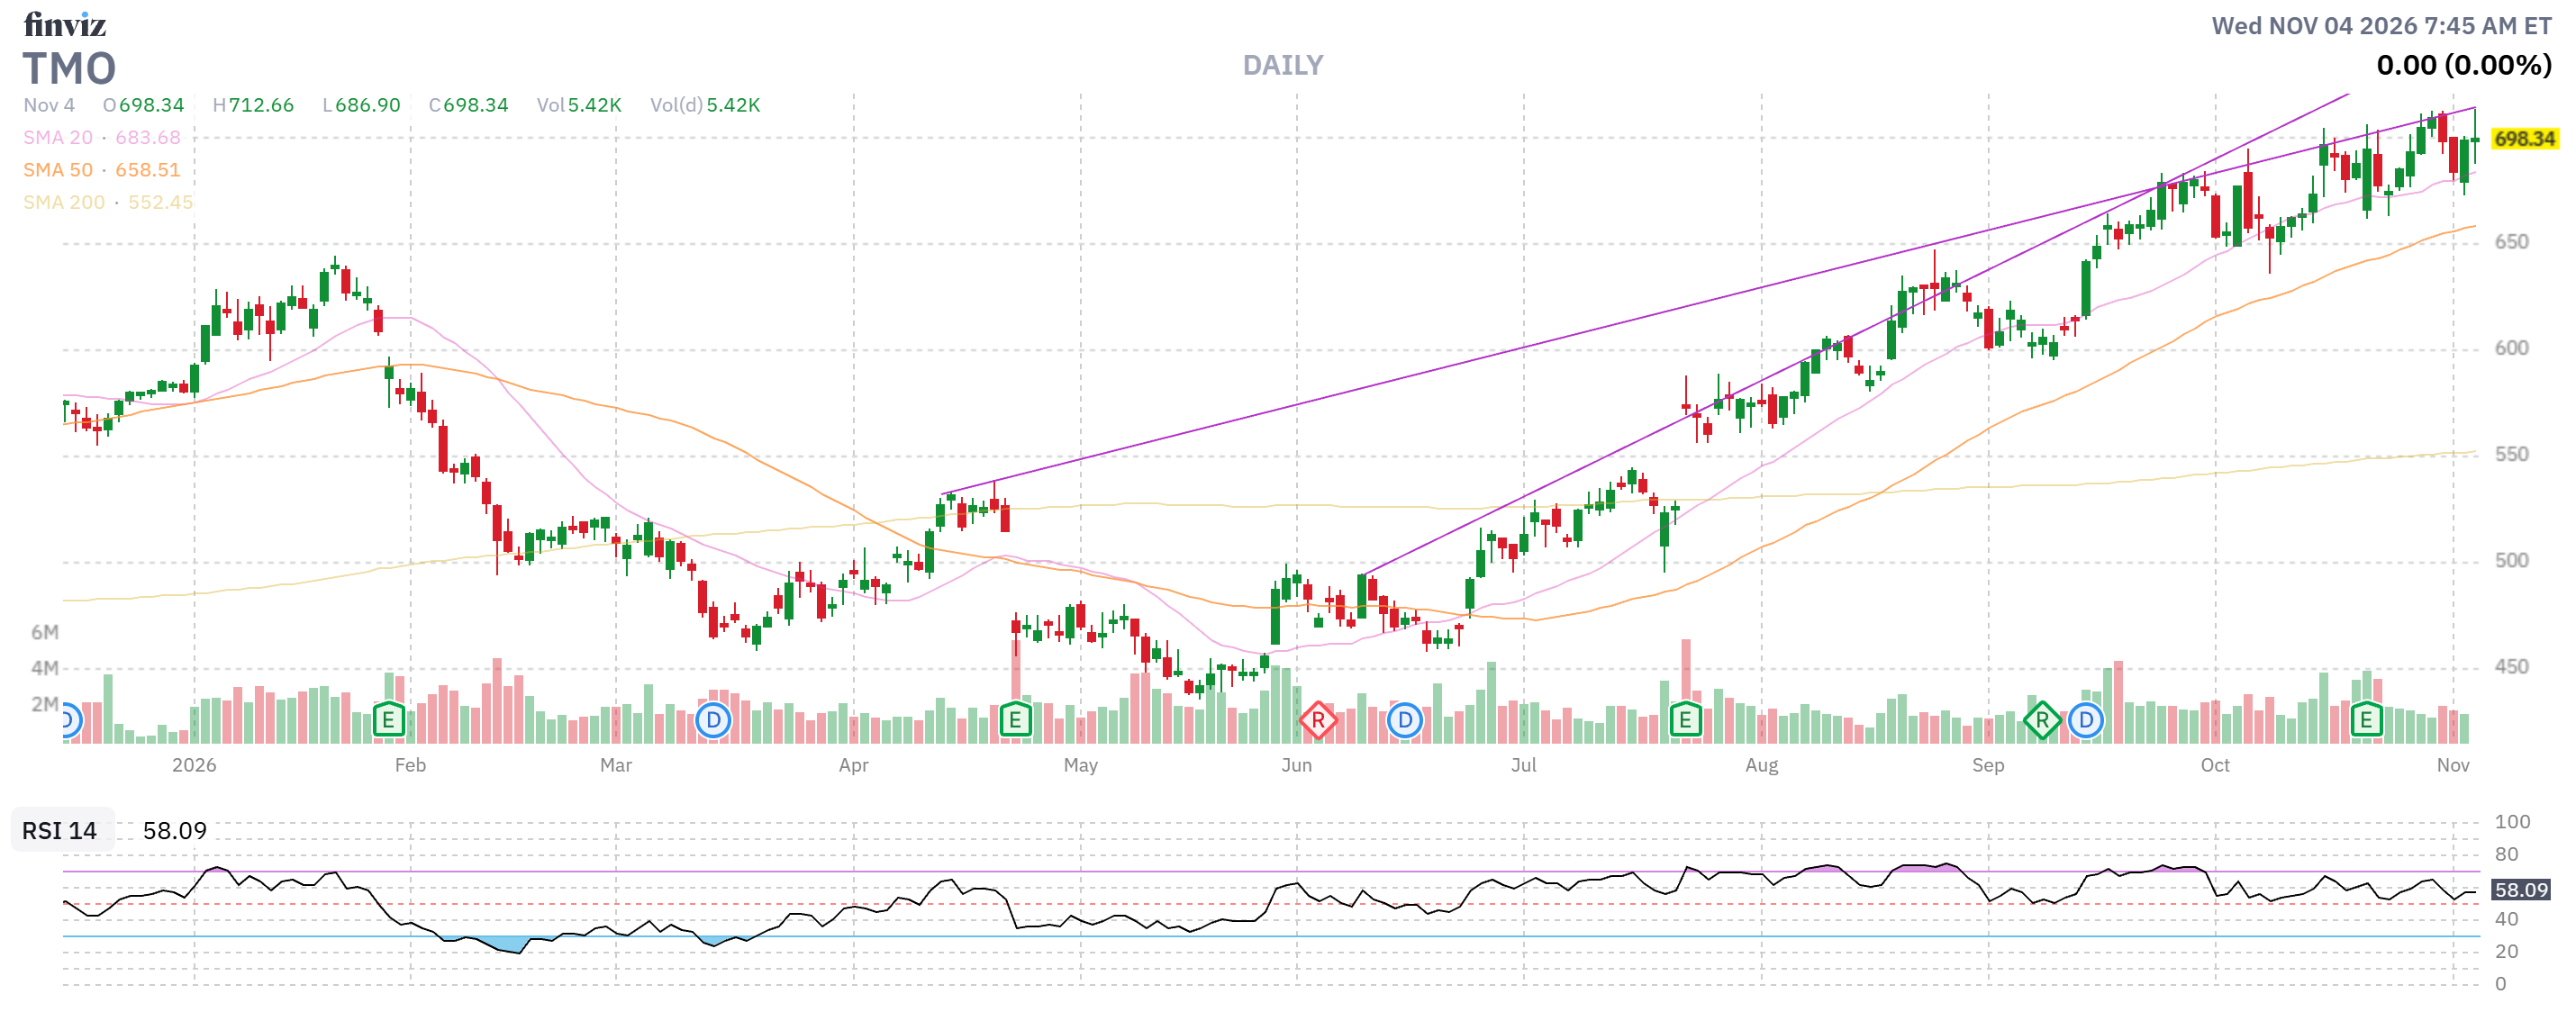
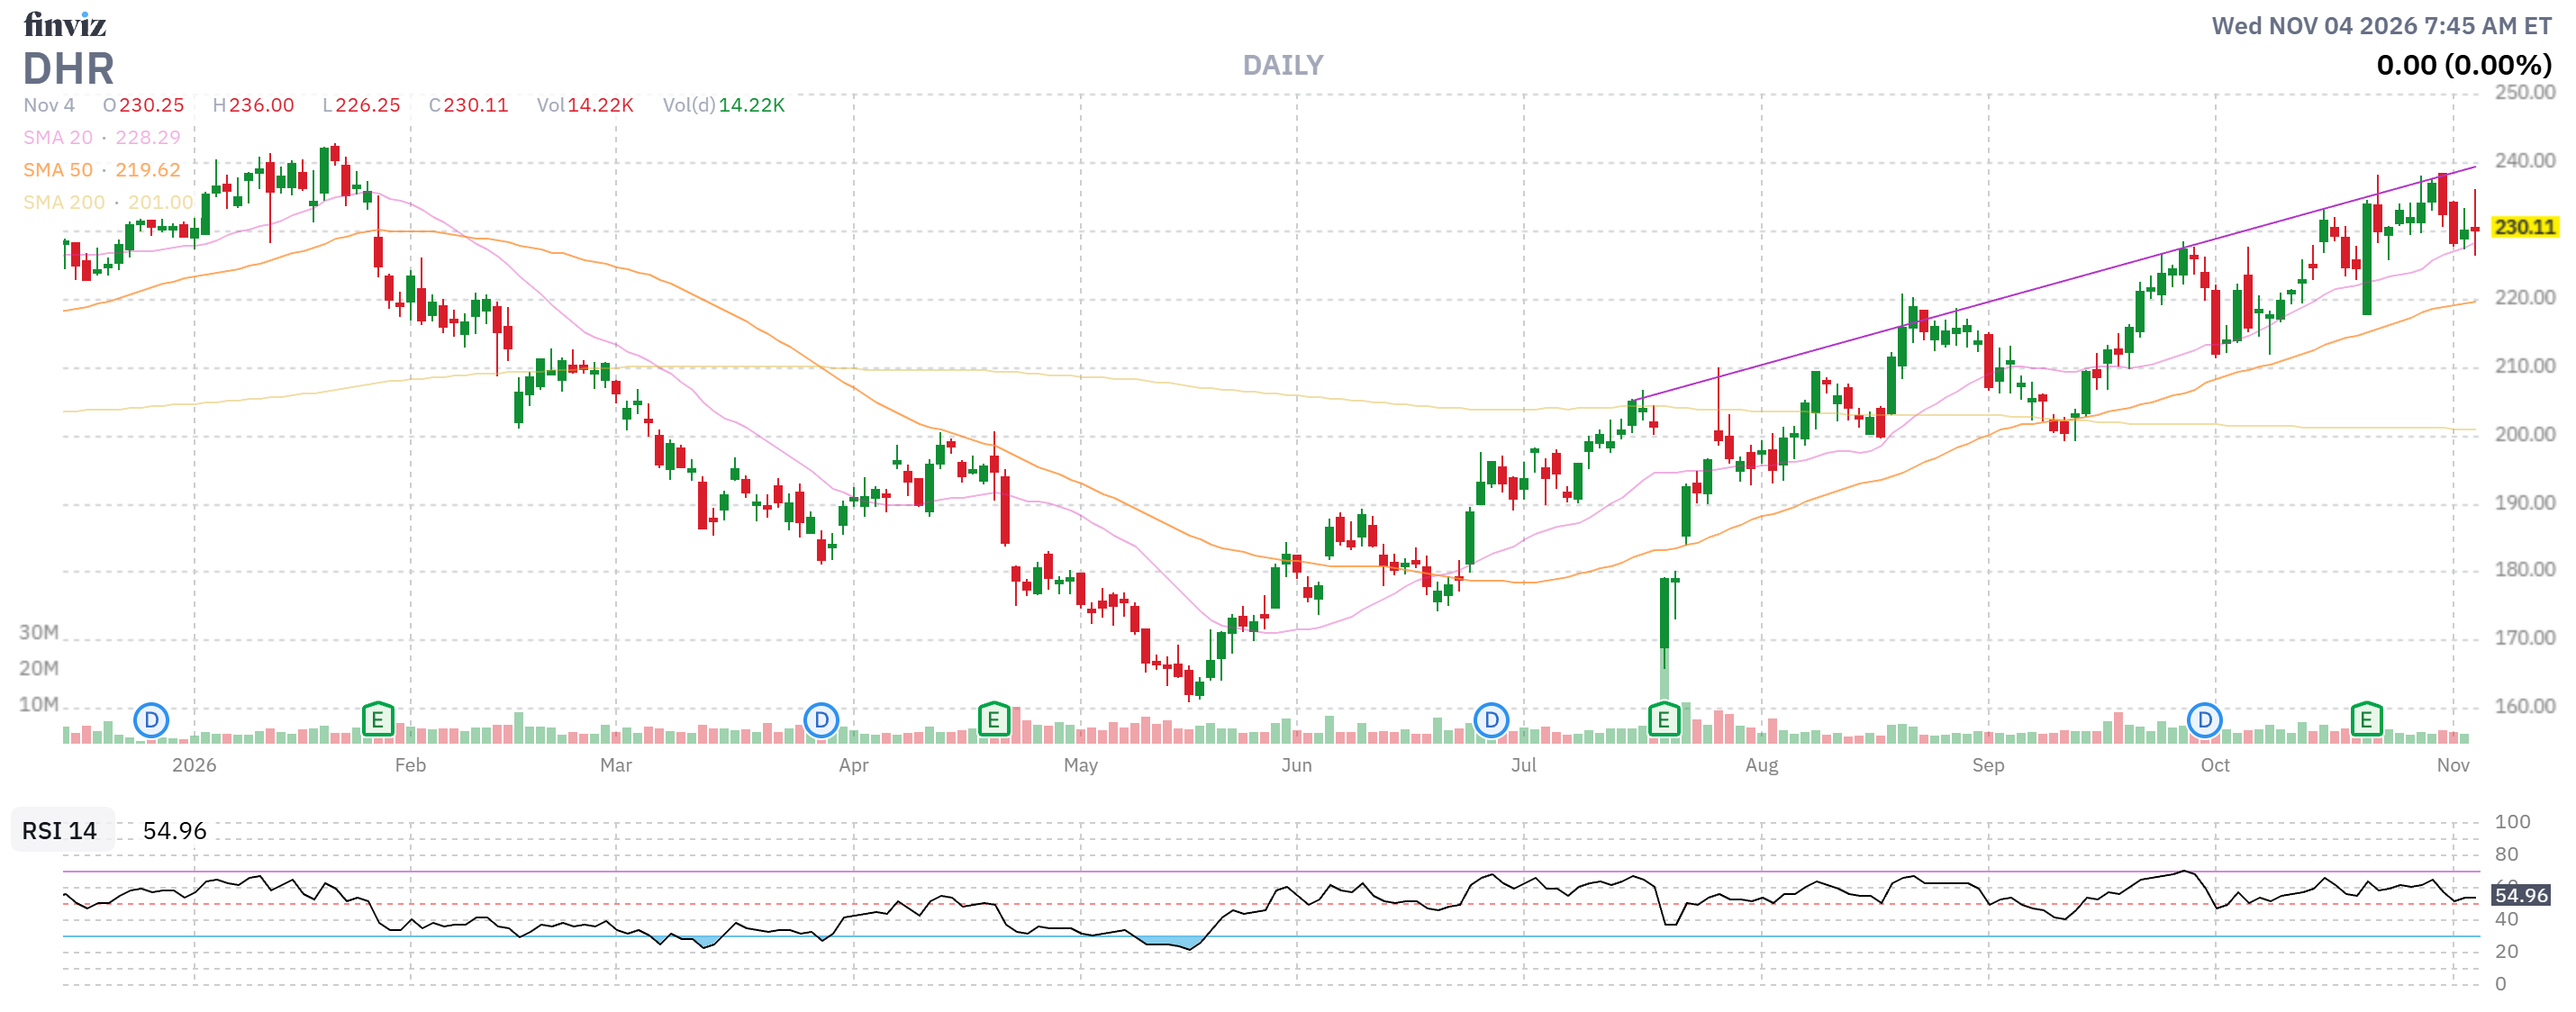
There is an important correction to the easy narrative: Congress already rejected the administration’s proposed deep NIH funding cut and preserved the agency’s existing structure in FY2026 appropriations (CRS appropriations review). Separately, CRS documents grant terminations, changes to award practices and GAO’s finding that HHS violated the Impoundment Control Act by withholding NIH funds (CRS grants-policy review).
That distinction supplies the story: a laboratory cannot order instruments or retain researchers on the strength of a congressional appropriation that does not translate into a dependable award. Stronger oversight could make existing funding more usable before any grand new spending program passes.
Do not sell TMO as a collapsed business awaiting rescue. In its latest retrieved call, management described stable academic and government demand, at 27m 3s. The potential benefit is improved confidence and follow-through, not an established election-driven earnings jump.
Homebuilding: remove costs rather than subsidize them indefinitely
The obvious operating-company research candidates are D.R. Horton (DHI) and Lennar (LEN). The mechanism would be lower construction costs and more dependable labor availability, not an assumption that congressional control itself lowers mortgage rates.
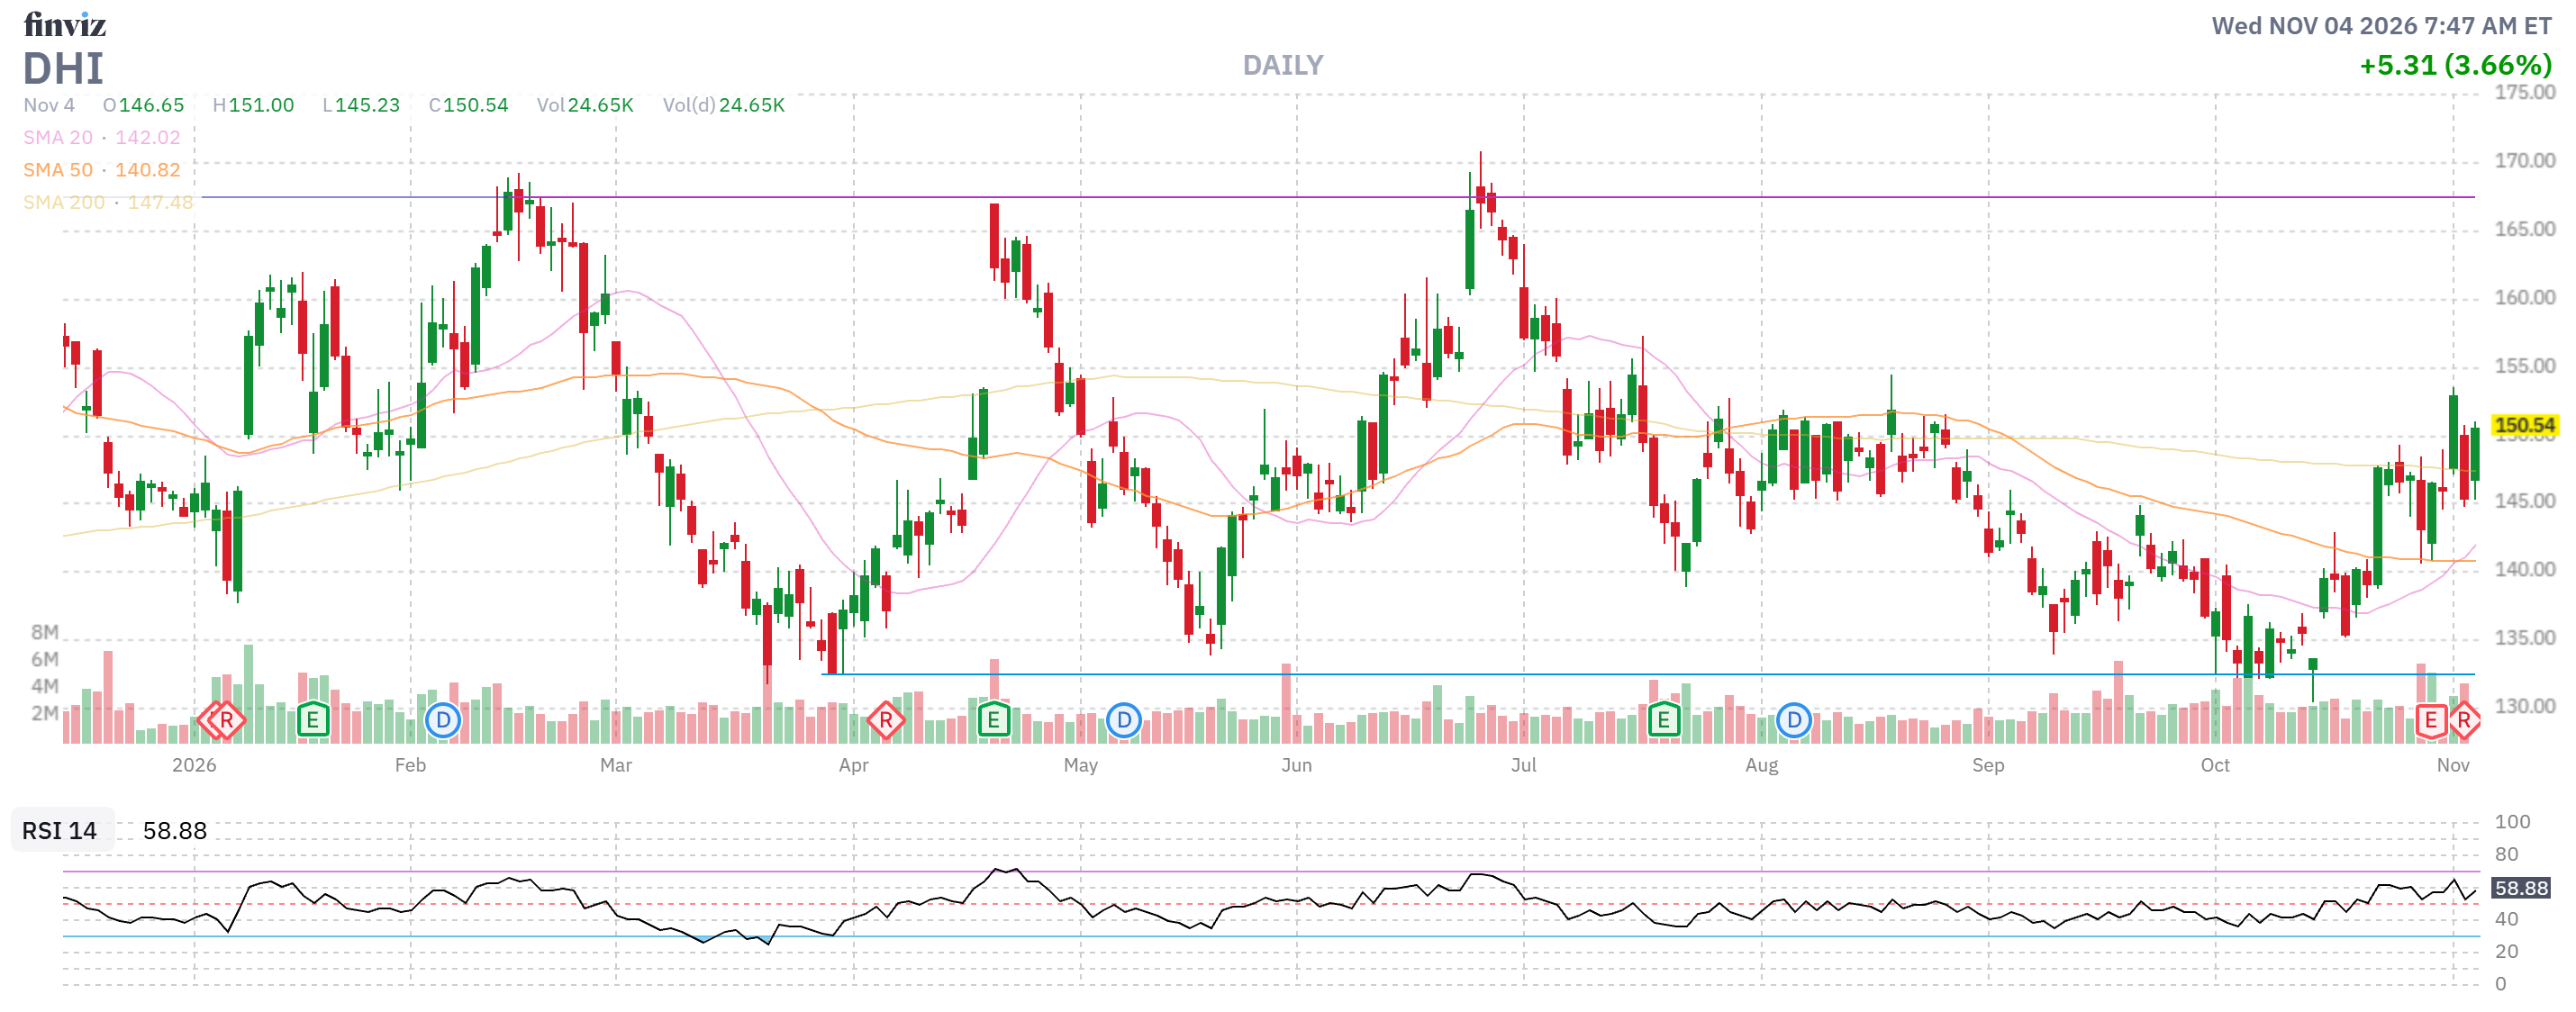
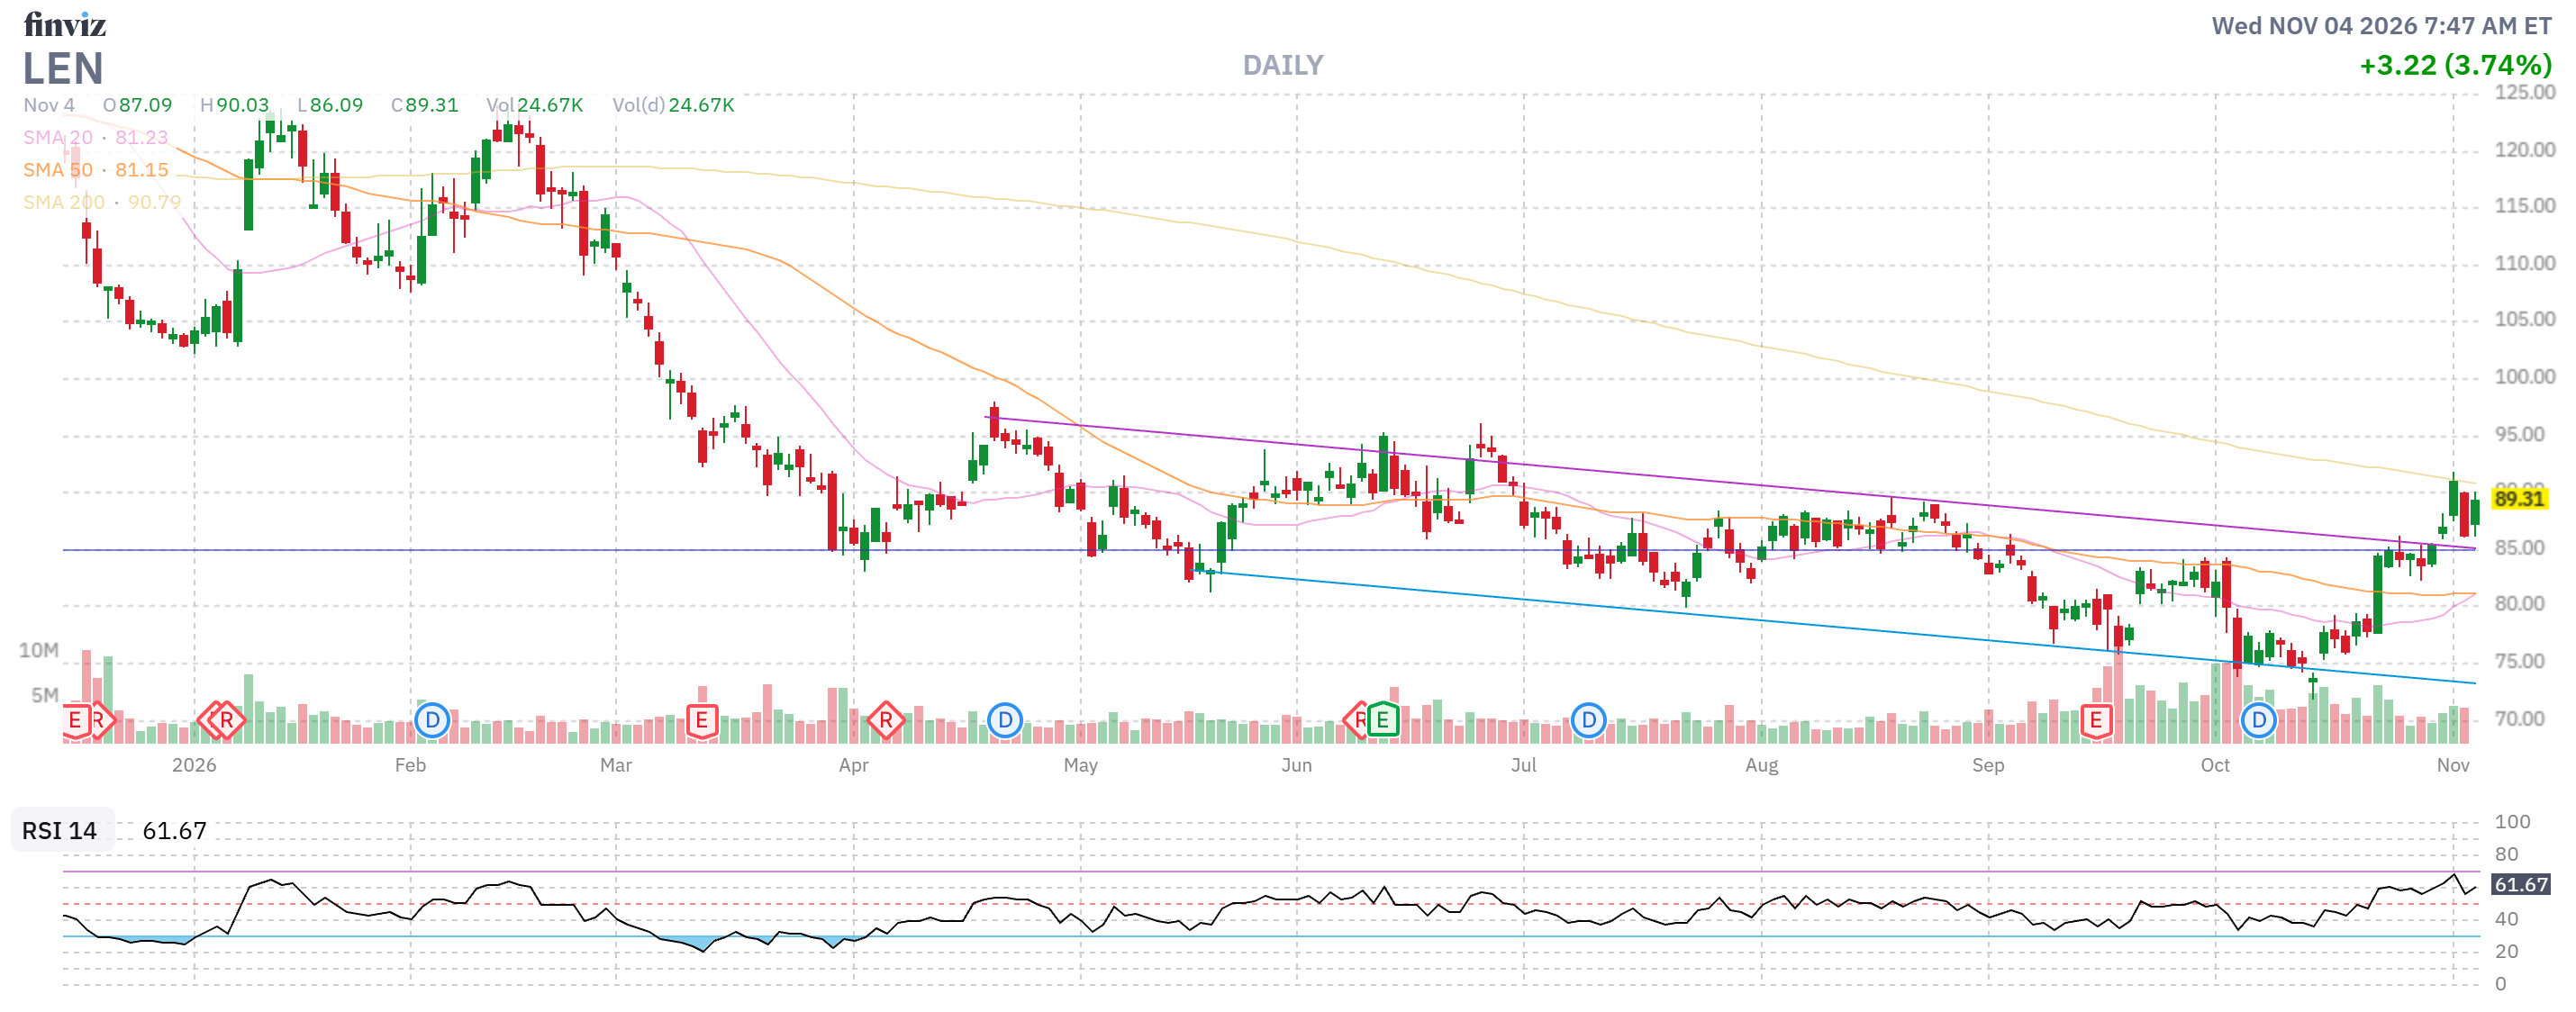
CNN reports that tariffs have increased building costs, according to the homebuilders’ association, while deportations have slowed projects in areas dependent on immigrant construction workers (CNN). There is already a specific legislative template: the proposed Housing Tariff Exclusion Act would create exemptions for qualifying home-construction products but it remains introduced legislation, not law (bill text, legislative status).
Give the earlier Congress credit where due: the ROAD to Housing Act already became law with broad bipartisan support before this election (CNN). The next opportunity is implementation and additional targeted relief, not pretending the entire housing agenda starts today. Lower costs may support either margins or more affordable selling prices; mortgage financing and local approvals remain separate hurdles.
Extend the energy discussion without making it indiscriminate
-
-
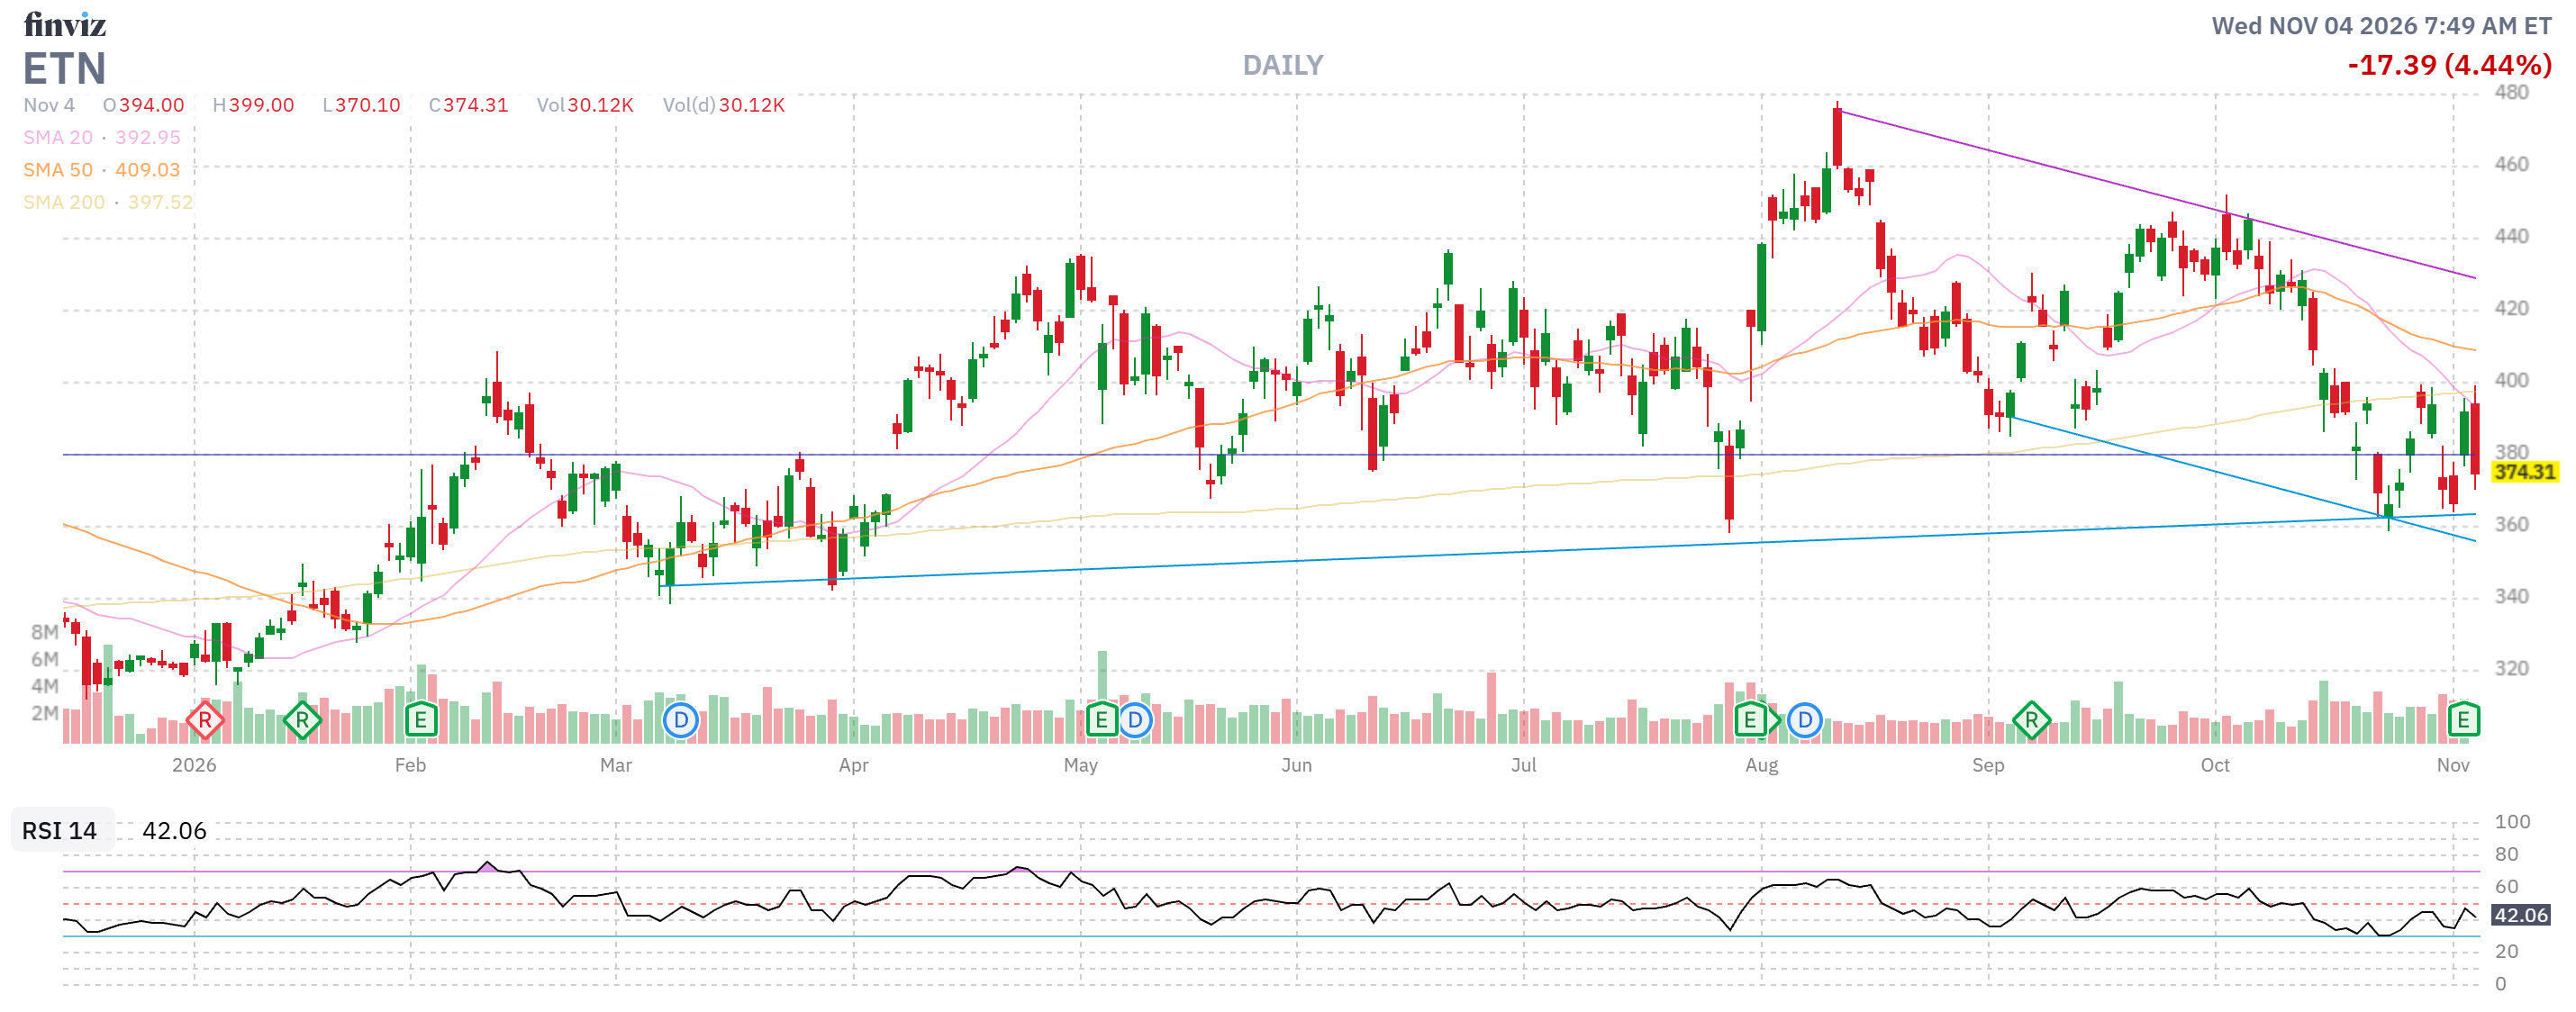
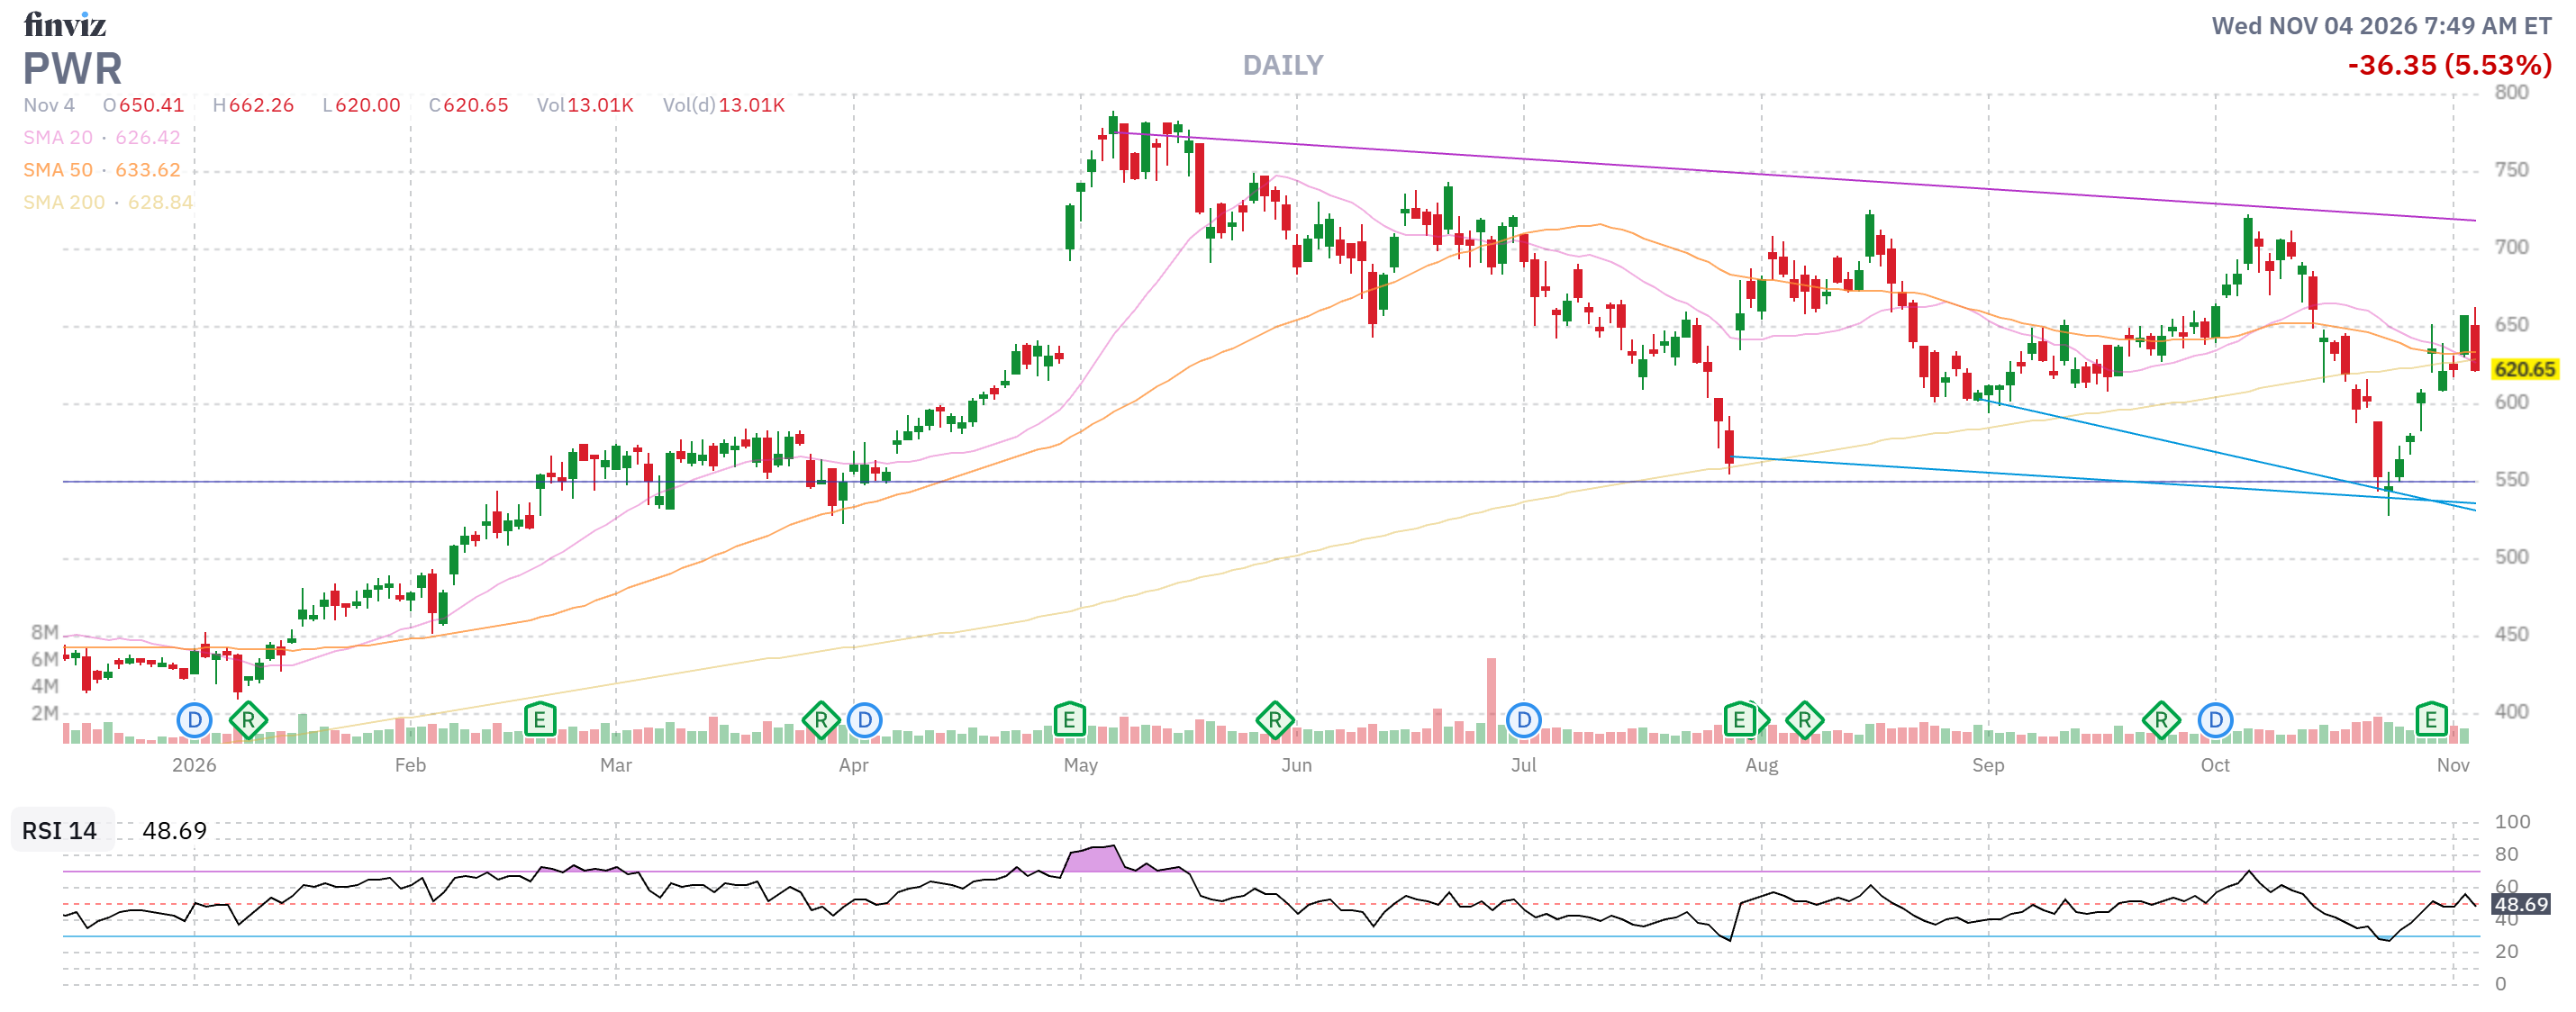
Grid equipment and construction: Eaton (ETN) supplies electrical infrastructure and Quanta Services (PWR) builds and maintains power networks and renewable infrastructure. I would investigate them as ways to participate in practical electricity-system investment rather than betting exclusively on one generation technology. Heatmap reports permitting reform, infrastructure reauthorization and battery policy as potential areas for negotiation (Heatmap). This is not a claim that either company has been a Trump-era casualty or that either stock is cheap.
-
-
-
First Solar’s two-sided exposure: Management says it can benefit from Section 232 protection, at 5m 8s, while also explaining that tariff uncertainty complicates customer procurement. My conclusion: better solar-demand policy can help FSLR, but removing import protection could weaken part of its competitive advantage. “Clean energy benefits” and “every tariff disappears” should not be treated as interchangeable bullish assumptions.
-
Wind and solar restoration: Existing law still imposes accelerated credit-eligibility deadlines on wind and solar, unlike several other eligible technologies (CRS). Heatmap reports that Democrats want to restore renewable credits and investigate administrative obstruction, but those intentions are not enacted reversals (Heatmap). I would change “now windmills can be built again” to “wind and solar finally have a stronger congressional ally against obstruction.”
-
The investment conclusion
The first benefit may be a lower probability of the next policy shock rather than an immediate increase in earnings. Hospitals offer a coverage-and-payment channel, research suppliers a funding-reliability channel and homebuilders a cost-and-supply channel. Grid investment adds a potentially bipartisan route.
Import-dependent retailers and manufacturers are a secondary watchlist if concrete tariff relief develops. I would not make that the lead trade while the president retains substantial delegated tariff powers (CRS).
The line I would build toward is: “The best businesses to watch may be the ones that no longer have to keep one eye on their customers and the other on Washington’s next threat.” That remains a hypothesis to test through enacted measures, agency behavior and company orders, not a reason to chase every stock wearing a blue tie.
As Boaty notes, these are candidates for us to look at more closely and we will do so in the Live Member Chat Room (Join us HERE) and today’s Live Trading Webinar, at 1pm, EST.
Remember, as we noted about Brazil’s election last week – nothing has actually changed this morning. We’re still stuck with the Congress we voted out until January 3rd and lame ducks can still quack – so nothing is set in stone and the official first session is from January 4th through January 20th – at which point they will take a well-deserved vacation after two full weeks of work… (end sarcasm font).
So don’t expect Project 2025 to be undone in Q4 or Q1 2027 because, unless Trump is visited by 3 ghosts this Christmas – the Oligarchs still hold 2 of the 3 branches of Government – but at least there’s a light!