Here's how Boaty and I arrive at a trade:
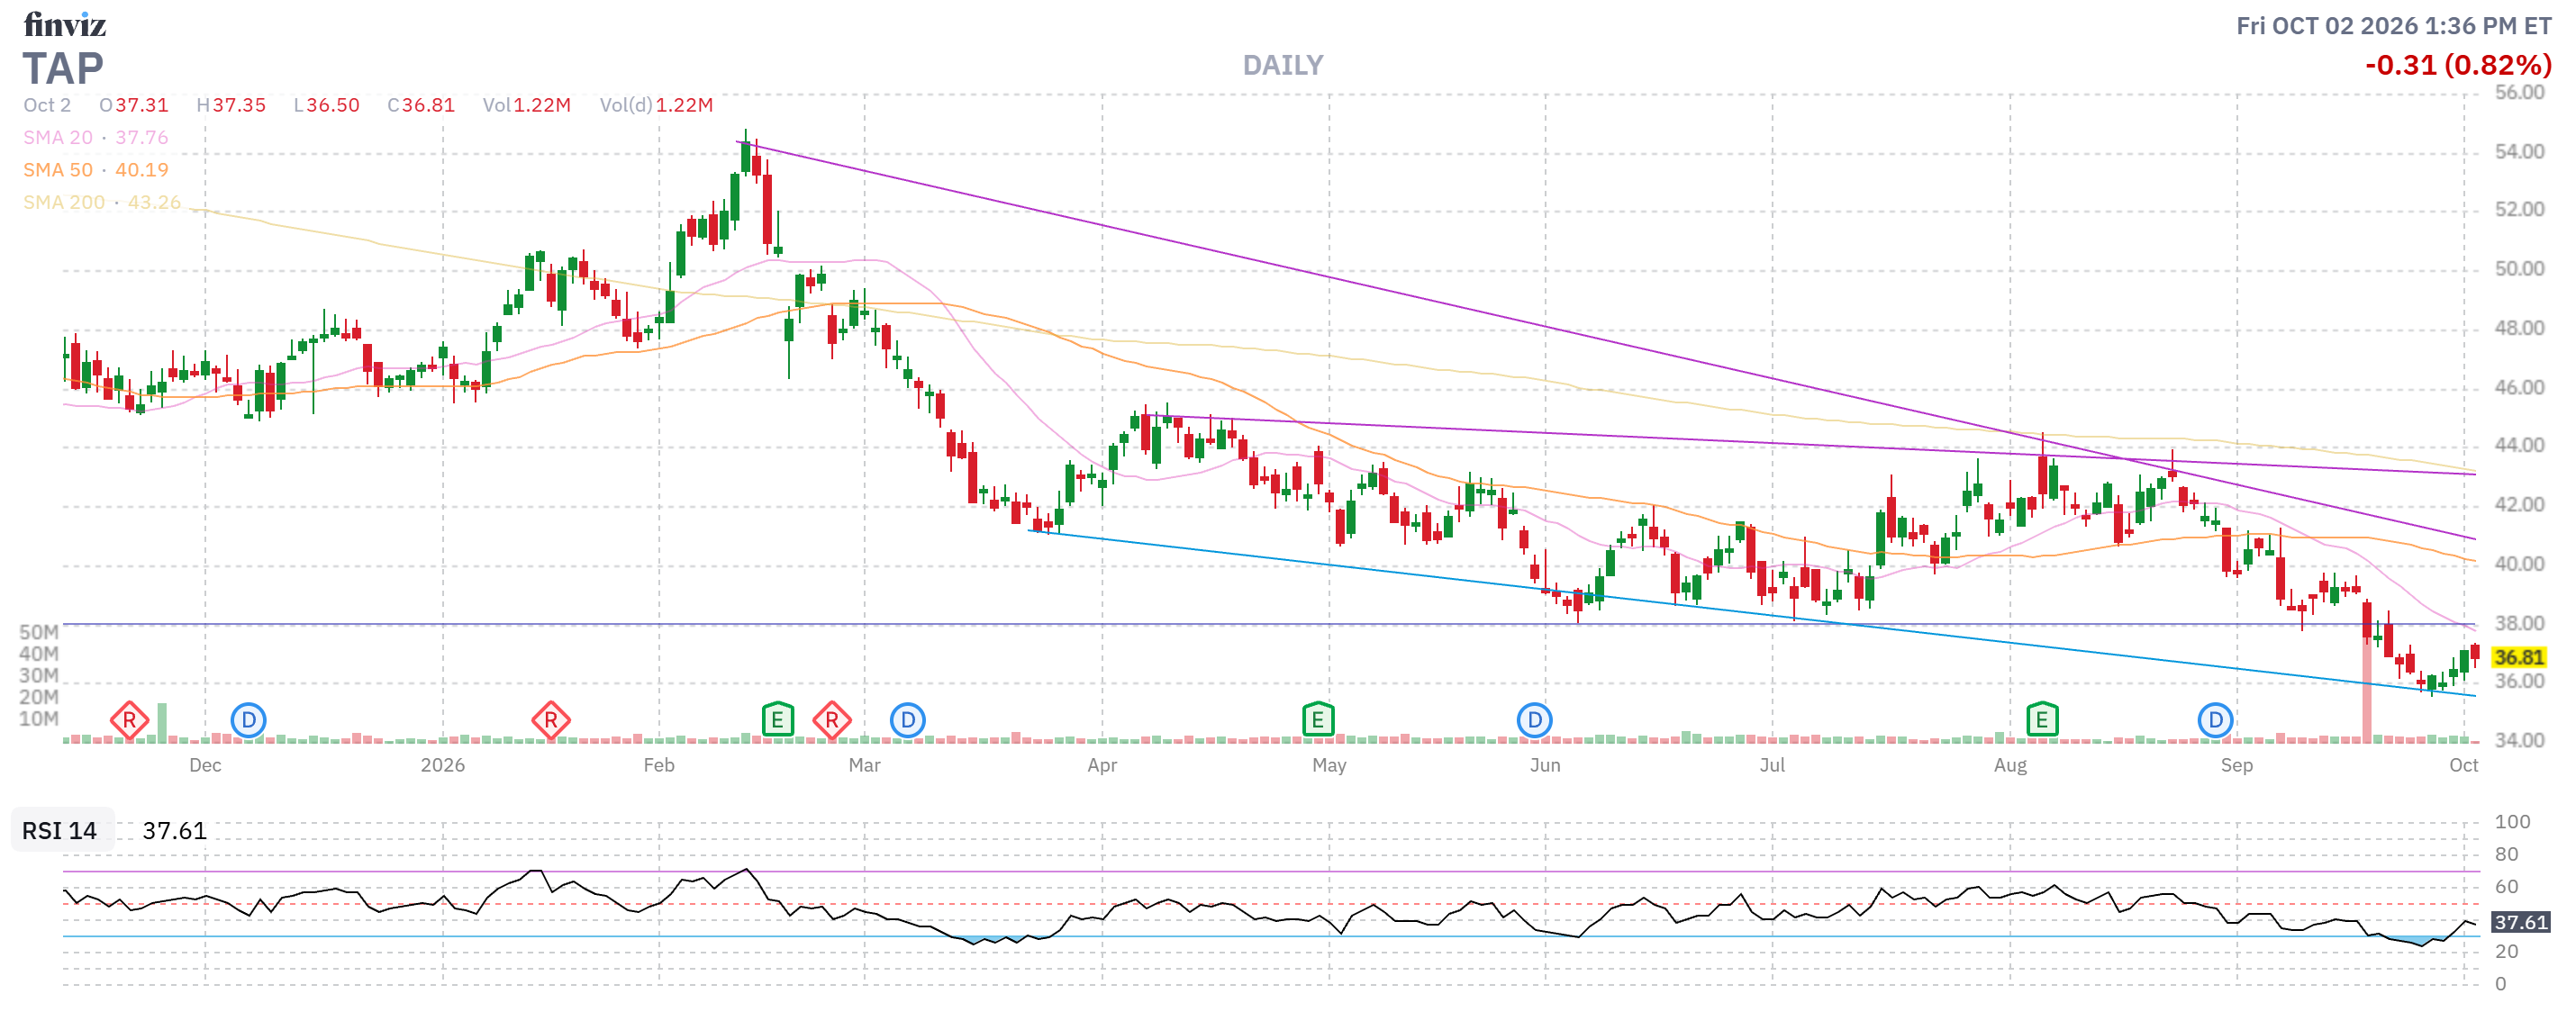
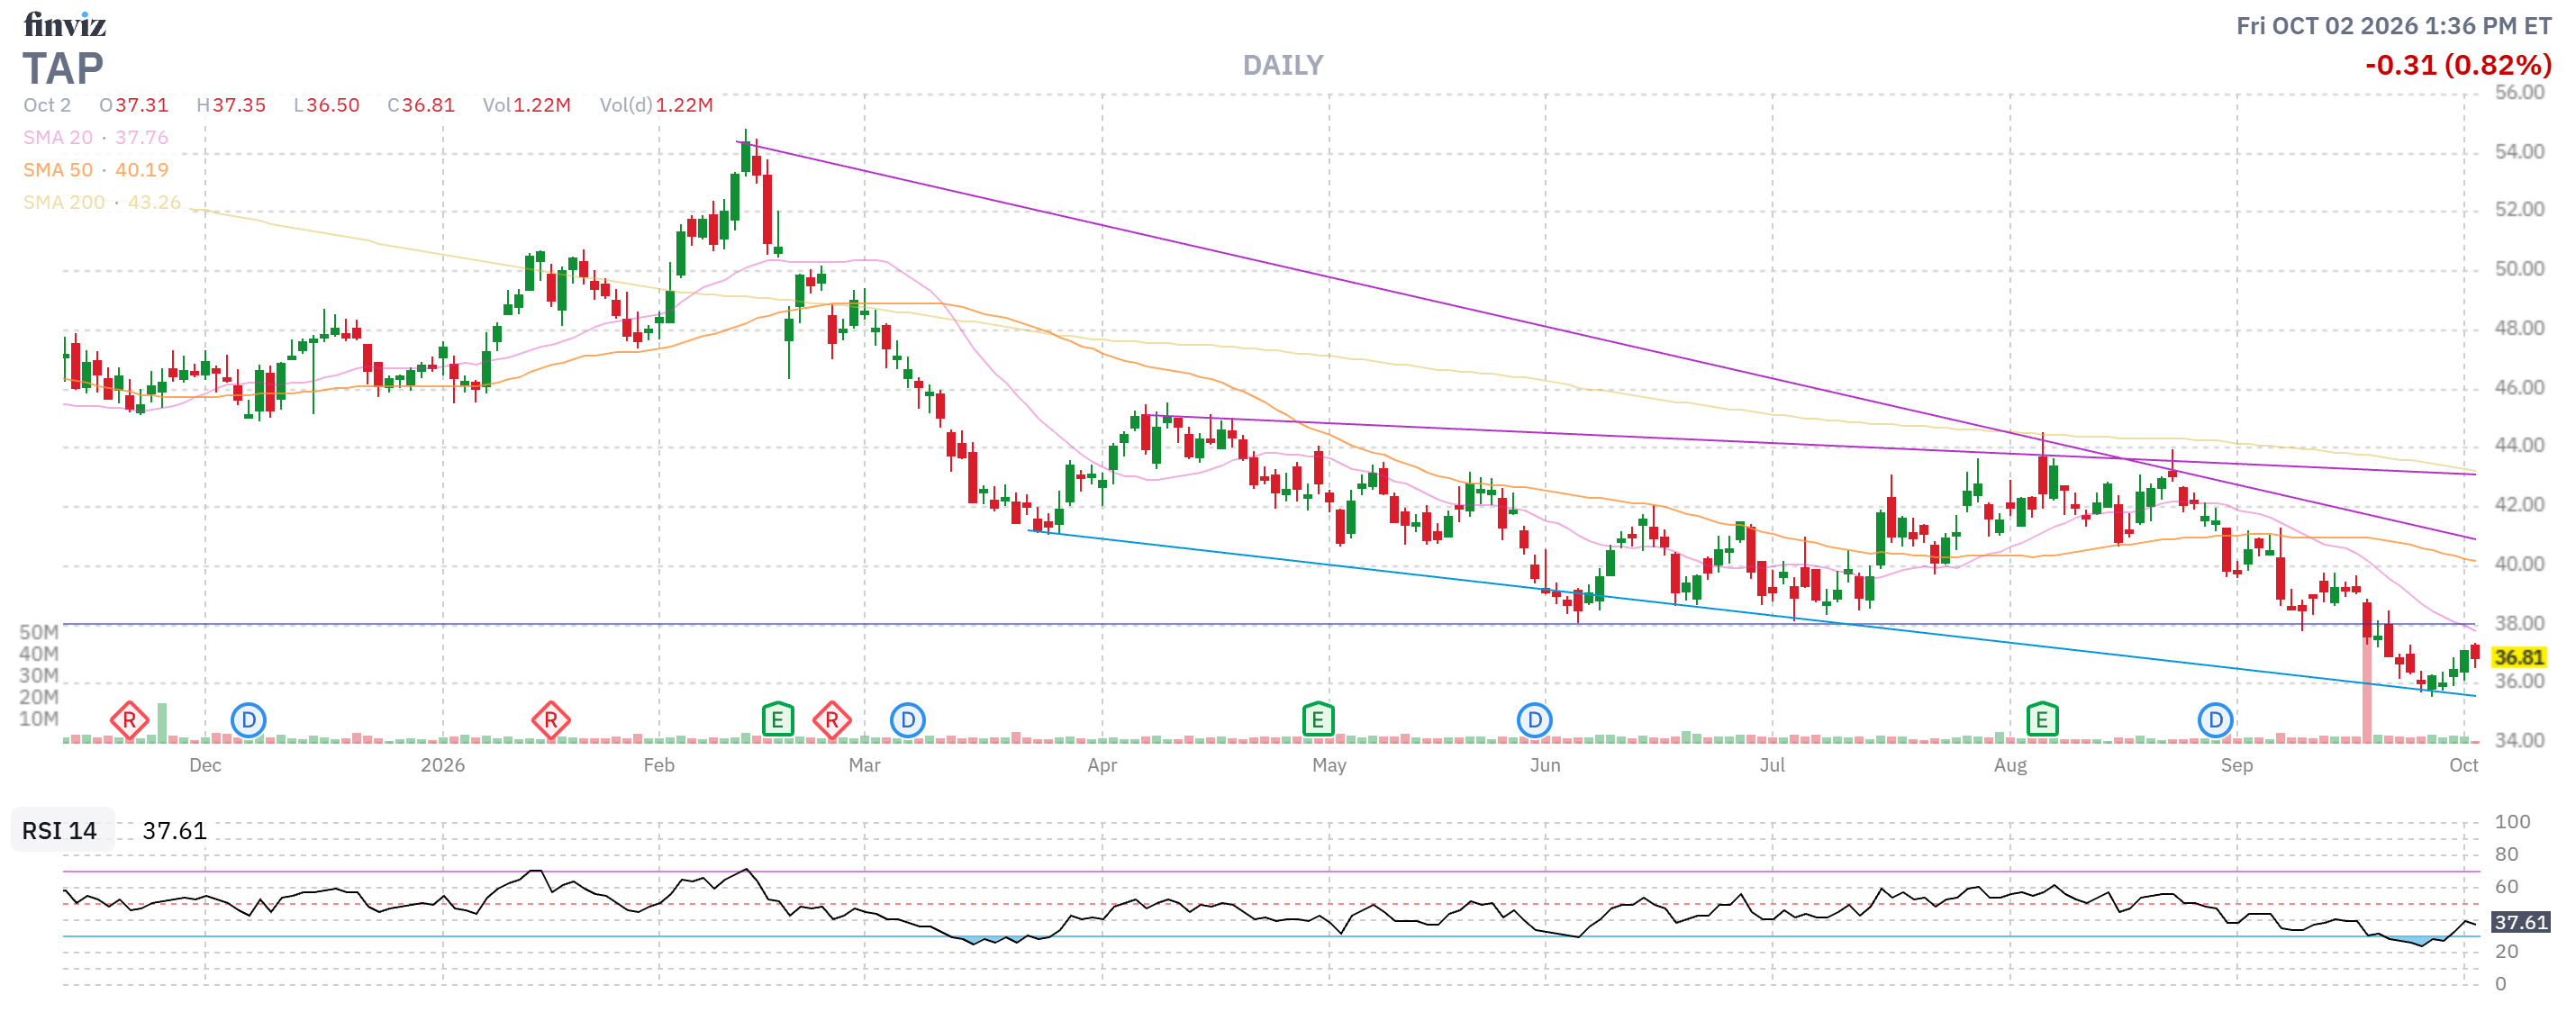
😎 TAP seems a bit too cheap though they did lose a ton of money last year (some sort of write-off I assume). GLPs, trade wars but they too are reducing share count. Debt seems a little scary but still, earning $800M for a $6.9Bn market cap?
🚢 Yes—TAP is cheap enough to deserve a serious look, and last year’s huge GAAP loss was primarily an accounting impairment, not a cash-burn disaster. But this is not the clean “$800M earnings for a $6.9B market cap” bargain until we separate sustainable earnings from declining beer volumes, consumer pressure, and a balance sheet that is manageable but no longer sleepy.
The write-off
Your assumption is correct. Molson Coors reported a 2025 GAAP net loss of $2.14B, but that was overwhelmingly driven by:
-
- A $3.65B non-cash partial goodwill impairment in its Americas reporting unit.
- A further $274M non-cash impairment of intangible assets, including Blue Run Spirits.
Without those charges, the company reported underlying EPS of $5.42 for 2025—not a GAAP loss-making operating business.
That impairment still matters conceptually. It means management concluded that the carrying value of the Americas business exceeded its estimated fair value. In plain English: the company paid too much for prior assets or its expectations for those assets had fallen.
But it does not mean $2.14B of cash evaporated in 2025.
The actual valuation
At around a $6.9B market capitalization, TAP is inexpensive on normalized earnings:
\$800\text{M} \div \$6.9\text{B}
\approx 11.6\% \text{ earnings yield}
That is about 8.6x earnings—cheap for an established beverage franchise, especially when it pays a dividend and is retiring stock.
But the market is assigning a low multiple because it sees earnings at risk, not because it forgot arithmetic:
-
- Q2 2026 sales fell about 3.3%–3.6% year over year.