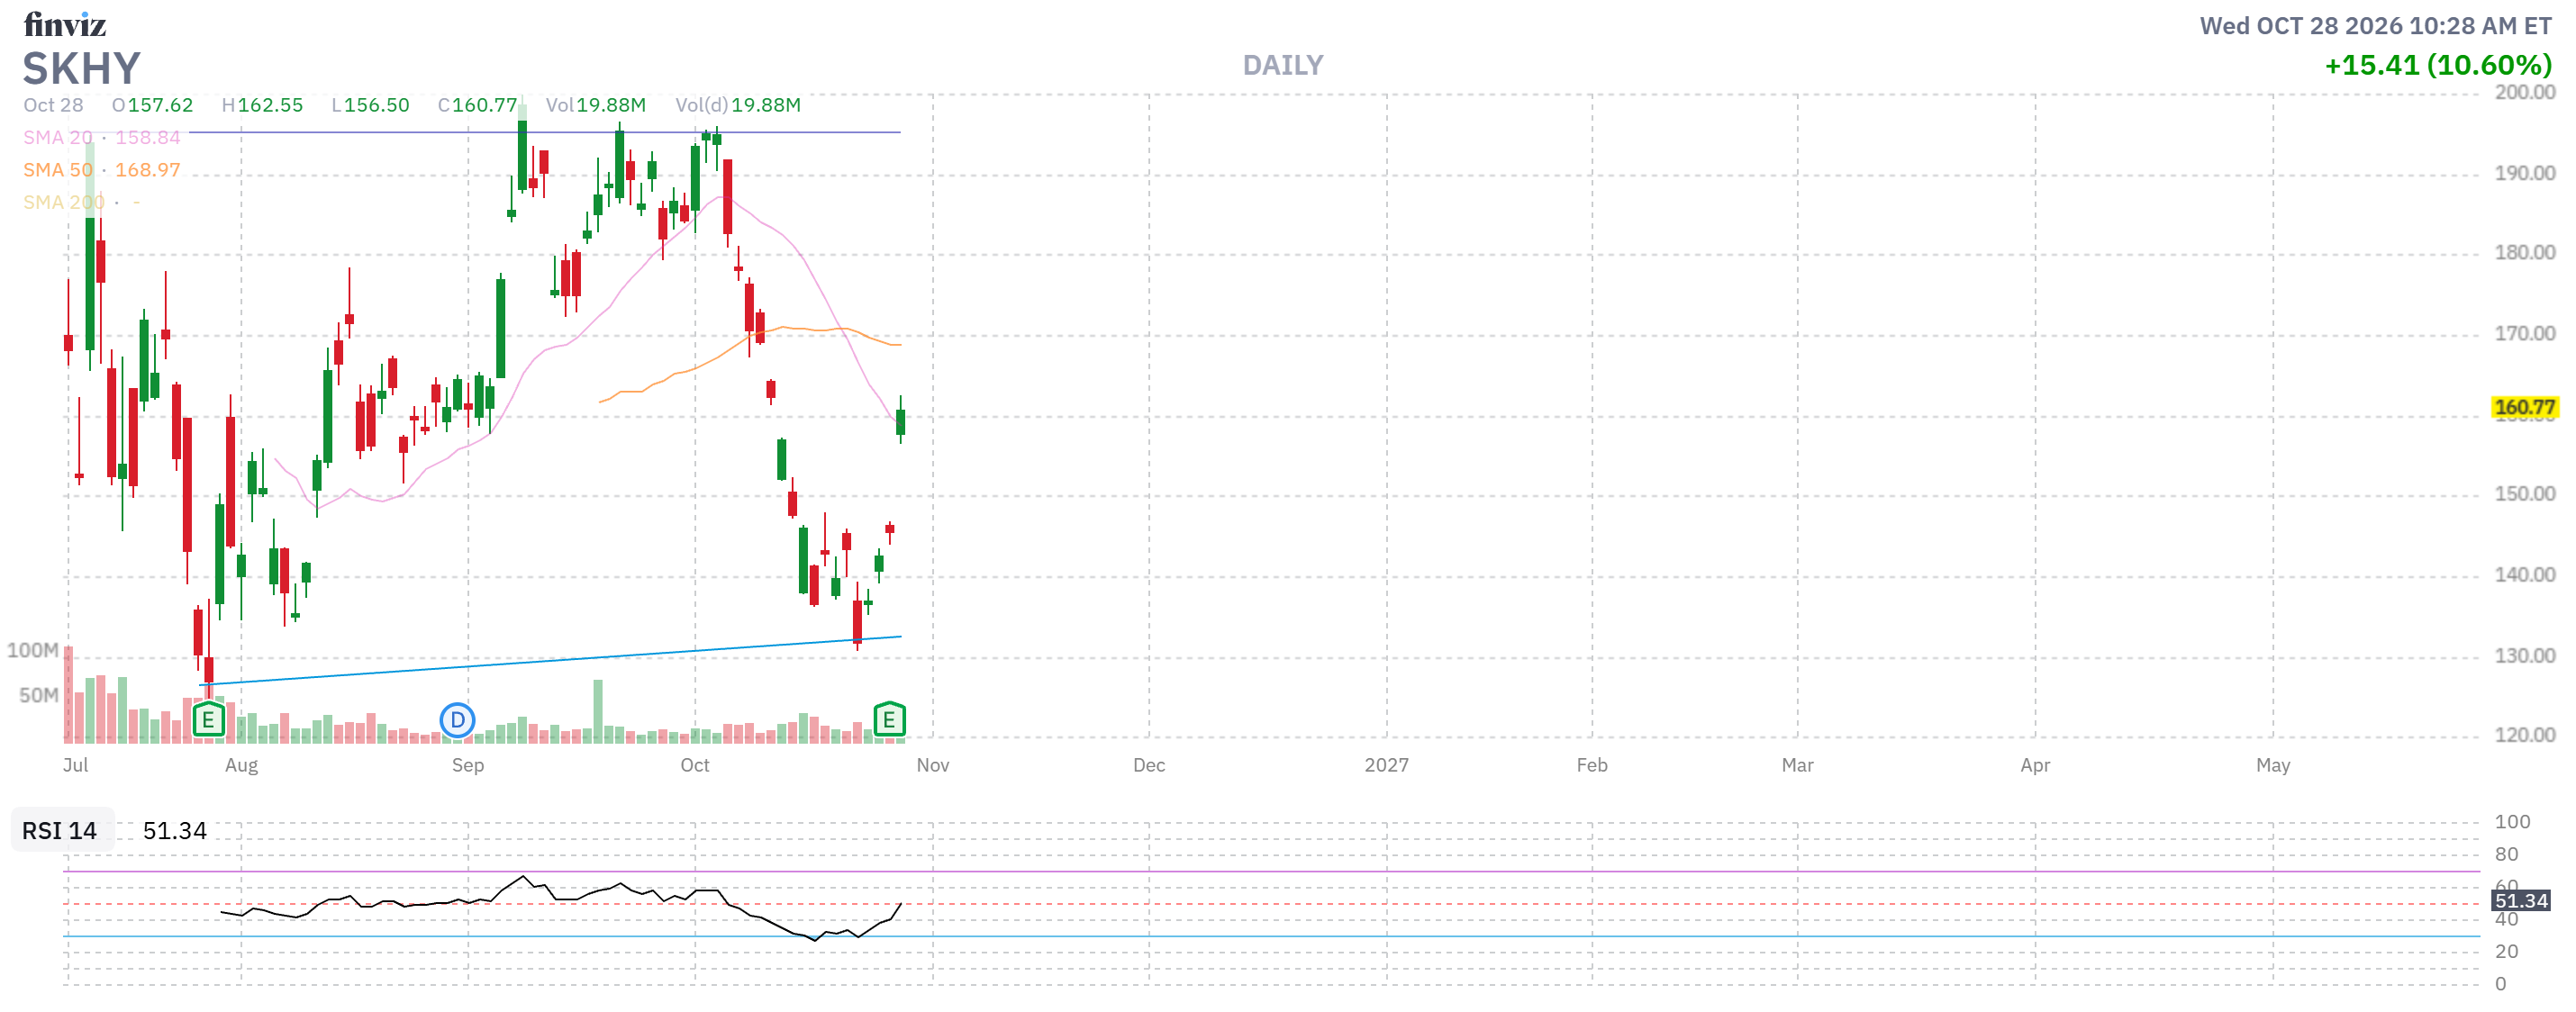
Here’s one we should play:
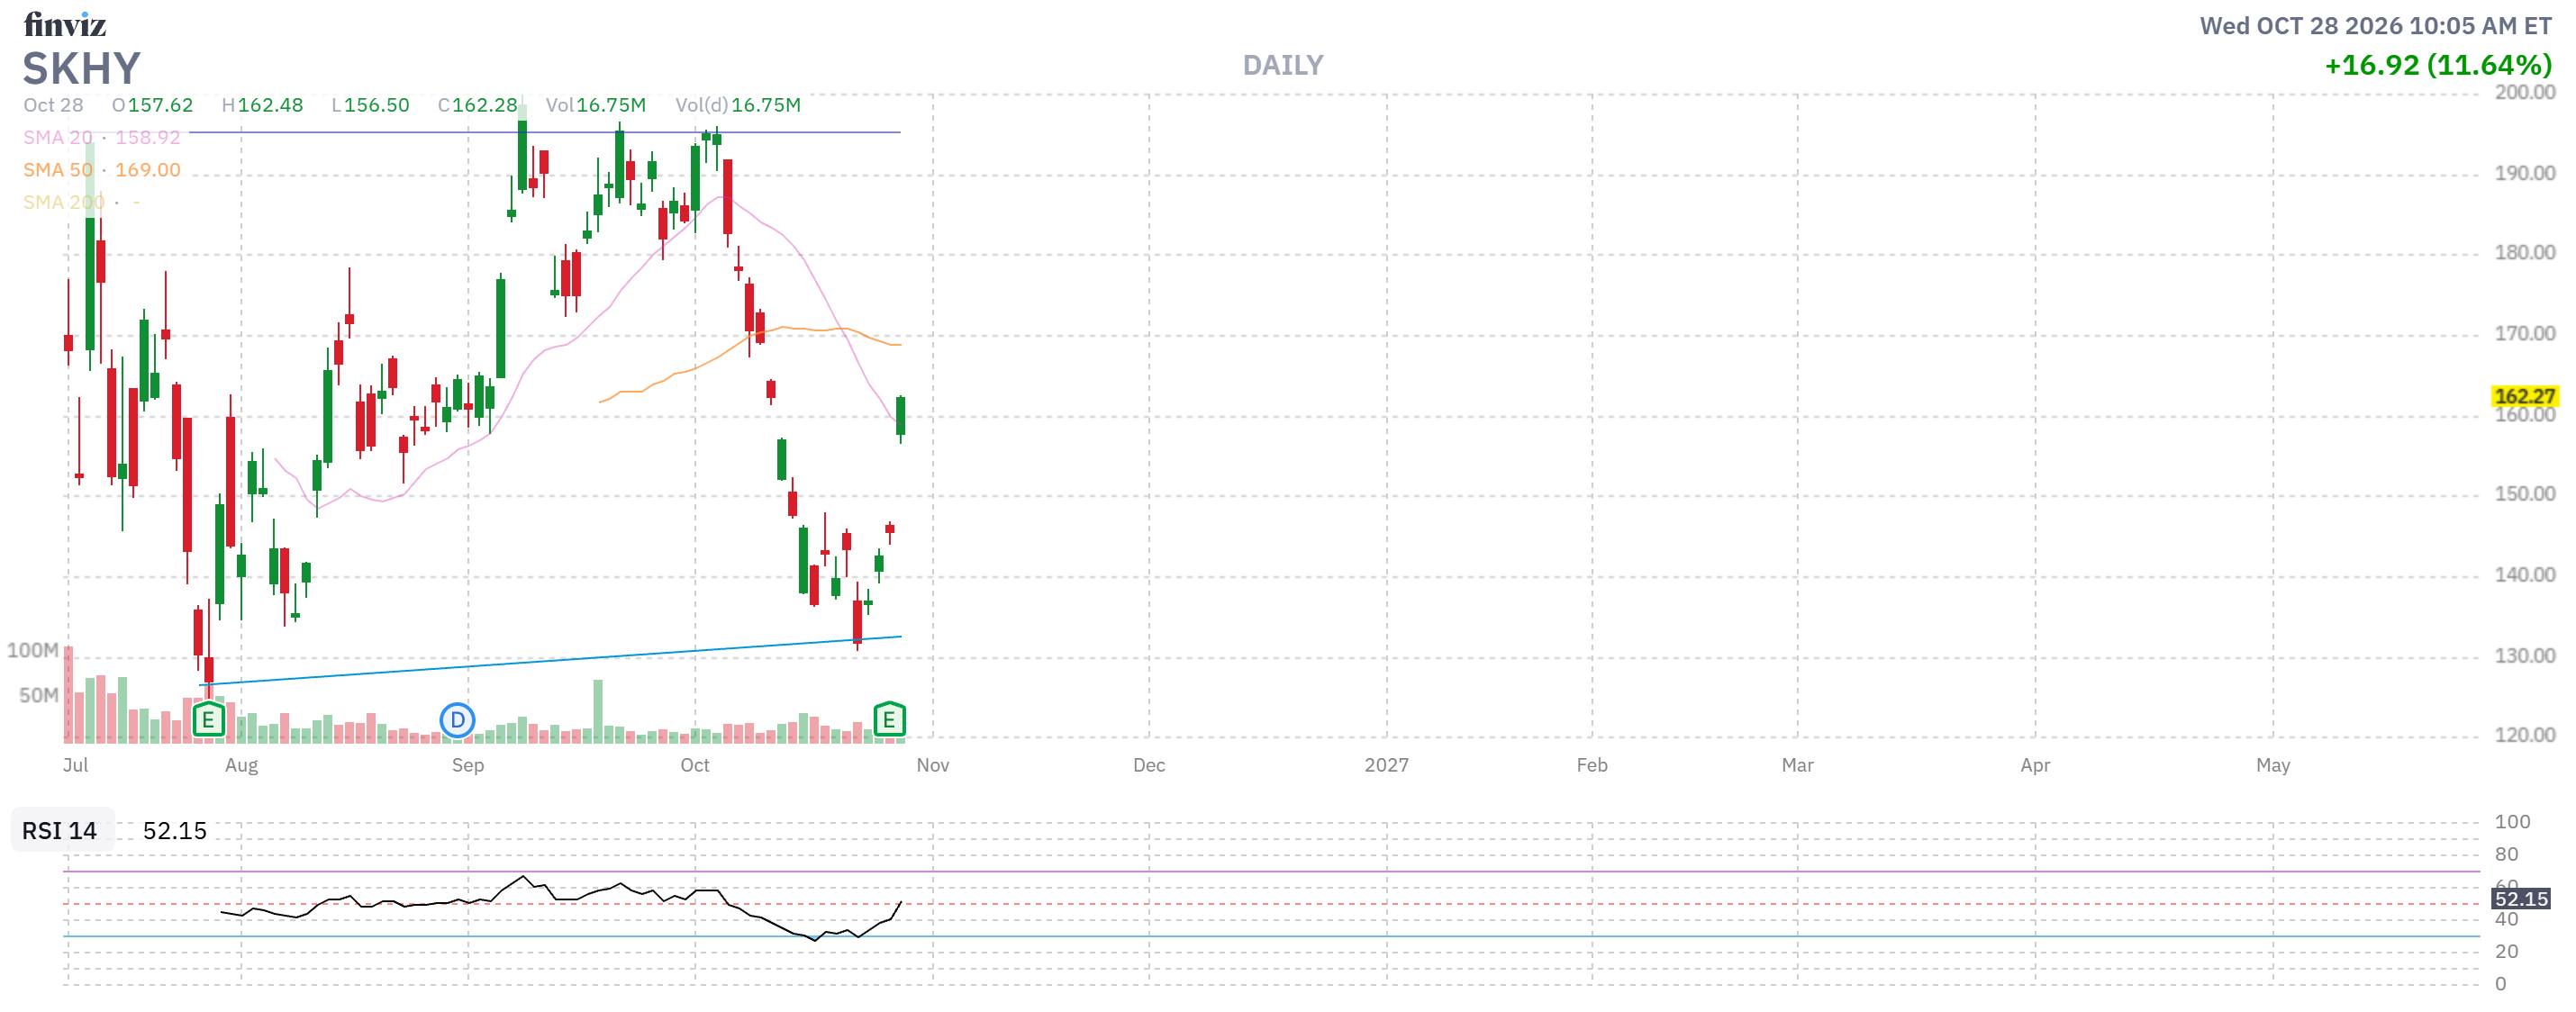
♦️ Rosenblatt raises SK Hynix target to $400 after Q3 beat, stronger DRAM pricing, reiterates Buy rating
-
- Rosenblatt lifted its price target from $320, implying about 175% upside from Tuesday’s close.
-
- SK Hynix beat Q3 2026 estimates with ADR EPS $4.21 and revenue $79.0B.
-
- Company says DRAM and HBM capacity is sold out through 2029.
-
- Q3 operating profit jumped 632% YoY to 83.33 trillion won, driven by strong AI-related memory demand.
-
- Q3 net profit rose 216% year-on-year to 39.77 trillion won but came below analyst expectations.
-
- Company plans 100 trillion won (about $75.5B) shareholder returns this year via dividends and repurchases.
-
- New 20 trillion won stock repurchase this year follows 40 trillion won buyback program announced in August.
-
- Company expects AI-driven memory demand to outstrip supply until 2030, indicating prolonged memory shortages.
-
- Deals with 14 customers cover over half of SK Hynix’s 2027–2028 memory production capacity.
-
- Investing.com and AP cite Anthropic’s IPO and future AI memory demand as key drivers for Asian chipmakers.
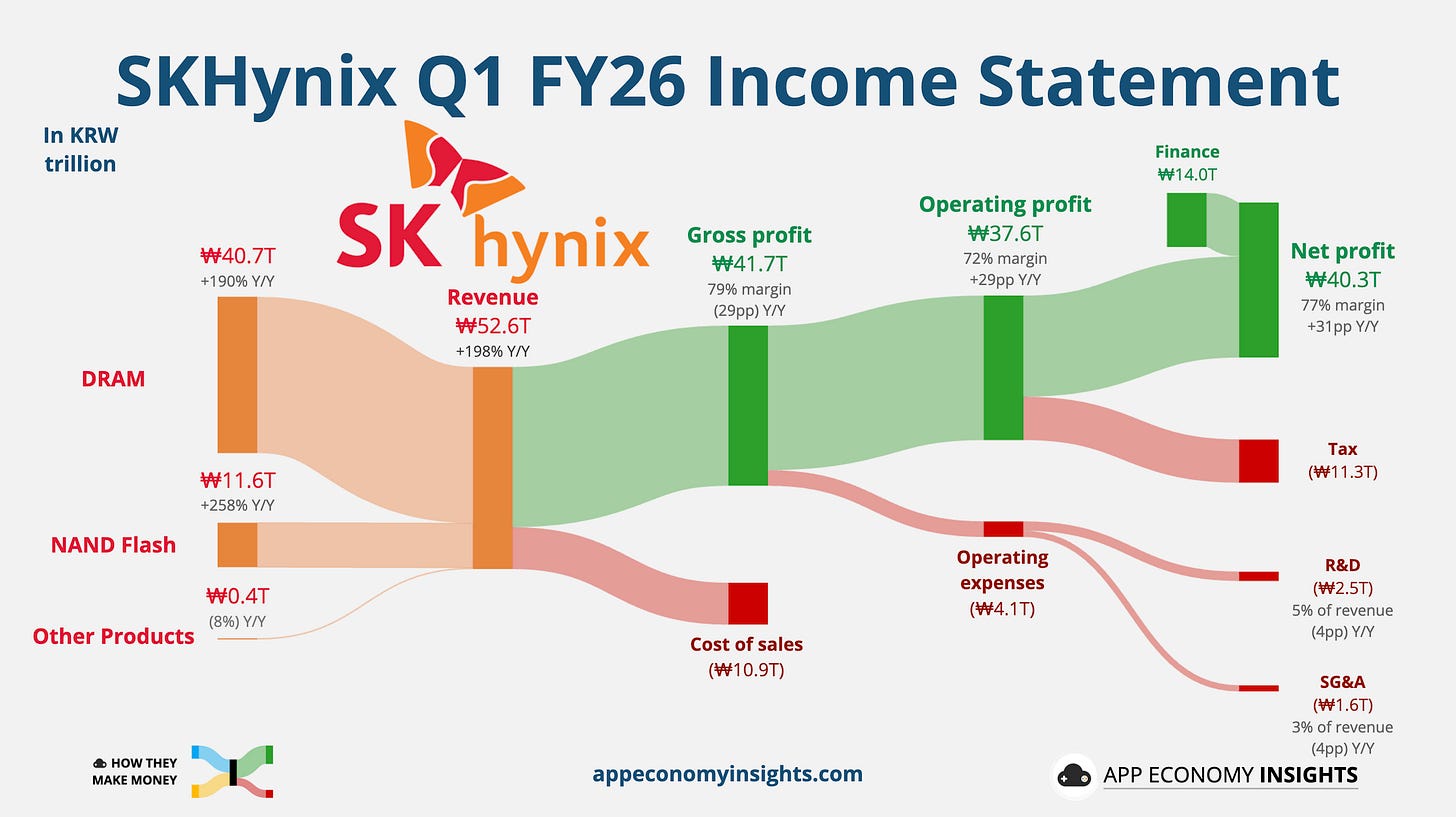
🚢 SK Hynix (SKHY): The Cheapest AI Pick-and-Shovel Has an Asterisk
SK Hynix makes the memory that AI runs on. Every Nvidia accelerator needs stacks of high-bandwidth memory (HBM) sitting next to the processor, and SK Hynix has led that market since it began. It held 50% of HBM revenue in Q2, with Samsung at 33% and Micron at 18%. It also makes regular DRAM for servers and phones, plus NAND flash for enterprise SSDs. All three are in short supply, and the prices show it. DRAM selling prices rose by a high-20s percentage and NAND by the mid-20s in a single quarter.[trendforce][chosun]
That’s how a memory maker posts an operating margin of 80%. Q3 revenue was 104.6 trillion won, up 328%, and operating profit was 83.33 trillion won, up 632%.