This started out as a Warren selection:
KeyCorp (KEY)
-
- Original Date: September 14, 2026
- Context: Recommended by Warren 2.0 in the Monday Morning Report after KeyCorp raised its 2026 revenue and Net Interest Income (NII) guidance at the Barclays Financial Services Conference.
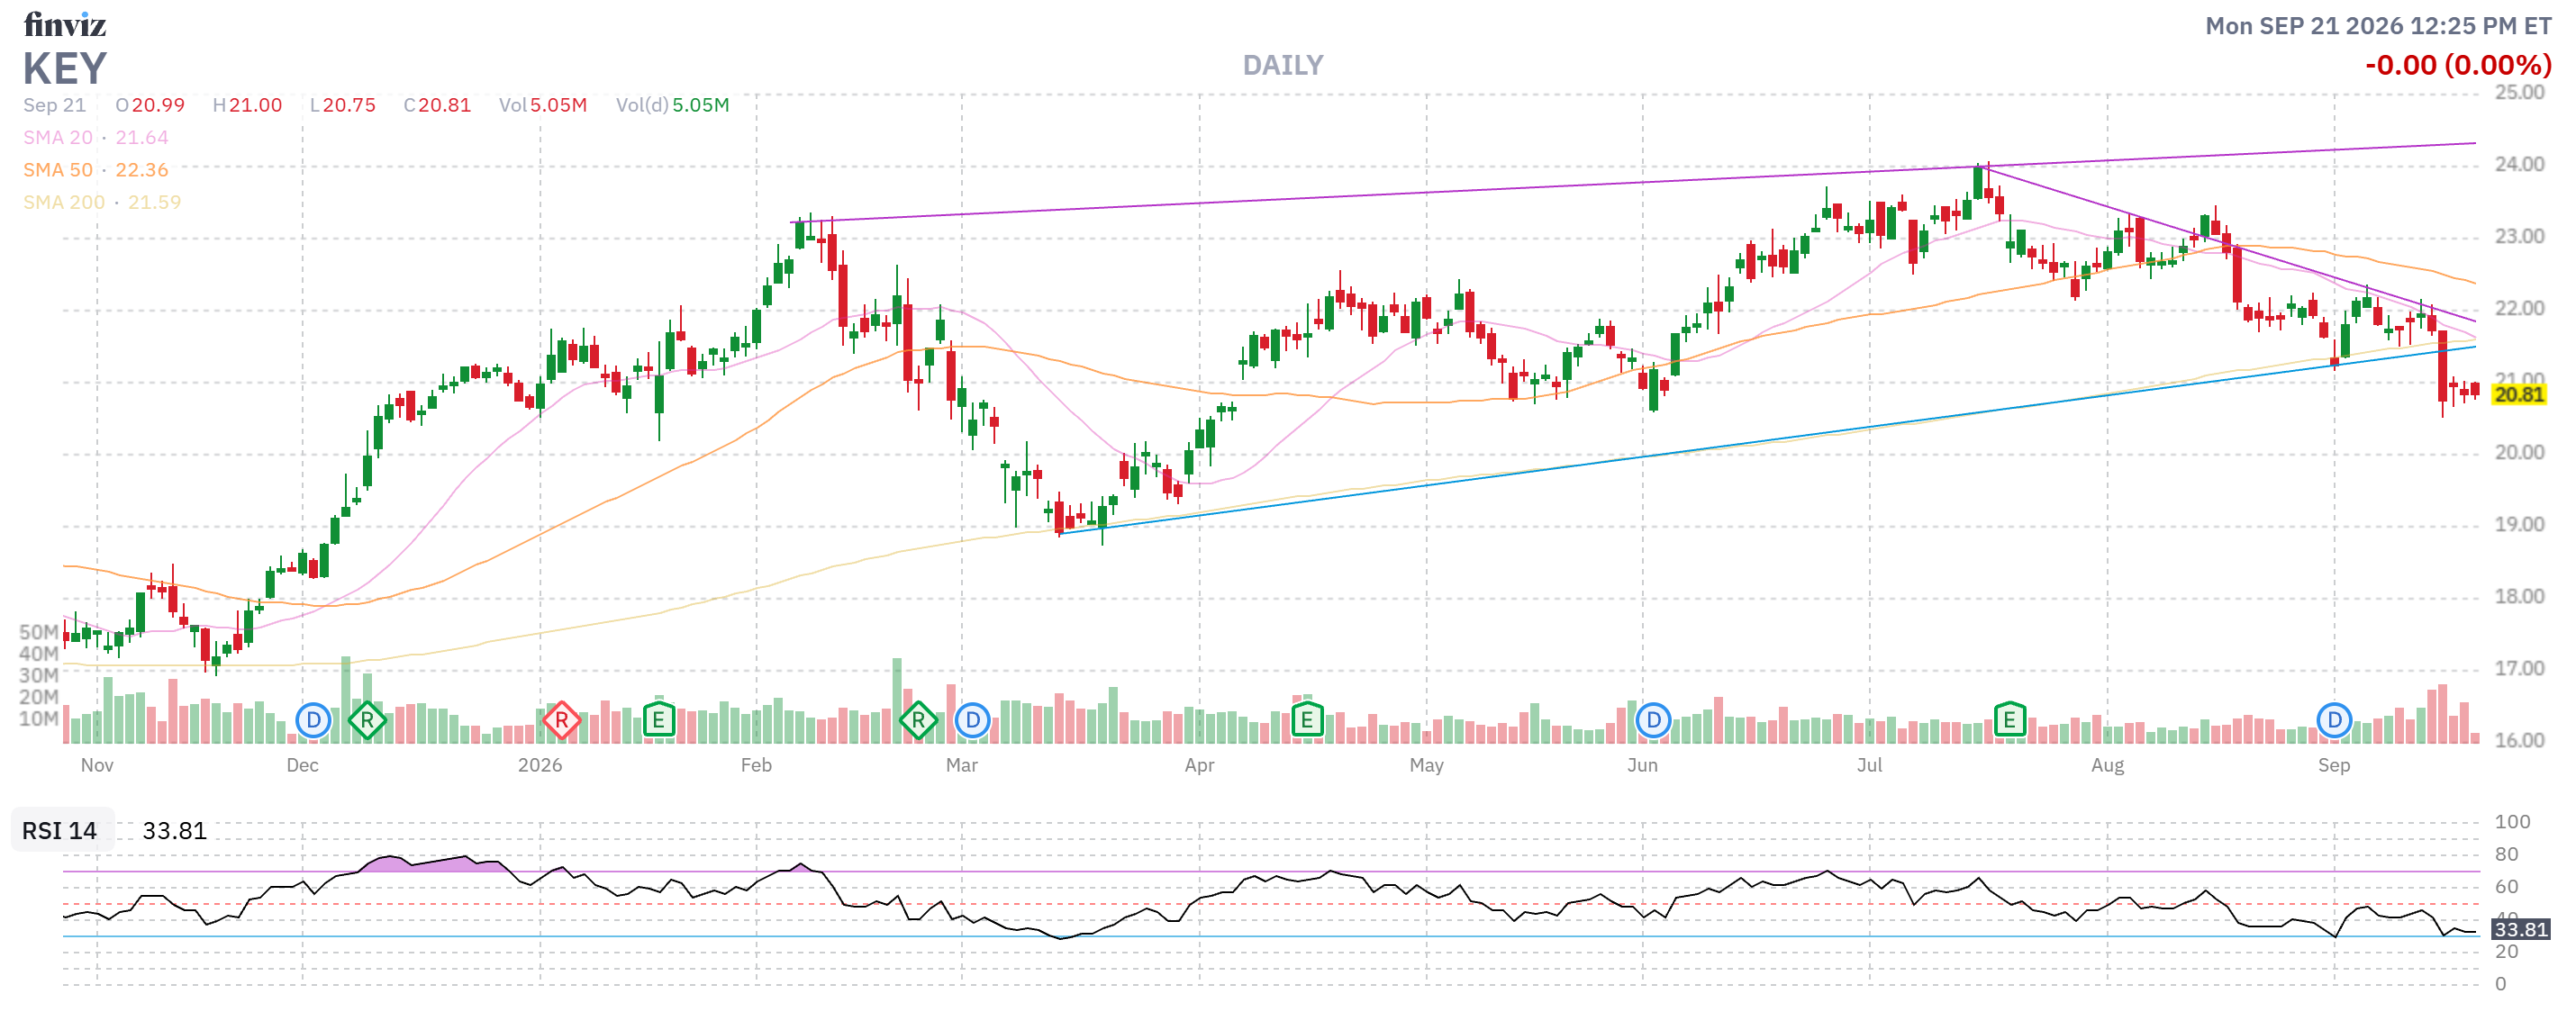
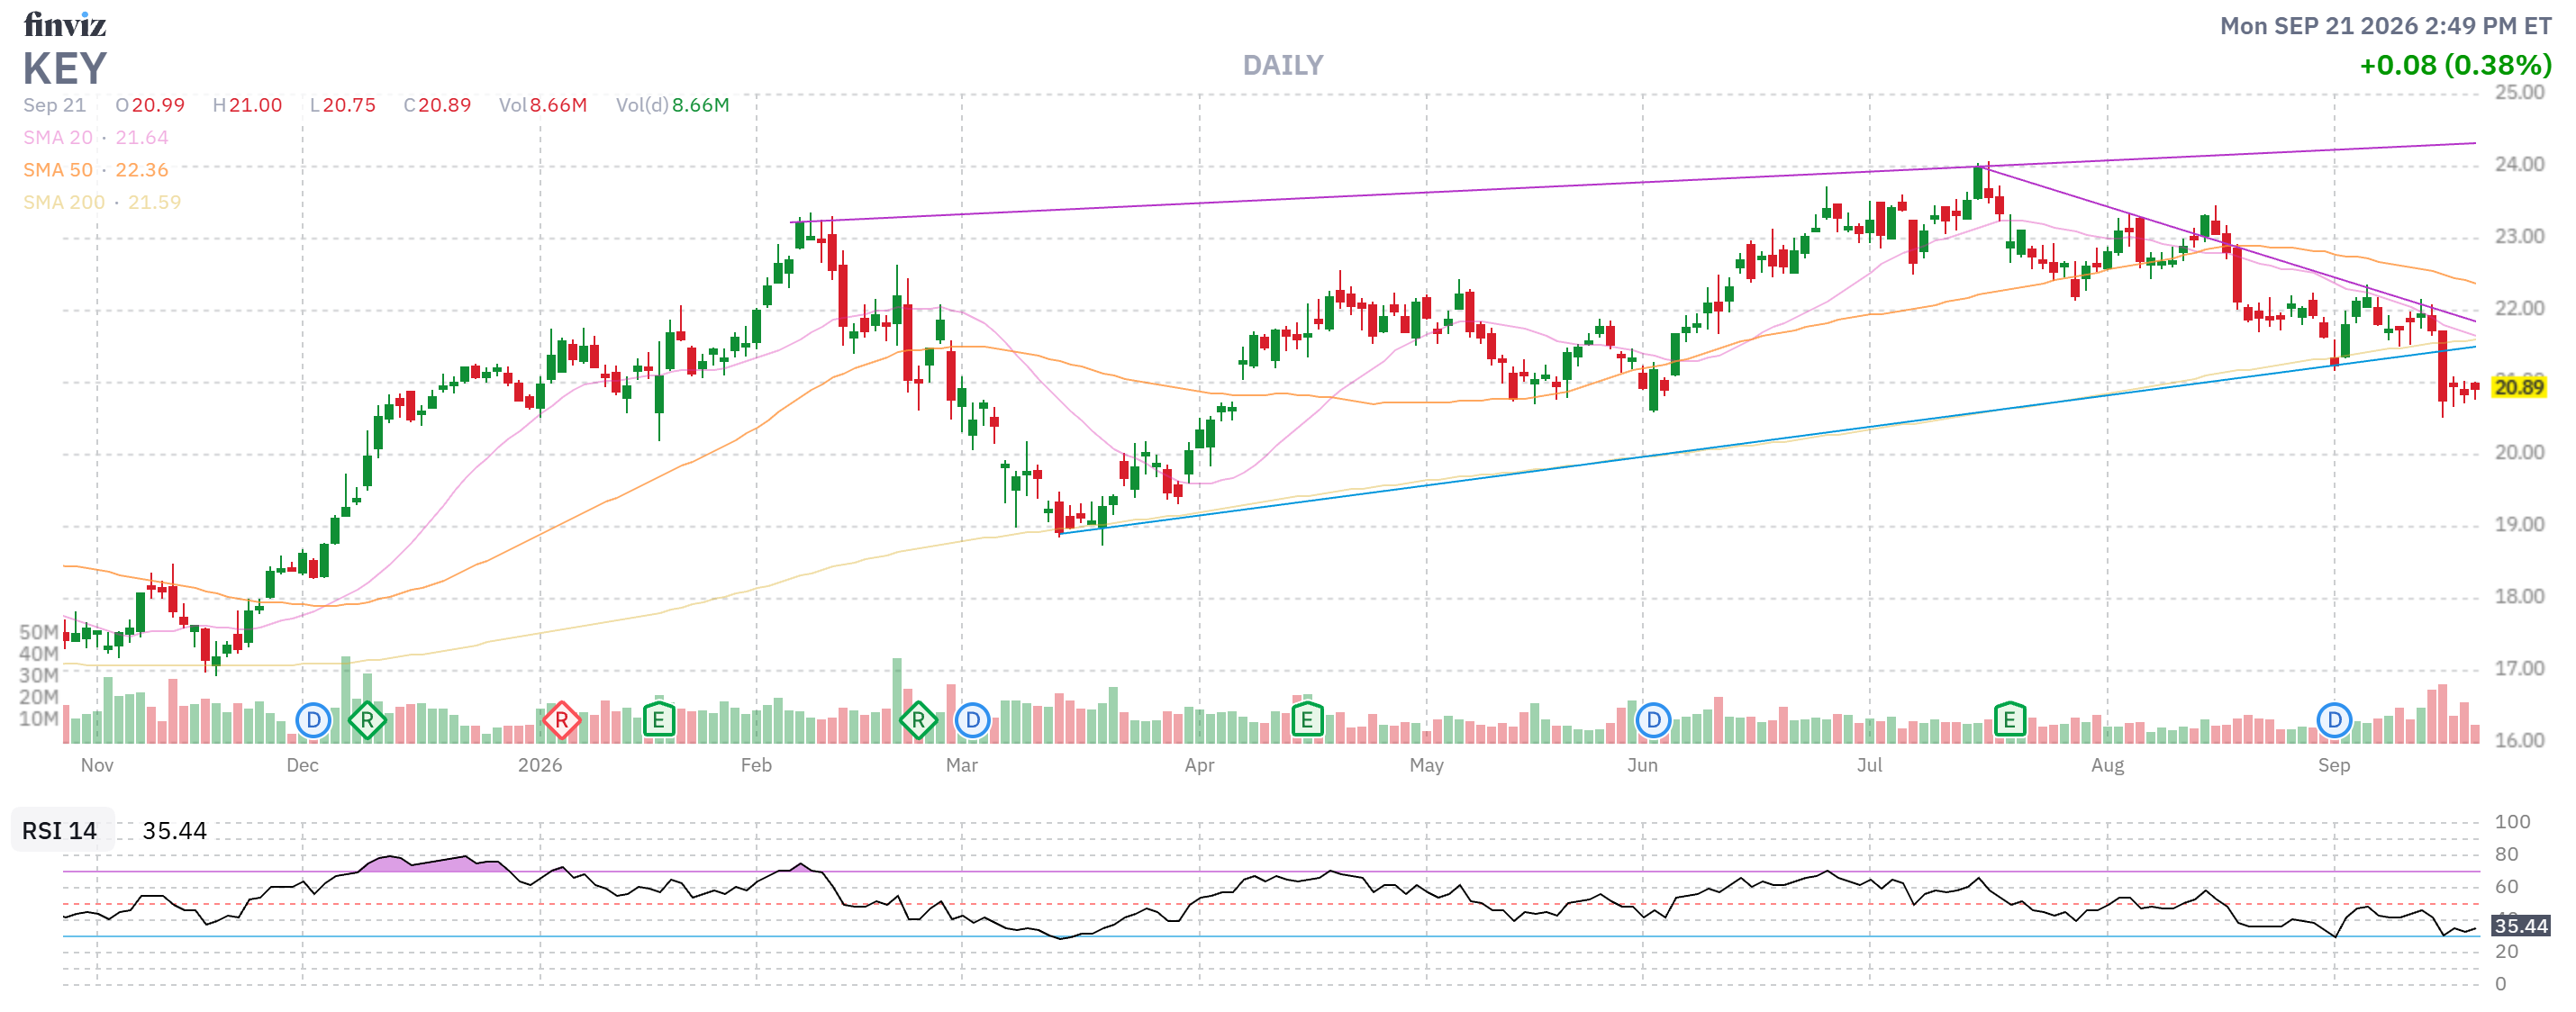
They sold off a bit since then so we updated it this morning:
-
- Screening Category: Regional Banking & Higher-for-Longer Yields
- The Thesis: As 10-year Treasury yields touched 5.00%, regional banks with pristine credit profiles emerged as primary beneficiaries of expanding net interest margins. KeyCorp trades at a very modest earnings multiple while maintaining a clean balance sheet.
- The Catalyst: Management raised full-year 2026 guidance at the Barclays Financial Services Conference in mid-September. KEY increased its 2026 revenue growth target to ~8% (up from 7%) and bumped its Net Interest Income (NII) growth target to 9%–11% (up from 8%–10%), signaling accelerating bank profitability in a tight rate environment.
And then Boaty and I dug deeper:
🚢 KeyCorp (KEY) is a more credible candidate than the “regional banks win automatically when the 10-year hits 5%” pitch implies—but the raised guidance is real, and the underlying loan and margin momentum is meaningful.
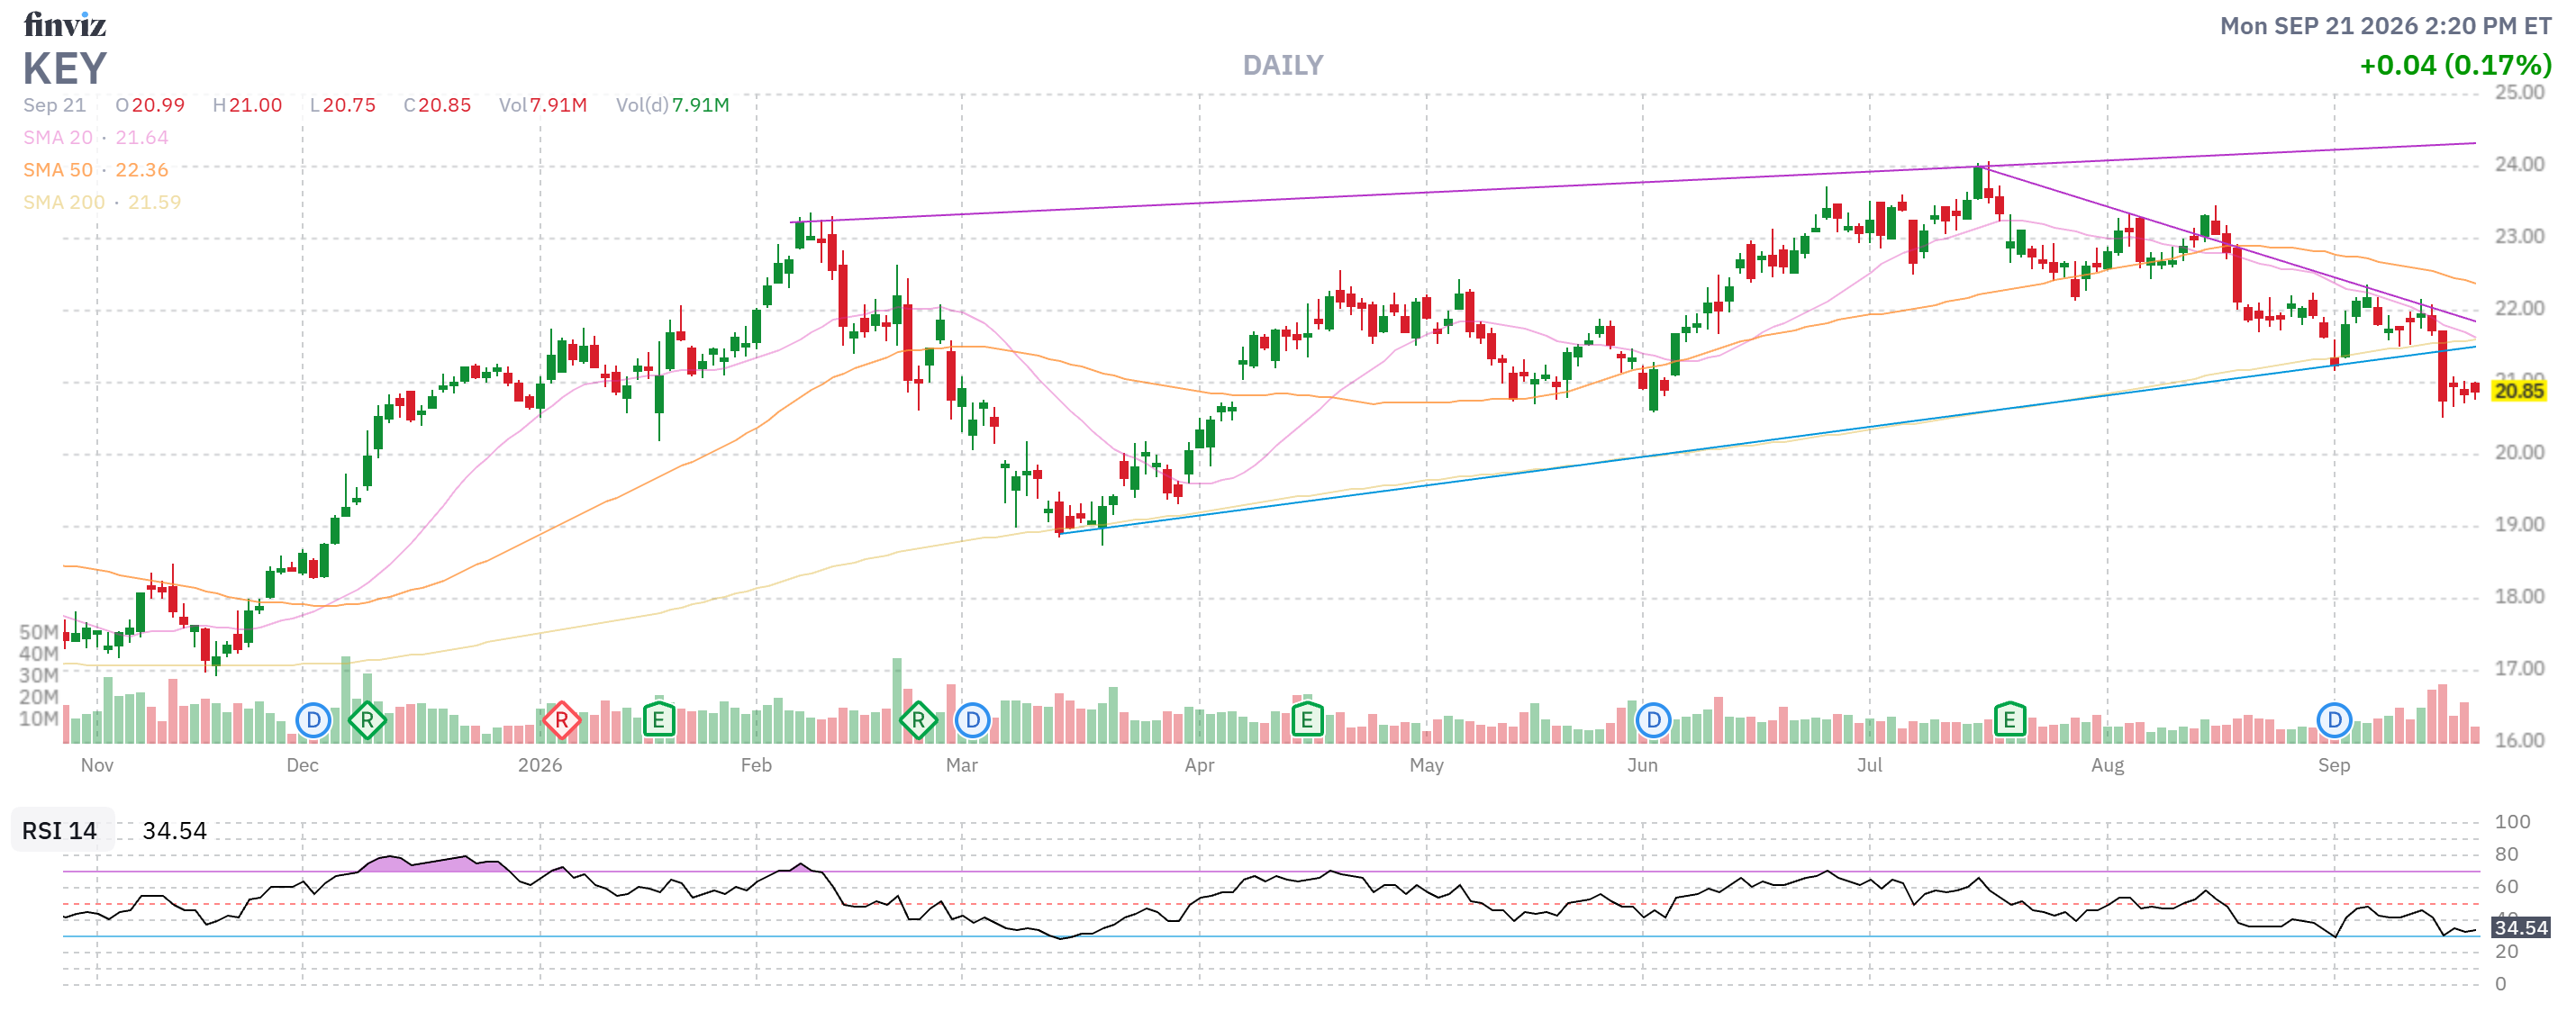
It is a qualified value/income candidate, not yet an automatic Top Trade Alert, because the same higher-for-longer environment that lifts net interest income can eventually damage borrowers, securities marks, capital, and commercial real estate.
My early verdict: put KEY on the active short list, ahead of SIRI and HAFN for a conservative portfolio structure. It has a cleaner path to near-term earnings growth, a modest valuation, and a specific operating catalyst. But we need to be honest that “pristine credit profile” is too strong, and we should insist on a favorable entry/basis.
What KeyCorp Is
KeyCorp is a Cleveland-based regional bank with roughly $190 billion in assets.